Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
 @aleabitoreddit
Sep 08, 2026 · 03:56 ET
stock
1st mention
trade
position
📈 market call
So $INTC is raising PC CPU prices by 10% apparently in October per Digitimes, which I think markets might appreciate.
The legacy memory trade also just going brrr from August revenues:
-> ESMT revenue up ~+605% Y/Y, 16.4% M/M
Which is interesting given gross margins also rising tremendously too.
-> Etron revenue up +525% Y/Y, +6.4% M/M
Chairman says he sees growth momentum in memory to extend through 2028 or longer, potentially 2030. (which is very positive read through for ESMT given what Etron sells) *own ESMT/Etron
-> Winbond revenue up +289.43% Y/Y, up 2% M/M
Their president says memory supply and demand are expected to be even tighter in 2027 than in 2026.
-> Macronix revenue up +218.5% Y/Y, +5.4% M/M
Says SLC NAND, eMMC, NOR remain tight (kinda known there).
So... if you think your 80%-100% type revenue growth players are insane.
Check out legacy memory (operating income is even more hilarious). There's a few more where ~ modeled forward P/E values of like 2-3 from my estimates.
I personally find the theme a better value investing type idea than your 16 P/E no-growth dividend companies.
$INTC$ESMT$ETRON$WINBOND$MACRONIX
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $INTClong |
+1.7% | -7.0% | — | — | +15.1% |
| $ESMTlong |
— | — | — | — | — |
| $ETRONlong |
| | | | |
| $MACRONIXlong |
| | | | |
| $WINBONDlong |
| | | | |
I get like 100 of these types of questions a day, I can’t just answer all of them.
Since you’ve asked 12 times: yes I still have exposure to all of them.
Cost averaged on a few, so as of today positions on:
Foci are up 53%
Xintec are up 53.1%
But still down -23% on Shunsin, -22% on Msscorp.
Main position I trimmed the most at a loss for tax harvesting was Auros after hybrid bonding industry delays.
I like to post thesis ideas, but try to keep portfolio management stuff private like tax loss harvesting or trimming.
I’ll post thesis research updates, like $TSM coupe confirming partnership with Shunsin. Or FAU bottleneck validation on Foci. Or hybrid bonding delays.
But in the end people should make their own decisions
$TSM$FOCI$XINTEC$SHUNSIN$MSSCORP$AUROS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $TSMlong |
+2.4% | +1.0% | — | — | +6.6% |
| $AUROSshort |
| | | | |
| $FOCIlong |
| | | | |
| $MSSCORPlong |
| | | | |
| $SHUNSINlong |
| | | | |
| $XINTEClong |
| | | | |
I asked OpenAI Astra Ultra + Anthropic Fable 5.1 Max to make me a 5x-10x return type portfolio in 1 year.
Burnt a lot of credits, and the results are in:
OpenAI: - $KYTX (autoimmune CAR-T results)
- $PRQR (human RNA-editing datasets)
- $VSTM (KRAS cancer-drug)
- $CNTB (asthma and COPD)
- $RANI (oral biologics)
- $IVA (MASH)
- $SILC (networking + inference hardware)
- $AMPX (batteries)
- $EOSE (batteries)
- $ZVRA (rare-disease drug growth)
Anthropic: - $INO (respiratory papillomatosis)
- $CAPR (PDUFA for deramiocel)
- $GOSS (seralutinib)
- $SLS (Phase 3 binary)
- $IREN (familiar face)
- $WULF (familiar face)
- $OKLO (nuclear)
- $SMR (nuclear)
- $RGTI (quantum)
- $QBTS (quantum)
*Disclosure don't own any of these aside from 1 share in IREN, not a recommendation, just TLDR of LLM output for educational purposes.
So very interesting results:
Our beloved AGI Astra prefers really obscure biotech I've never heard about. And a few familiar names like $EOSE and $AMPX.
And Fable... yeah idk, feels like it learned a little too much from /r/wallstreetbets and X but maybe it's right, who knows.
Anyway no judgement, I'll save this and revisit it in a few months. If one of them actually delivers... I'll be impressed.
↗ Quoting @aleabitoreddit
$KYTX$PRQR$VSTM$CNTB$RANI$IVA$SILC$AMPX$EOSE$ZVRA$INO$CAPR$GOSS$SLS$IREN$WULF$OKLO$SMR$RGTI$QBTS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMPXlong |
+5.1% | -4.6% | — | — | -2.1% |
| $CAPRlong |
-3.6% | -11.0% | — | — | +0.7% |
| $CNTBlong |
+3.8% | +10.9% | — | — | -40.2% |
| $EOSElong |
+10.8% | +1.8% | — | — | -21.0% |
| $GOSSlong |
+2.6% | -23.5% | — | — | -14.2% |
| $INOlong |
-0.7% | -12.6% | — | — | -14.0% |
| $IRENlong |
+5.0% | -1.9% | — | — | -8.5% |
| $IVAlong |
-2.3% | -15.9% | — | — | -31.2% |
| $KYTXlong |
-2.2% | -12.0% | — | — | -17.5% |
| $OKLOlong |
+4.9% | -12.2% | — | — | -10.3% |
| $PRQRlong |
-1.0% | -10.1% | — | — | -20.3% |
| $QBTSlong |
+6.6% | +1.3% | — | — | -0.1% |
| $RANIlong |
+0.8% | -2.6% | — | — | -8.6% |
| $RGTIlong |
+4.0% | +0.5% | — | — | +3.5% |
| $SILClong |
+6.2% | +3.4% | — | — | +28.5% |
| $SLSlong |
+0.7% | -16.7% | — | — | -11.2% |
| $SMRlong |
+15.3% | -11.2% | — | — | -18.6% |
| $VSTMlong |
-1.5% | -10.7% | — | — | -1.8% |
| $WULFlong |
+8.2% | +1.4% | — | — | -10.4% |
| $ZVRAlong |
+2.2% | -3.1% | — | — | -8.5% |
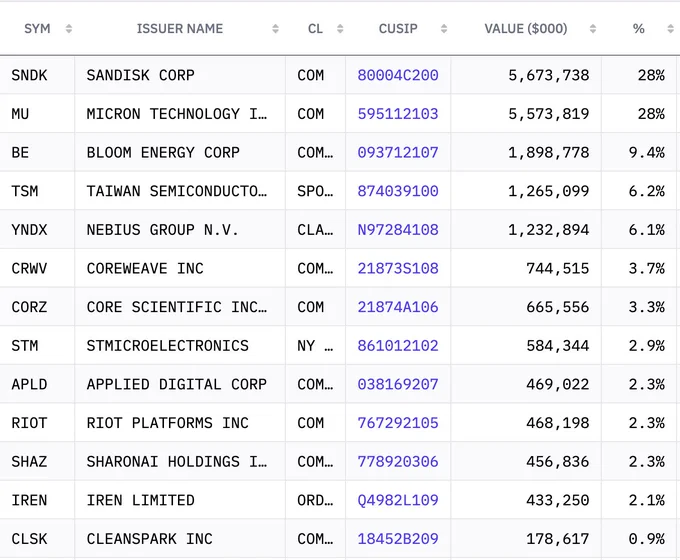
Just taking a look at Leopold's Situational Awareness Q2 13F latest holdings as of June 30th:
1. $SNDK - $5.674B
2. $MU - $5.574B
3. $BE - $1.899B
4. $TSM - $1.265B
5. $NBIS - $1.232B
6. $CRWV - $744.5M
7. $CORZ - $665.6M
8. $STM - $584.3M (new)
9. $APLD - $469.0M
10. $RIOT - $468.2M
11. $SHAZ - $456.8M
12. $IREN - $433.3M
Less material positions includeed $CLSK, $KEEL, sei-network:native, $WYFI, $BTDR, $TE, $HIVE, $VSH, and others.
Seems like Situational Awareness concentrated around memory (Sandisk, Micron), that have low forward multiples but high visibility into 2030.
As well as Anthropic/energy/power adjacent from colo/neoclouds + Bloom.
Some of the bottlenecks like the MLCC trade, he couldn't see play out (Taiyo Yuden, etc). due to July's liqudation. And some are new like $STM (eg. MCU price hikes).
With core winners of everything such as $TSM (but less high-beta).
This looked similar to my H2 2026/early 2027 portfolio with Nebius, Micron, TSM, colo players and others as core focus. (I've heavily concentrated on upstream networking/legacy memory currently, with a lot of name overlap).
But always cool to see what others are doing.
$SNDK$MU$BE$TSM$NBIS$CRWV$CORZ$STM$APLD$RIOT$SHAZ$IREN$CLSK$KEEL$SEI$WYFI$BTDR$TE$HIVE$VSH
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $APLDlong |
+4.0% | +9.0% | — | — | -2.2% |
| $BElong |
+8.4% | +23.9% | — | — | +27.5% |
| $BTDRlong |
+10.9% | +14.8% | — | — | -2.3% |
| $CLSKlong |
+11.0% | +17.2% | — | — | +13.6% |
| $CORZlong |
+6.5% | +7.6% | — | — | -4.9% |
| $CRWVlong |
+4.5% | +17.3% | — | — | +7.6% |
| $HIVElong |
+12.1% | +14.0% | — | — | +8.3% |
| $IRENlong |
+5.2% | +14.6% | — | — | +3.2% |
| $KEELlong |
+7.7% | +19.3% | — | — | +13.7% |
| $MUlong |
+0.2% | +7.5% | — | — | +11.8% |
| $NBISlong |
+3.2% | +17.8% | — | — | +15.6% |
| $RIOTlong |
+13.4% | +18.4% | — | — | +8.1% |
| $SEIlong |
+0.5% | -3.5% | — | — | +48.9% |
| $SHAZlong |
+1.3% | +4.5% | — | — | +0.8% |
| $SNDKlong |
+0.1% | +13.6% | — | — | +12.0% |
| $STMlong |
+1.1% | +1.7% | — | — | +5.4% |
| $TElong |
+6.3% | +15.0% | — | — | -9.6% |
| $TSMlong |
+0.4% | +4.8% | — | — | +10.0% |
| $VSHlong |
-0.5% | +3.5% | — | — | +6.7% |
| $WYFIlong |
+8.5% | +11.6% | — | — | +4.1% |
@balllvest With how the trends are going with $MRVL and Mediatek. My guess is Alchip (disclosure, I own this) or $QCOM might be next.
I think the ASIC pie gets bigger for all of them though.
$MRVL$2454$3661$QCOM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MRVLlong |
-0.6% | +5.6% | +24.8% | — | +24.8% |
| $QCOMlong |
-2.3% | -0.5% | +8.5% | — | +8.5% |
| $2454long |
| | | | |
| $3661long |
| | | | |
$TSM Vice President of Advanced Packaging:
"Foundries can scale up the optical engine, but the real bottlenecks to large scale deployment lie elsewhere...
Including lasers, optical fiber, fiber-optic connectors, and test" (UDN)
Just some bucket ideas:
Lasers: $LITE, $SIVE, $COHR, LandMark (3081), LuxNet, Sumitomo, Furukawa
Optical fiber / FAU: Foci, Browave, $GLW, Sumitomo
Fiber Optic / CPO Connectors: BizLink, $GLW , Fujikura, Nextronics, COXOC
CPO testing: MPI (6223), Advantest, $FORM, Msscorps, $KEYS, Chroma
(disclosure: exposure to theme above, individual names not named by TSMC)
There are others I like as well, such as ShunSin, which now has explicit TSMC COUPE exposure but probably belongs under a different category like packaging/integration.
eg. "Foxconn unit ShunSin confirms TSMC COUPE partnership"
I don't think there's anything too new vs. H1, aside from ongoing news (eg. FAU looks like there will have a demand imbalance in 2027, from a report last week).
But it's helpful to reiterate overall beneficiaries from time to time...
$TSM$LITE$SIVE$COHR$GLW$FORM$KEYS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $COHRlong |
-2.1% | +1.5% | +3.6% | — | +3.6% |
| $FORMlong |
-5.2% | +3.3% | +48.5% | — | +48.5% |
| $GLWlong |
-2.1% | +3.7% | +3.4% | — | +3.4% |
| $KEYSlong |
-1.1% | +1.4% | +12.8% | — | +12.8% |
| $LITElong |
-5.0% | -3.7% | +6.1% | — | +6.1% |
| $TSMlong |
-0.3% | +3.3% | +10.1% | — | +10.1% |
| $SIVElong |
| | | | |
Just some random ideas from Elon’s post:
$AAON - Chillers / liquid cooling
$NVT - Cooling
$MOD - Chillers / Cooling
$IESC - Wiring
$MTRS - chillers
$JCI - chillers
$HPS.A - Transformers (disclosure I own positions in this)
$PRY.MI - networking/wiring(fiber)
$CRDO / $AAOI (same) / $LITE / $COHR - networking
Since Elon Musk cited:
- transformers
- wiring
- liquid cooling
- massive chillers + complex networking
As the point of failure for AI compute buildout.
Which is “harder than finding power”
↗ Quoting @elonmusk
$AAON$NVT$MOD$IESC$MTRS$JCI$HPS.A$PRY.MI$CRDO$AAOI$LITE$COHR
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+1.4% | -0.7% | -4.5% | — | -6.6% |
| $AAONlong |
+0.1% | +4.8% | +17.6% | — | +9.2% |
| $COHRlong |
-0.5% | +1.0% | +6.0% | — | +3.1% |
| $CRDOlong |
-2.8% | -26.7% | -9.4% | — | -16.3% |
| $IESClong |
-2.2% | +4.1% | +4.6% | — | +3.7% |
| $JCIlong |
-1.0% | +3.8% | +7.9% | — | +6.8% |
| $LITElong |
+2.2% | -1.5% | +5.2% | — | +8.4% |
| $MODlong |
+0.5% | +9.6% | +11.5% | — | +5.4% |
| $NVTlong |
+1.5% | +5.1% | +10.7% | — | +8.0% |
| $HPS.Along |
| | | | |
| $MTRSlong |
| | | | |
| $PRY.MIlong |
| | | | |
I wanted exposure to DDR2/DDR3 bottleneck ongoing and found ESMT (3006).
A $2.5B MC fabless company with PSMC wafer allocation (esp. focused on DDR2).
Last month's net income was: $109.5M (July month), which annualized is $1.31B net profit (1.9x runrate P/E).
If we look at net profit throughout the months tracking legacy DRAM price hikes:
Jan 2026: ~$16M (est)
Feb 2026: ~$17M
Mar 2026: ~$31M (est)
April 2026: ~$58M
May 2026: ~$60M (est)
June 2026: ~$67M (est)
Jul 2026: ~$110M
(Estimated months are inferred from reported quarterly totals. July is company reported)
This earnings progression reminds me of $SNDK style price hikes + earnings inflection (esp. the report released this month).
And I do expect DDR2/DDR3 capacity to remain constrained throughout 2027 (with legacy players like Winbond withdrawing from certain lines too like DDR2).
It's not quite all inventory liquidation like the other peers. Sure lower cost inventory helped, but the primary driver seems to be the widening spread between wafer costs/supply and legacy dram ASPs?
Their balance sheet is extremely solid as well:
- Cash on hand: ~$395.9M net cash
- $249.6M inventory, $146.3M receivables
And the net income progression... is before further legacy DRAM hikes expected in Q3.
*disclosure own positions, NFA
It's always a bit daunting being early without much commentary around the idea. Wondering if anyone can stress test this thesis?
Since a company that grew monthly net income from $16M -> $100m this year alone (July Annualized would be 1.9x P/E).
And benefits from another projected wave of DDR2/DDR3 hikes this quarter... maybe like 35-40% for DDR2 lines per Trendforce, and DDR3 likely continuing to rise.
Do markets just not know about this bottleneck/company or am I missing something from my research?
$ESMT$SNDK
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $SNDKlong |
-1.0% | +3.6% | +18.6% | — | +16.0% |
| $ESMTlong |
— | — | — | — | — |
Walsin (2494) is top 4 in the world in terms of overall MLCC marketshare (I actually added some recently to track how this guess plays out), with apparently less AI server related compared to Yaiyo Yuden.
~$4.5B MC relative to Yageo, so relatively higher exposure if MLCC supply imbalance broadens.
There's primary Walsin document they state "10% global MLCC share" / "4th or 5th globally"
$2494$2327$6976
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $2327long |
| | | | |
| $2494long |
| | | | |
| $6976long |
| | | | |
$SMCI 2027 guidance was actually unholy: $65-$72 billion FY 2027 revenue guidance...
vs. ~$52.4B expected, a casual +$16.1B above consensus.
SMCI logged a massive $60B+ in news order from this earnings.
That timeline is also interesting when they announced a plan to co-build $SPCX + xAI DCs "within a year" back in June..
But if SMCI sustain 10-15% gross margins off that ~$70B revenue guidance... I think there's a lot of room for rerating given MC is ~$20B (NFA, I have short term positions in SMCI now from this ER).
Most important thing is learning about 2027 margins from call today.
$SMCI$SPCX
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $SMCIlong |
+19.0% | +18.4% | +18.3% | — | +29.9% |
| $SPCXlong |
+9.6% | +7.5% | +11.2% | — | +13.2% |
@babybluecream Yeah, my $EWY longs crashed quite a bit.
I still think the operating income that SK Hynix and Samsung produces will catch up to the MC eventually, so I’m holding my memory positions.
Regardless, not a fun time to watch Asian markets from Nikkei to Taiwan to Kospi drop so much.
$EWY$SSNLF$HXSCL$N225$KOSPI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $EWYlong |
+0.2% | +0.3% | +10.6% | — | +12.5% |
| $HXSCLlong |
| | | | |
| $KOSPIlong |
| | | | |
| $N225long |
| | | | |
| $SSNLFlong |
— | — | — | — | — |
Came across an interesting report from SVRC Research called "State of Robotics 2026", published in April.
Which listed:
1. Figure AI
2. Agility Robotics $CCXI
3. Apptronik
4. $TSLA
5. Boston Dynamics
6. Physical Intelligence
7. 1X Technologies
8. $AMZN Robotics
9. Covariant
10. Skild AI
As the National Champions of the United States robotics program.
"The United States leads the world in where robotics is heading: Fundation models, OpenAI-style scaling laws applied to action, autonomous vehicles.
While losing the race on where robotics is shipping today."
Then it frames:
1. Rare Earths Exposure: from Neodymium for motors to samarium-cobalt for high-temp applications as a critical vulnerability.
2. Actuator dependency. Series elastic actuators, quasi-direct-drive motors, and precision reducers overwhelmingly sourced from Japan, Germany, and China
As one of the main vulnerabilities alongside Manufacturing velocity/data collection cost/regulations. Then their take was:
"With at least six well-funded US humanoid companies competing for a market still in early formation, we expect at least two significant consolidation events (acquisition or merger) in 2027".
With Logistics / E-commerce (like $AMZN / $FDX) and Automotive from $GM to $FORD as being the immediate top use cases for deployment.
I think it's just interesting to see a lot of my points I've been talking about reiterated by research firms. Regardless, I do think it's going to be a major frontier race between the US and China.
Agility Robotics (which I own), Tesla, Figure, and Apptronik as leaders representing the USA. Competing against Unitree, AGIbot, Ubtech, and others in China.
$TSLA$AMZN$FDX$GM$F$CCXI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMZNlong |
+0.6% | +1.8% | +11.9% | — | +2.7% |
| $CCXIlong |
-9.8% | -15.0% | -27.4% | — | -39.3% |
| $Flong |
+3.5% | +1.9% | +9.9% | — | -8.8% |
| $FDXlong |
-1.0% | -0.7% | -1.8% | — | -8.6% |
| $GMlong |
+2.4% | +0.9% | +16.9% | — | +1.5% |
| $TSLAlong |
+6.7% | +3.3% | -20.9% | — | -9.9% |
So positive readthrough on the upstream glass substrate supply chain:
- Sumitomo Chemical and Samsung Electro-Mechanics formally establish JV in Korea within the year to handle the glass core substrate business (GlaSSEM).
Main thing was timeline/funding was finalized: "full scale commercialization targeted H2 2027" for the Samsung/Dongwoo JV / KRW 482.1B planned capital.
Think the "full scale commercialization" is the word to highlight, since that would imply timeline moving faster than expected than starting ramp or early production H2 2027.
So... TGV/LIDE with $LPK (that I own)/E&R and Onto in terms of yields are just some examples of possible sector beneficiaries.
Since companies like LPK stated in the past: “80% of customers among major global players have selected LPKF equipment” and targeted "70% of LIDE market share target for TGV in the glass-core ramp".
These players also typically have revenue pulled forward, since equipment orders during capex cycle hit before actual ramp.
Regardless, just an update on developments.
$LPK$ONTO
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $ONTOlong |
-1.2% | +3.1% | -15.9% | — | +0.1% |
| $LPKlong |
| | | | |
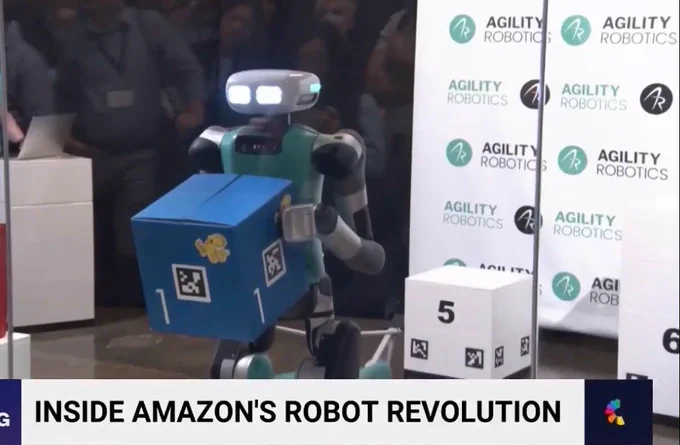
Yep! Agility Robotics is currently my favorite humanoid/robotics position.
They're set to be listed on NASDAQ via $CCXI as early as September (per Digitimes).
Just for informational purposes: Their V4 humanoid robot is already operating in sites like Amazon. And have V5 slated for mass production next year (they have a 10,000+ /year capacity).
Investors include Foxconn, $NVDA, $AMZN, Softbank, and now Serenity.
I've been personally waiting for humanoid exposure for awhile (Agility is set to be the first US pure-play listed one) to the point I was actually planning on investing in Unitree's IPO.
But I'm glad now I personally have a compelling alternative now since I prefer to invest capital to build up Made in America supply chains (75% of their components are US-sourced from investor desks).
There are risks assigned to SPACs such as listing delays, or cancellation. But excited to see what happens next with developments.
I do hope this encourages other frontier companies to go public early on.
↗ Quoting @suoha_ai
$CCXI$NVDA$AMZN
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMZNlong |
+1.4% | +3.2% | -1.2% | — | +4.5% |
| $CCXIlong |
-2.2% | -9.1% | -19.8% | — | -33.5% |
| $NVDAlong |
-1.3% | -1.6% | -2.5% | — | +14.3% |
For robotics companies, I have a favorable view on Unitree and Agility Robotics, two humanoid players.
And I have largest concentration in Agility Robotics, since I personally prefer US humanoid players.
For upstream component exposure, I currently own:
- Harmonic Drive (6324) given high content BOM on things like harmonic reduction gear.
- Vishay Precision for sensors and a possible candidate for Telsa Optimus.
LeaderDrive (688017) and Schaeffler I have favorable views on but don't own personally.
Many of the other AI DC players, I have indirect exposure to robotics like memory.
Don't recommend anyone to copy, just sharing personal positions/thoughts.
Humanoid sector is large, and as seen with Goldman Sachs report that "Korean companies will command a 30% direct and indirect share of global humanoid robot production".
Lot of players out there globally. This was an older report but just linking it again since you see all of them pop up in GS institutional reports + what they cover.
Agility Robotics is my personal favorite as of now.
↗ Quoting @pdrakoul
$6324$VPG$TSLA$688017$SHA$GS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $GSlong |
-0.9% | +3.4% | -3.9% | — | -11.3% |
| $TSLAlong |
+2.1% | +1.9% | -27.6% | — | -13.9% |
| $VPGlong |
+5.5% | -13.4% | -42.8% | — | -49.5% |
| $6324long |
| | | | |
| $688017long |
| | | | |
| $SHAlong |
| | | | |
OFC I'm aware. But I'm personally sleeping comfortably since I have conviction in my hyperscaler mapping research with $SIVE.
And yes, I still have my million+ share position.
Not sure if people realize this: but I'm only here to share my thoughts/ideas.
I don't control market volatility, what decisions you all make, or how markets react to new information synthesis.
It's much safer for analysts to just reactively tag along Morgan Stanley/JP Morgan/Goldman Sachs research whenever it's created and just summarize.
Rather than coming up with new ideas from OSINT mapping and waiting them get validated.
Because when you discover a new angle:
Everyone keeps heatedly debating topics of 4-6 inch InP fabs, employee count, who their hyperscaler customers are, volume ramp timelines, etc to try and play devils advocate with a thesis.
Then actively monitoring every single 5-20% price movement.
I'm forced to stay on this topic more since it's less validated + there's always heated discussions. Just like $EWY in Feb, which I did memory projections on + Helium/LNG/Oil analysis.
But months later everyone sees memory looks structural with Micron's 16+ LTAs and LNG isn't taking down SK Hynix margins.
Or $NBIS from last year in terms of sum-of-parts / dilution structures vs $IREN.
And now it's close to ATHs and listed on $QQQ.
I'm personally just waiting Sivers to volume ramp in 2027 + listing on NASDAQ to support their M&A efforts.
So they can walk down the same path as $LITE when they scaled from $3B to $60B+.
↗ Quoting @Ecom_Venture2
$SIVE$EWY$NBIS$IREN$QQQ$LITE$MU
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $EWYlong |
+0.1% | -8.7% | -17.4% | — | -7.3% |
| $IRENlong |
-2.8% | -17.8% | -21.5% | — | -13.4% |
| $LITElong |
+4.2% | -10.9% | -6.6% | — | +18.8% |
| $MUlong |
+1.1% | -13.8% | -18.7% | — | -5.6% |
| $NBISlong |
+8.7% | -10.3% | -21.9% | — | -1.8% |
| $QQQlong |
+2.5% | +0.9% | -3.2% | — | +4.8% |
| $SIVElong |
| | | | |
I actually think OE Solutions ($138080.KQ
) makes the most sense as an acquisition target by a large downstream player.
Since it’s now trading at a stupid ~$215M MC for scarce EML/CW laser IP.
A Source Photonics / Suzhou Dongshan Precision type acquisition might add a lot more value to another company that wants to vertically integrate.
Given there’s a lot of expensive R&D and capex required to scale their fabs and buildout ahead + it’s a small optical player. (Disclosure: I do own positions)
Just floating the idea out there to other companies.
↗ Quoting @nokorea_yesusa
$138080.KQ
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $138080.KQlong |
| | | | |
Wow, 3 limit ups in a row with WUS TW. Pretty sad I didn't take larger positions.
WUS TW is 1 my 2 NAV arbitrage + independent growth trades.
If you want context: WUS TW is a ~$1.12B PCB player with AI DC growth.
Their stake in WUS Kunshan is $4.79B (11.4% of 42.04 billion)
So basically they're a $1.1B PCB player growing independently, sitting on ~$4.79B worth of another company that looks to IPOed on Hong Kong markets soon.
And a successful activist investor in Palliser (with Ajinomoto and Toto), is pressuring them to trim some holdings along with a few others.
Seems like a pretty insane disconnect, and I think there's a lot of potential here.
↗ Quoting @aleabitoreddit
$WUS$2802.T$5332.T
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $2802.Tlong |
| | | | |
| $5332.Tlong |
| | | | |
| $WUSlong |
| | | | |
I've been getting a lot of questions about OE Solutions (138080) recently.
Here's my research/thoughts so far on it:
They're a small Korean optical transceiver company, similar to $AAOI.
And they've become one the few EML players in the world (eg. $COHR, $LITE, Mitsubishi, Source, Sumitomo), with scarce 100G EML laser capacity for 800G/1.6T.
OE appears to be trying to make the full transceiver, not just the EML. They also have finished ELSFP CPO products, with UHP CW lasers, which is sampling Q3.
Likewise, OE also seems to be building out the full ELSFP, rather than selling CW laser dies, so that's more market share.
So you can think of it as Korean AAOI but EML instead of CW, and less capacity/qualifications. And playing catch-up to the rest of the world.
However in terms of timelines:
1. 23dBm cooled ELSFP samples start in Q3 2026
2. Sales base for 800G, and 2027 1.6T "full force"
3. Late H2 2027, H1 2028 onward probably their ELSFP enters the volume production.
And it seems they're working on 200G EML capability from their investor snipper 2025 OE IR snippet referenced “100GBaud EML / 200G PAM". This seems promising given their IP/demos.
ELS has just been unveiled recently, sampling starts Q3. 800G/1.6T Optical transceivers are also likely 2027.
So this is basically Korea's sovereign photonics player, playing catchup to $LITE, $AAOI, and the bigger players.
(Disclosure: I have positions in OE Solutions (138080). This is fundamental research for informational purposes, not financial advice).
As for OE solution valuations:
1. Doesn't seem like there's confirmed customers yet for these growth verticals.
2. Probably not many people understood what they're building toward yet.
3. Yields data kinda uncertain
1. Customers: We're actually in a major EML/CW laser shortage, so any independent capacity will be sought after. I personally don't think they'll have a hard time finding customers here. I would assume anything they make might get bought out and would get extra support from Korea.
2. Institutional support: Probably not much since it doesn't meet threshold for many US institution given MC size + KR listing. I also don't think many people understood what they're building yet.
3. Yields/Capacity: OE's disclosed wafer/module utilization is low (i remember was around 31% underutilized off the top of my head), so there's enough material revenue they can generate before they need to spend on capex.
I'm also not sure about EML/CW and other yields. Probably need to go ask the company.
Is this some random crap co? No. It's been doing optical transceivers stuff for more than 20Y, has R&D in the U.S. and Netherlands.
But their entire AI growth vertical seems to happen next year, and hinges mainly around capacity/yields.
And I personally think the EML/CW tech is probably worth a lot more than their current MC, if it were an acquisition target.
Especially from a larger player that wanted to vertically integrate EML for pluggables and CW lasers for CPO.
Markets are probably waiting on more certainty around qualifications after Q3 sampling or earnings projections announcements.
TLDR on thoughts:
Some of my friends discussed this last year, was probably way too early. Saw it got many comments 2 months ago, still too early.
I still think now is early, but later in Q3-Q4 might be more interesting. I personally think it's a lot higher risk than a major CPO player like $SIVE, that's embedded in Ayar, $JBL, $GFS, and many other hyperscaler suppliers. Which also has Win Semi and others de-risking volume ramp.
As OE Solutions looks like a new player trying to build out an $AAOI for the optical transceivers but sovereign EML and CW laser production for CPO products.
And there's a lot of answered questions around customers + volume ramp, which presents material risk.
But if you believe Korea can build out an 800G/1.6T transceiver EML supply chain and ELSFP with CW lasers.
With OE Solutions, it might be worth taking a look into. Still researching the company tho, just initial thoughts.
↗ Quoting @unintellignt
$AAOI$COHR$LITE$SIVE$JBL$GFS$138080
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+5.8% | -14.4% | -36.7% | — | -38.7% |
| $COHRlong |
+9.2% | +4.5% | -28.7% | — | -26.1% |
| $GFSlong |
+4.5% | +0.5% | -32.9% | — | -43.9% |
| $JBLlong |
+1.4% | +0.7% | -19.1% | — | -22.8% |
| $LITElong |
+5.2% | +1.4% | -13.8% | — | +14.2% |
| $138080long |
| | | | |
| $SIVElong |
| | | | |
In terms of personal notes:
1. Priortech owns 21% of $CAMT, ~1.35x their MC, seems more like holding co.
2. Bit Digital people kept shouting, but NAV discount is not clean $WYFI, lot of dilution + not AI parent.
3. Wistron (3231) is the best one I've seen since $SIVE + Ayar + Wiwynn are one of my favorite trio.
~$16.2B MC, Q1 revenue up a ridiculous amount with 144% Y/Y growth.
Owns 35.46% of Wiwynn, which is ~0.66x of MC. I'd expect Wiwynn to keep on growing.
4. Sin-American Silicon 5483 does own 46.64% of GlobalWafers (6488).
MC is $3.5B, stake value is ~$7.9B, but not exactly growing too fast independently, though it's heavily trading heavily discount to NAV.
5. Iljin Holdings owns 42.99% of Iljin Electric, it's ~$0.22B MC vs. ~$1.13B NAV holding. This was transformer/cable DC related.
But again idk if I trust korean stocks for NAV unlock, probably better for activist investors.
6. Simmtech Holdings was ~$0.17B MC vs. ~$1.0B of parent, which also looks ridiculous.
So 6x+ NAV. PCB substrate related name. Also another prob don't trust korean governance type name.
I think both $ACMR and WUS have H-Share subsidiary listing soon, and those were the biggest NAV discounts with independent growth.
Then you have a highly successful activist going after WUS so I'd expect some middle ground there.
So maybe I'll put more concentration into those on top of what I already own Monday, we'll see. And Wistron was growing very fast independently.
I'm still doing research, normally this goes in shower thoughts since I haven't formally made a conclusion, but thought others might be interested.
↗ Quoting @pingguo2023
$CAMT$WYFI$SIVE$ACMR$BTBT$3231$5483$6488$WUS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $ACMRlong |
-6.1% | -2.7% | -23.6% | — | -26.3% |
| $BTBTlong |
+2.8% | -11.1% | -35.5% | — | -24.9% |
| $CAMTlong |
+0.3% | -13.9% | -25.1% | — | -20.6% |
| $WYFIlong |
+16.3% | -4.3% | -34.7% | — | -53.2% |
| $3231long |
| | | | |
| $5483long |
| | | | |
| $6488long |
| | | | |
| $SIVElong |
| | | | |
| $WUSlong |
| | | | |
I think something to highlight also is not all my ideas are green, especially on short term timeframes!
My core three themes are Neoclouds (Energy), Memory, and Photonics.
And I'm glad I chose the literal top performers for each segment from $NBIS to $EWY leaps to $SIVE.
However, I still have pretty large losses following the false analyst report on CPO delays that $NVDA refuted:
That nuked 3 of my TW CPO longs from Foci, Msscorp, Xintec and others. (which are heavily red). Shunsin / Win Semi are holding up much better though.
Some of the other ones in Japan that I've mentioned like Towa, Harmonic Drive, NCI, etc. are performing much better following short-term volatility.
As for Korea yes I have PTSD for from Auros and now Foosung that are both both red (I didn't own 093370 though, just got PTSD watching price action).
Idk if I'll touch Korea again, just way too volatile. But I still think those will end up green eventually following Sk hynix/samsung qualifications + HVM, and the future japanese supply chain shutdown.
I also did change some of my previous long ideas like $XLU following the Iran War nuking all chances of rate cuts from 3-4 down to 0, and that didn't play out too well. Three software names I mentioned previously like $TTD, $META ended up red. $SNAP, I also changed my thesis after noticing the endless SBC accounting methods. $RDDT idea was finally in the green from $130 -> $170 after a long time.
But I think the vast majority of my ideas like $MRVL, $NBIS, $ARM, $INTC, $MU, $LITE, SK Hynix, Samsung, for larger cap.
Down to $AXTI, $LITE, $AAOI, $RPI, $IQE, and others for smaller cap positions directionally play out pretty well.
With random stuff like $SIMO, $HPS.A, $TSEM, $AEHR, $LPK, $SOI, $ALRIB, and so on all ended up turning out aight too.
The blended average is kinda overwhelmingly green since majority of my long ideas are triple digit YTD.
But I've definitely missed a few.
Also entry point is really important too... I mentioned $AAOI at $30 or $AXTI at ~$13, but not everyone has the same entry point. So if someone bought AOI at $220 and it dropped to $160, I'd feel bad.
But regardless, I'd prefer to judge how ideas play out on medium term timeframes over a few months rather than a few weeks.
↗ Quoting @insyyte
$NBIS$EWY$SIVE$NVDA$XLU$TTD$META$SNAP$RDDT$MRVL$ARM$INTC$MU$LITE$AXTI$AAOI$RPI$IQE$SIMO$HPS.A$TSEM$AEHR$LPK$SOI$ALRIB
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+5.8% | -14.4% | -36.7% | — | -38.7% |
| $AEHRlong |
-1.7% | -14.3% | -29.7% | — | -13.6% |
| $ARMlong |
-7.2% | -20.9% | -39.2% | — | -34.1% |
| $AXTIlong |
+9.3% | -18.3% | -45.8% | — | -8.5% |
| $EWYlong |
-0.1% | -6.5% | -25.8% | — | -16.6% |
| $INTClong |
+5.2% | -0.8% | -29.1% | — | -10.3% |
| $LITElong |
+5.2% | +1.4% | -13.8% | — | +14.2% |
| $METAlong |
-2.1% | -7.9% | +41.8% | — | +81.7% |
| $MRVLlong |
-0.9% | -9.4% | -39.2% | — | -14.9% |
| $MUlong |
+6.8% | +7.0% | -25.1% | — | -5.7% |
| $NBISlong |
-1.1% | -10.5% | -38.0% | — | -17.7% |
| $NVDAlong |
-1.0% | -7.1% | -3.7% | — | +8.5% |
| $RDDTlong |
-2.6% | -9.7% | +3.6% | — | -18.6% |
| $SIMOlong |
+4.7% | +1.1% | -17.8% | — | -12.8% |
| $SNAPlong |
-0.6% | -6.9% | -2.8% | — | +15.9% |
| $TSEMlong |
+10.5% | -5.9% | -18.4% | — | -20.7% |
| $TTDlong |
-2.6% | -6.4% | +0.4% | — | -34.3% |
| $XLUlong |
+0.5% | +3.1% | +1.6% | — | -10.7% |
| $ALRIBlong |
| | | | |
| $HPS.Along |
| | | | |
| $IQElong |
| | | | |
| $LPKlong |
| | | | |
| $RPIlong |
| | | | |
| $SIVElong |
| | | | |
| $SOIlong |
| | | | |
Anyone got a list or ideas of the biggest NAV discounts. But independently has AI growth?
Stuff more extreme end like $ACMR and WUS (2316) compared to SK Square.
Have exposure to the ones above, just wanted to research more opportunities.
Seems to be getting noticed recently
$ACMR
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $ACMRlong |
-6.1% | -2.7% | -23.6% | — | -26.3% |
$ALRIB general meeting notes came out today.
-2nd ROSIE System expected to be delivered shortly to a leading quantum computing player” in the US.
- They’re also intensifying BD for their products used for BTO/STO on photonics and recorded strong interest.
Just for background, they’re the MBE duopoly with Veeco, which got re-rated heavily recently (Disclosure own Riber), with exposure to Quantum.
Positive development overall.
↗ Quoting @aleabitoreddit
$ALRIB$VECO
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $VECOlong |
-2.7% | -5.3% | -34.4% | — | -35.5% |
| $ALRIBlong |
| | | | |
I agree with Palliser Capital here.
As a shareholder, it’s just so stupid how WUS (2316 TW) MC can be ~$1B MC.
While they own a 11.26% stake of WUS Kunshan, a $39.3B (¥282B CNY) company…
Which is worth $4.42B pre-tax. Just sell 1/4th or something?
And you get an extra ~$1.1B for PCB growth at the inflection point with AI demand.
Which is more than your current MC pre-tax, purely in cash.
And there’s still $3.3B in assets + markets might revalue your company because of willingness to trim locked up assets.
Nobody is asking you to trim everything, but the NAV disconnect is insanity.
WUS TW management should really reconsider.
$2316
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $2316long |
| | | | |
VPEC new price hikes on Epiwafers today.
Positive bottleneck read through on companies like $IQE and Landmark (3081) in terms of pricing power/demand for epiwafers.
This follows $MTSI investment into IQE to secure capacity, and shows how important some of these chokepoints are.
(disclosure: have positions in IQE)
↗ Quoting @QQ_Timmy
$IQE$MTSI$3081
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MTSIlong |
+1.3% | +3.0% | -18.8% | — | -25.0% |
| $3081long |
| | | | |
| $IQElong |
| | | | |