Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
@tradesidious @kkkkk61216936 I still have $CCXI, they haven't even had the listing event yet, so volatility up until then is kinda meaningless to me.
$CCXI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $CCXIlong |
+1.6% | — | — | — | -5.2% |
@kkkkk61216936 I cut my positions here
https://t.co/XJBWaBQQmQ
↗ Quoting @aleabitoreddit
$FLNC
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $FLNCshort |
-5.2% | — | — | — | -3.1% |
I’ve actually entered positions in many tiny Korean companies recently…
That actively supply memory, test, machines, etc. to $MU, $SKHY, Samsung, and others like $SMTC + US companies.
It’s pretty interesting what you find in the $30-$250m range for optical components, CPUs, memory, and others that are inflecting due to AI.
I don’t share these names publicly since risks/volatility is enormous.
But one or two going from $40M -> $400m makes the risk/reward worth it for me personally.
↗ Quoting @mikefritzell
$MU$SKHY$SMTC
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MUlong |
+0.8% | -0.3% | — | — | -0.3% |
| $SKHYlong |
-1.5% | -2.7% | — | — | -2.7% |
| $SMTClong |
+3.1% | +5.4% | — | — | +5.4% |
$SIVE and $AAOI, yes for a 2027 timeframe. That's the nuance.
Sivers you're coming on with 100M CW DFB laser capacity + 2 external foundries (maybe 300M in total), and all my supply chains mapping maps to larger hyperscaler suppliers.
AAOI you're coming on with $471m transceiver revenue + 400K ELS units for 2028 timeframe. With hyperscalers + demand eating up all their capacity. There's just a $600m ATM which presents overhang near term.
$NBIS already got re-rated but it's very positive upcoming for Q4 2026 (esp. with price hikes).
Legacy memory like $ESMT + (some I haven't named yet) + regular memory names like Samsung, I do think will strongly outperform near term. And obviously CPUs names like $INTC $AMD $ARM as of recent.
$SIVE$AAOI$NBIS$ESMT$INTC$AMD$ARM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-1.5% | -10.9% | — | — | -8.7% |
| $AMDlong |
+1.3% | -1.2% | — | — | -0.6% |
| $ARMlong |
+3.2% | -12.3% | — | — | -10.3% |
| $INTClong |
+1.7% | -4.7% | — | — | -1.3% |
| $NBISlong |
+1.4% | -0.4% | — | — | +1.3% |
| $ESMTlong |
— | — | — | — | — |
| $SIVElong |
| | | | |
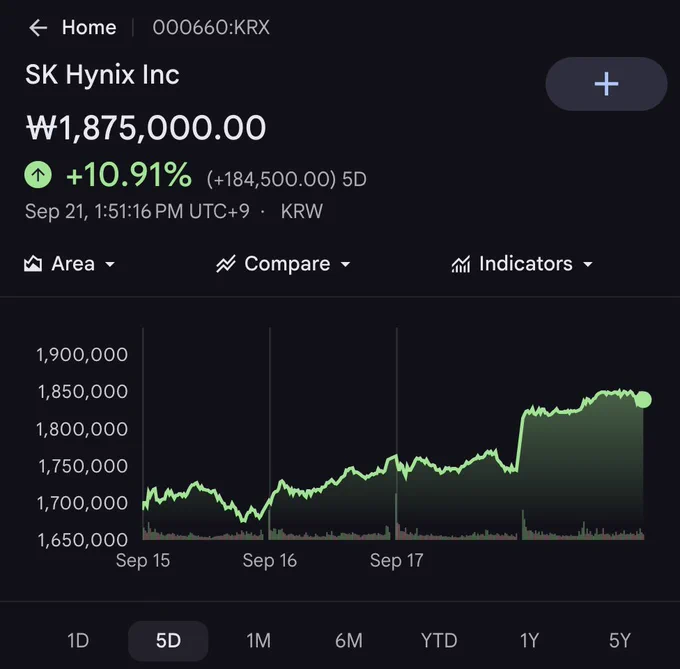
The main duo $SKHY and Samsung are having a fun day.
I'm still long memory (eg. $EWY / $DRAM ) since if capacity agreements extend 3-5 years... and your analysts model 2.8-3.3x 2027E. Risk/reward is attractive over time.
But I think legacy memory a very interesting trade currently due to ASP hike potential..
It also just so happens these same companies procure memory from even smaller memory companies (that might have higher sensitivity)...
So if you want to, you can track $PSMC wafer allocations, and find some interesting companies that likely replace $MU discontinued legacy memory through Alliance or supply directly to Samsung.
Won't mention them on X, but just throwing out some research ideas.
$SKHY$EWY$DRAM$PSMC$MU$SSNLF
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $DRAMlong |
+3.3% | -3.1% | — | — | -2.2% |
| $EWYlong |
+1.8% | -2.9% | — | — | -3.4% |
| $MUlong |
+5.0% | +1.0% | — | — | +2.4% |
| $SKHYlong |
+3.4% | -3.7% | — | — | -2.5% |
| $PSMClong |
| | | | |
| $SSNLFlong |
— | — | — | — | — |
@Retardlnvestor I now own 2 whole shares of $IREN
$IREN
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $IRENlong |
-3.7% | +9.4% | — | — | -5.3% |
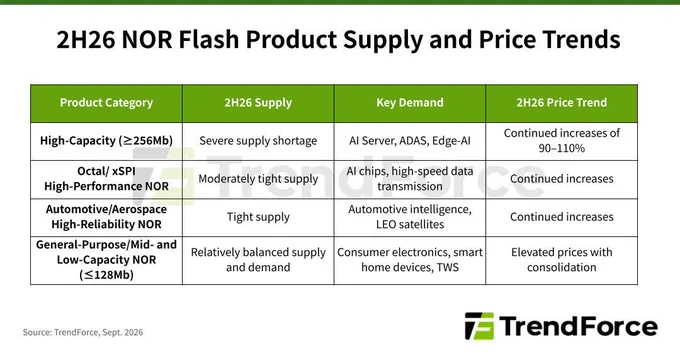
NOR flash “Severe Supply Shortage” with high density continued increases of 90-110% for H2.
I wonder who sells both high density NOR and SLC NAND? *cough cough, $ESMT*
For H1 hikes:
NOR: +100–120%
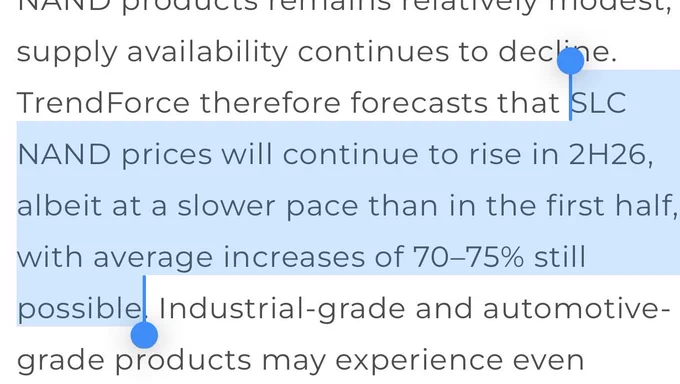
SLC NAND: +130–150%
For H2 hikes:
High-density NOR: 90-110% in H2
SLC NAND: ~70–75%.
Obviously there’s others from Winbond / Macronix / Gigadevice, but my idea and position with ESMT is that it’s the largest beneficiary of the shortage relative to size. (they sell NOR: >256Mb)
The moderate bearish part is:
“For mid- and low-capacity products of 128Mb and below, additional capacity from Chinese suppliers is gradually coming online.
Price increases for consumer-grade products are therefore expected to moderate”
However, this update is overwhelmingly bullish for earnings of legacy memory players.
Let the ASP hike games continue.
$ESMT
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $ESMTlong |
— | — | — | — | — |
Of course! All it takes is a surprise announcement like “Sivers powers Innolight” like they did with $JBL or $GFS.
Since we narrowed down the pluggable players working with Sivers to China as a geography from channel checks + potentially larger scale.
Could be anytime or never, who knows.
$SIVE$JBL$GFS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $GFSlong |
-7.3% | +1.9% | — | — | +2.3% |
| $JBLlong |
-6.1% | -5.8% | — | — | -9.8% |
| $SIVElong |
| | | | |
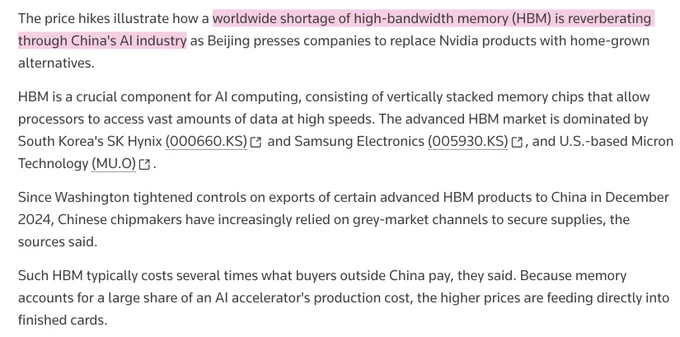
Wow, HBM reportedly drove up AI accelerator/card prices by 20-50% in China.
So $SKHY, Samsung, $MU, should be happy to hear this:
- Huawei has raised indicated pricing for the Ascend 950DT 20–50% above quotes from just 2 months ago
- Cambricon's upcoming 690 is reportedly +20–30%
Reuters stated that HBM acquired through grey market channels in China can cost several times regular pricing.
As someone who is long memory, I'm happy about memory causing this much inflation.
$SKHY$MU$SSNLF
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MUlong |
-0.2% | +0.0% | — | — | +9.4% |
| $SKHYlong |
+0.9% | -2.8% | — | — | -2.2% |
| $SSNLFlong |
— | — | — | — | — |
Okay I know this is US time and this is a Taiwan stock...
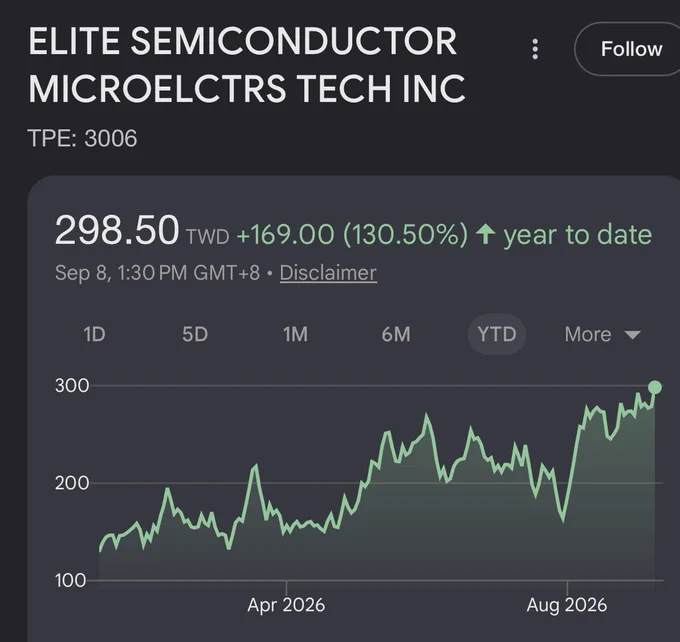
But I really am starting to think $ESMT (3006) can cook like $SNDK. And I’m excited.
So hopefully in a few months, people can something say similar...
FUN FACT CHAT:
Did you know.. 1 old DDR2 memory chip is.. ~$0.96? (from LCSC data)
Obviously different per spec since some can be $2.5...
But if you 3x ASP Hike this.
That's a whole... ~$2 added to final BOM cost.
So about the same cost as a $COST hot dog.
It goes into things like a D-Link security camera, maybe like $33 final cost...
and adds like $2. (which people won't mind)
But... 3X ASP hike to ESMT? Is very, very material.
That's just for one product category, and there's many others from SLC NAND (eg. +120–170% H2) to NOR Flash products for H2 ASP hike projections.
And my favorite thing is, they've already shown they're willing to partake in the price hike games (seems like there's a long way to go)…
Currently they make ~$111M net income a month from July earnings ($2.8B MC), which annualized is like ~2.1X P/E. *I have positions.
So... I think $ESMT has room to cook like masterchef Sandisk.
TLDR:
- Repeated rounds of price hiking = seems absurd for the company's net income... but has potential due to starting low component cost.
- Reminds me of early $SNDK but for other segments (legacy/niche memory).
↗ Quoting @yukimamax
$ESMT$SNDK$COST
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $COSTlong |
-0.8% | -1.0% | — | — | +0.0% |
| $SNDKlong |
+1.5% | -11.9% | — | — | +0.1% |
| $ESMTlong |
— | — | — | — | — |
@OInvests My 1 $IREN share is also cooking today.
$IREN
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $IRENlong |
-3.3% | -11.4% | — | — | -12.9% |
 @aleabitoreddit
Sep 08, 2026 · 03:56 ET
stock
1st mention
trade
position
📈 market call
So $INTC is raising PC CPU prices by 10% apparently in October per Digitimes, which I think markets might appreciate.
The legacy memory trade also just going brrr from August revenues:
-> ESMT revenue up ~+605% Y/Y, 16.4% M/M
Which is interesting given gross margins also rising tremendously too.
-> Etron revenue up +525% Y/Y, +6.4% M/M
Chairman says he sees growth momentum in memory to extend through 2028 or longer, potentially 2030. (which is very positive read through for ESMT given what Etron sells) *own ESMT/Etron
-> Winbond revenue up +289.43% Y/Y, up 2% M/M
Their president says memory supply and demand are expected to be even tighter in 2027 than in 2026.
-> Macronix revenue up +218.5% Y/Y, +5.4% M/M
Says SLC NAND, eMMC, NOR remain tight (kinda known there).
So... if you think your 80%-100% type revenue growth players are insane.
Check out legacy memory (operating income is even more hilarious). There's a few more where ~ modeled forward P/E values of like 2-3 from my estimates.
I personally find the theme a better value investing type idea than your 16 P/E no-growth dividend companies.
$INTC$ESMT$ETRON$WINBOND$MACRONIX
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $INTClong |
+1.7% | -7.0% | — | — | +15.1% |
| $ESMTlong |
— | — | — | — | — |
| $ETRONlong |
| | | | |
| $MACRONIXlong |
| | | | |
| $WINBONDlong |
| | | | |
I get like 100 of these types of questions a day, I can’t just answer all of them.
Since you’ve asked 12 times: yes I still have exposure to all of them.
Cost averaged on a few, so as of today positions on:
Foci are up 53%
Xintec are up 53.1%
But still down -23% on Shunsin, -22% on Msscorp.
Main position I trimmed the most at a loss for tax harvesting was Auros after hybrid bonding industry delays.
I like to post thesis ideas, but try to keep portfolio management stuff private like tax loss harvesting or trimming.
I’ll post thesis research updates, like $TSM coupe confirming partnership with Shunsin. Or FAU bottleneck validation on Foci. Or hybrid bonding delays.
But in the end people should make their own decisions
$TSM$FOCI$XINTEC$SHUNSIN$MSSCORP$AUROS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $TSMlong |
+2.4% | +1.0% | — | — | +6.6% |
| $AUROSshort |
| | | | |
| $FOCIlong |
| | | | |
| $MSSCORPlong |
| | | | |
| $SHUNSINlong |
| | | | |
| $XINTEClong |
| | | | |
I asked OpenAI Astra Ultra + Anthropic Fable 5.1 Max to make me a 5x-10x return type portfolio in 1 year.
Burnt a lot of credits, and the results are in:
OpenAI: - $KYTX (autoimmune CAR-T results)
- $PRQR (human RNA-editing datasets)
- $VSTM (KRAS cancer-drug)
- $CNTB (asthma and COPD)
- $RANI (oral biologics)
- $IVA (MASH)
- $SILC (networking + inference hardware)
- $AMPX (batteries)
- $EOSE (batteries)
- $ZVRA (rare-disease drug growth)
Anthropic: - $INO (respiratory papillomatosis)
- $CAPR (PDUFA for deramiocel)
- $GOSS (seralutinib)
- $SLS (Phase 3 binary)
- $IREN (familiar face)
- $WULF (familiar face)
- $OKLO (nuclear)
- $SMR (nuclear)
- $RGTI (quantum)
- $QBTS (quantum)
*Disclosure don't own any of these aside from 1 share in IREN, not a recommendation, just TLDR of LLM output for educational purposes.
So very interesting results:
Our beloved AGI Astra prefers really obscure biotech I've never heard about. And a few familiar names like $EOSE and $AMPX.
And Fable... yeah idk, feels like it learned a little too much from /r/wallstreetbets and X but maybe it's right, who knows.
Anyway no judgement, I'll save this and revisit it in a few months. If one of them actually delivers... I'll be impressed.
↗ Quoting @aleabitoreddit
$KYTX$PRQR$VSTM$CNTB$RANI$IVA$SILC$AMPX$EOSE$ZVRA$INO$CAPR$GOSS$SLS$IREN$WULF$OKLO$SMR$RGTI$QBTS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMPXlong |
+5.1% | -4.6% | — | — | -2.1% |
| $CAPRlong |
-3.6% | -11.0% | — | — | +0.7% |
| $CNTBlong |
+3.8% | +10.9% | — | — | -40.2% |
| $EOSElong |
+10.8% | +1.8% | — | — | -21.0% |
| $GOSSlong |
+2.6% | -23.5% | — | — | -14.2% |
| $INOlong |
-0.7% | -12.6% | — | — | -14.0% |
| $IRENlong |
+5.0% | -1.9% | — | — | -8.5% |
| $IVAlong |
-2.3% | -15.9% | — | — | -31.2% |
| $KYTXlong |
-2.2% | -12.0% | — | — | -17.5% |
| $OKLOlong |
+4.9% | -12.2% | — | — | -10.3% |
| $PRQRlong |
-1.0% | -10.1% | — | — | -20.3% |
| $QBTSlong |
+6.6% | +1.3% | — | — | -0.1% |
| $RANIlong |
+0.8% | -2.6% | — | — | -8.6% |
| $RGTIlong |
+4.0% | +0.5% | — | — | +3.5% |
| $SILClong |
+6.2% | +3.4% | — | — | +28.5% |
| $SLSlong |
+0.7% | -16.7% | — | — | -11.2% |
| $SMRlong |
+15.3% | -11.2% | — | — | -18.6% |
| $VSTMlong |
-1.5% | -10.7% | — | — | -1.8% |
| $WULFlong |
+8.2% | +1.4% | — | — | -10.4% |
| $ZVRAlong |
+2.2% | -3.1% | — | — | -8.5% |
Now that $MU to $SNDK have pulled a major recovery.
Good to have a reminder that the memory bottleneck hasn’t changed!
Same with CW lasers… substrates… or others.
But short term sentiment (depending on prices/macro) often does.
I think a lot of demand imbalances get worse than people expect:
- There’s some Japanese distributors in Nikkei today saying memory demand deficit has reached 40-60% (67-150% higher than supply). With general prices going up 50% by years end.
- $SPCX isn’t included in the $1.3T hyperscaler capex figures (I think Wells Fargo ets. ~$263b AI capex), so total capex figures might be surprising.
- $SNDK expects 80% gross margins to continue into 2030… (welcome to S&P 100)
- and once again you have long term visibility into 2031 now with companies like Samsung
Memory is very really volatile… some of my positions are up 270%+, so I find it a bit easier to hold through volatile periods.
But regardless, operating fundamentals doesn’t always align with short term price movements.
Same concept can be applied to other sectors.
↗ Quoting @aleabitoreddit
$MU$SNDK$SPCX
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MUlong |
-1.6% | -4.1% | — | — | +5.2% |
| $SNDKlong |
-0.1% | -6.1% | — | — | -0.0% |
| $SPCXlong |
+3.7% | +2.2% | — | — | +2.0% |
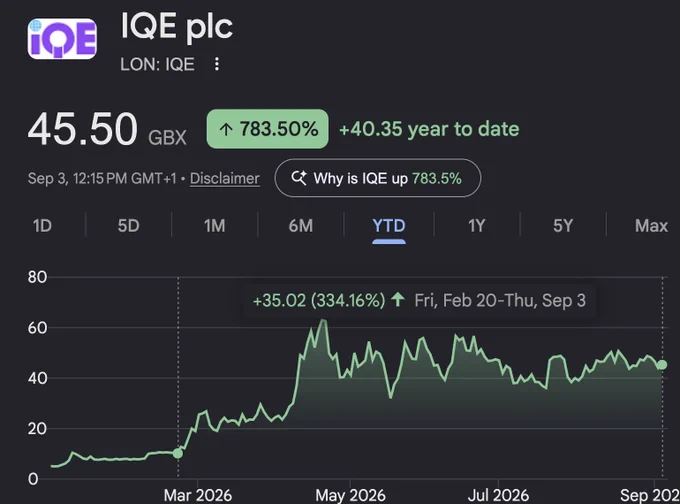
@KhalidIshaq85 Yes? I wrote my thesis on $IQE Q1 this year before $MTSI, $TSEM and the other material events came about.
$IQE$MTSI$TSEM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MTSIlong |
+3.5% | +4.8% | — | — | +9.6% |
| $TSEMlong |
+7.8% | +0.9% | — | — | +10.3% |
| $IQElong |
| | | | |
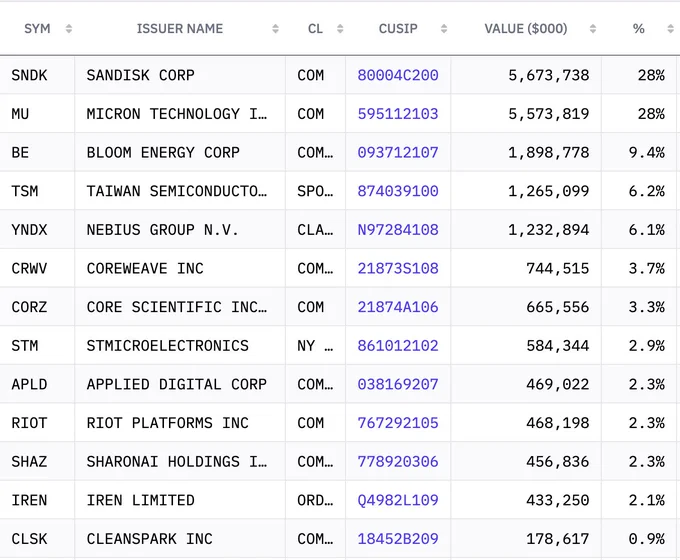
Just taking a look at Leopold's Situational Awareness Q2 13F latest holdings as of June 30th:
1. $SNDK - $5.674B
2. $MU - $5.574B
3. $BE - $1.899B
4. $TSM - $1.265B
5. $NBIS - $1.232B
6. $CRWV - $744.5M
7. $CORZ - $665.6M
8. $STM - $584.3M (new)
9. $APLD - $469.0M
10. $RIOT - $468.2M
11. $SHAZ - $456.8M
12. $IREN - $433.3M
Less material positions includeed $CLSK, $KEEL, sei-network:native, $WYFI, $BTDR, $TE, $HIVE, $VSH, and others.
Seems like Situational Awareness concentrated around memory (Sandisk, Micron), that have low forward multiples but high visibility into 2030.
As well as Anthropic/energy/power adjacent from colo/neoclouds + Bloom.
Some of the bottlenecks like the MLCC trade, he couldn't see play out (Taiyo Yuden, etc). due to July's liqudation. And some are new like $STM (eg. MCU price hikes).
With core winners of everything such as $TSM (but less high-beta).
This looked similar to my H2 2026/early 2027 portfolio with Nebius, Micron, TSM, colo players and others as core focus. (I've heavily concentrated on upstream networking/legacy memory currently, with a lot of name overlap).
But always cool to see what others are doing.
$SNDK$MU$BE$TSM$NBIS$CRWV$CORZ$STM$APLD$RIOT$SHAZ$IREN$CLSK$KEEL$SEI$WYFI$BTDR$TE$HIVE$VSH
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $APLDlong |
+4.0% | +9.0% | — | — | -2.2% |
| $BElong |
+8.4% | +23.9% | — | — | +27.5% |
| $BTDRlong |
+10.9% | +14.8% | — | — | -2.3% |
| $CLSKlong |
+11.0% | +17.2% | — | — | +13.6% |
| $CORZlong |
+6.5% | +7.6% | — | — | -4.9% |
| $CRWVlong |
+4.5% | +17.3% | — | — | +7.6% |
| $HIVElong |
+12.1% | +14.0% | — | — | +8.3% |
| $IRENlong |
+5.2% | +14.6% | — | — | +3.2% |
| $KEELlong |
+7.7% | +19.3% | — | — | +13.7% |
| $MUlong |
+0.2% | +7.5% | — | — | +11.8% |
| $NBISlong |
+3.2% | +17.8% | — | — | +15.6% |
| $RIOTlong |
+13.4% | +18.4% | — | — | +8.1% |
| $SEIlong |
+0.5% | -3.5% | — | — | +48.9% |
| $SHAZlong |
+1.3% | +4.5% | — | — | +0.8% |
| $SNDKlong |
+0.1% | +13.6% | — | — | +12.0% |
| $STMlong |
+1.1% | +1.7% | — | — | +5.4% |
| $TElong |
+6.3% | +15.0% | — | — | -9.6% |
| $TSMlong |
+0.4% | +4.8% | — | — | +10.0% |
| $VSHlong |
-0.5% | +3.5% | — | — | +6.7% |
| $WYFIlong |
+8.5% | +11.6% | — | — | +4.1% |
I want as much % ownership of the companies that lead AI’s next architectural shift as possible.
Not optimizing for USD returns at this point since even if Sivers goes to $0, I’d be completely fine.
Also my thesis was for H2 2027 for CPO scale up, not August 2026 wireless revenue.
There’s still time for management to reorganize, and I think this crash sends a good message.
$SIVE
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $SIVElong |
| | | | |
I don’t want to play investor activism here:
But I hope the recent crash sends a message to $SIVE what investor base + focus really matters (not Sweden, not wireless).
As well as that they should fire whatever board member or executive gave into local media criticisms:
And told the CEO to prioritize on non-photonics / near term revenue, since the discussions was on AllSpace + pipeline conversion now. Not Ayar/GFS and H2 2027/2028 opportunities.
It’s not hard to set clear future goals like NASDAQ listing filing by H1 2027 and use all your resources to execute on that.
Not vague post and language hedge like no-growth conservative companies do.
I’d argue this is better long term so they consolidate around:
NPO/CPO, US funding, and forward vision + execution through scaling/M&A.
Including divesting wireless/satcom/5G to 100% focus on photonics, if those are redirecting priorities.
I’m still holding my 1M+ share count position but not going to blindly cheerlead or hold a company if they become misaligned on what I originally invested in them for (CPO).
↗ Quoting @elpidalymp33598
$SIVE$GFS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $GFSlong |
+1.3% | +4.5% | — | — | +9.3% |
| $SIVElong |
| | | | |
I don’t want to be on any board or be an activist investor, pls stop recommending me lol!
I’m just putting out my thoughts on how I see them become a $LITE type company, and operationally they’re in an amazing spot.
In the end, it all comes down to the leadership’s execution on their vision, and that part is out of my hands.
I’m still holding my positions, but people should make their own judgement on what they see happening.
$SIVE$LITE
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $LITElong |
+0.2% | +12.6% | — | — | +11.7% |
| $SIVElong |
| | | | |
I mean I do have 1 single share of $IREN now, so I'd love to see them get a deal with Anthropic.
There were leaked memos suggesting that Anthropic was looking to secure more in Australia, and that just so happens to be the country Iren was heavily investing in.
Buuut, the $25-30B capex number is always a bit daunting during current macro, despite securing a lot of financing via prepayments.
$IREN
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $IRENlong |
-0.8% | +20.4% | +10.1% | — | +10.1% |
Macro has clearly cut high beta AI valuations over the past few months. But I try to stay focused on fundamentals.
If you're curious about my take though:
We're seeing record visibility with
- memory (2031), photonics (2029-2030), etc LTAs
- $NBIS, $AWS, etc. massive demand imbalance for compute despite capex spend.
- combined with record projections ( $NVDA 70% growth 2027, $SMCI $60B+ new server orders, etc).
vs.
uncomfortable macro where:
- Warsh said the Fed has "more work to do" if underlying inflation isn't clearly returning to 2%.
- July PCE came in at 3.7% Y/Y
- July jobs report payrolls fell by 23k with unemployment at 4.1%
-10Y Treasury high/ 30Y highest since 2007
- Iran tensions continuing
- Japan Yen weakened to 160/ 2 rate hikes in Korea
And with rate 40/60 in favor of 25BPS near-term hikes.
There's definitely implications on financing + too many third/fourth order effects for me to personally map.
I'm not a macro expert but my take is:
The AI buildout will continue w/ $1.3T+ capex poured upstream expected next year, flowing through many bottlenecks and chokepoints.
While markets chopped off forward valuations and rotated toward currently profitable/defensive companies.
I don't know what's going to happen, especially since rate hike odds are almost a coinflip, and Trump posts can change sentiment overnight.
As long as I don't see indicators of hyperscalers cutting capex or demand wavering.
I'm staying long despite macro volatility, since I want ownership of the names controlling the future of the AI buildout.
And if there's any indicators of better macro climates, high beta are typically the fastest to recover.
↗ Quoting @dBooray
$NBIS$NVDA$SMCI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $NBISlong |
-3.3% | +9.7% | +14.3% | — | +14.3% |
| $NVDAlong |
-1.5% | +4.3% | +3.6% | — | +3.6% |
| $SMCIlong |
-1.5% | +6.2% | +10.1% | — | +10.1% |
@balllvest With how the trends are going with $MRVL and Mediatek. My guess is Alchip (disclosure, I own this) or $QCOM might be next.
I think the ASIC pie gets bigger for all of them though.
$MRVL$2454$3661$QCOM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MRVLlong |
-0.6% | +5.6% | +24.8% | — | +24.8% |
| $QCOMlong |
-2.3% | -0.5% | +8.5% | — | +8.5% |
| $2454long |
| | | | |
| $3661long |
| | | | |
@SidkMena Yeah, I was forced to averaged down during that massive July sector crash.
Now up ~55% on FOCI and ~50% on Xintec at least but some of my other names are still recovering
$FOCI$XINTEC
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $FOCIlong |
| | | | |
| $XINTEClong |
| | | | |
$TSM Vice President of Advanced Packaging:
"Foundries can scale up the optical engine, but the real bottlenecks to large scale deployment lie elsewhere...
Including lasers, optical fiber, fiber-optic connectors, and test" (UDN)
Just some bucket ideas:
Lasers: $LITE, $SIVE, $COHR, LandMark (3081), LuxNet, Sumitomo, Furukawa
Optical fiber / FAU: Foci, Browave, $GLW, Sumitomo
Fiber Optic / CPO Connectors: BizLink, $GLW , Fujikura, Nextronics, COXOC
CPO testing: MPI (6223), Advantest, $FORM, Msscorps, $KEYS, Chroma
(disclosure: exposure to theme above, individual names not named by TSMC)
There are others I like as well, such as ShunSin, which now has explicit TSMC COUPE exposure but probably belongs under a different category like packaging/integration.
eg. "Foxconn unit ShunSin confirms TSMC COUPE partnership"
I don't think there's anything too new vs. H1, aside from ongoing news (eg. FAU looks like there will have a demand imbalance in 2027, from a report last week).
But it's helpful to reiterate overall beneficiaries from time to time...
$TSM$LITE$SIVE$COHR$GLW$FORM$KEYS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $COHRlong |
-2.1% | +1.5% | +3.6% | — | +3.6% |
| $FORMlong |
-5.2% | +3.3% | +48.5% | — | +48.5% |
| $GLWlong |
-2.1% | +3.7% | +3.4% | — | +3.4% |
| $KEYSlong |
-1.1% | +1.4% | +12.8% | — | +12.8% |
| $LITElong |
-5.0% | -3.7% | +6.1% | — | +6.1% |
| $TSMlong |
-0.3% | +3.3% | +10.1% | — | +10.1% |
| $SIVElong |
| | | | |