Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
Memory names from Kioxia finished up a whopping +17.18%. Samsung up +6.15%.
Optical networking from $SIVE, $LITE, and $AAOI are showing signs of recovery, all up 4%+.
Neoclouds from $NBIS to $IREN all up 4%+ premarket.
$INTC to $AMD to $MRVL all up 4%+.
Does the Cramer effect work on the entire AI trade?
↗ Quoting @jimcramer
$SIVE$LITE$AAOI$NBIS$IREN$INTC$AMD$MRVL
If you’re curious why $NBIS is up after hours.
$NVDA disclosed it owns 9.3% beneficial ownership of Nebius via SEC filings.
Not exactly too new since it dates back to Nvidia’s existing share position of 1.19M shares + $2B prefunded warrant of ~21M shares.
But great for sentiment having Nvidia be a large shareholder of the Neocloud leader.
$NBIS$NVDA
$IREN +19.69% after revising ARR target to $4B+ from new AI cloud contracts. Its customer base now includes Microsoft, Nvidia, Perplexity, and Figure.
$HUT +10.45% off a 15Y $9.8B AI DC lease
$CIFR +16.76%
$CLSK +13.7%
$WYFI +9.18%
$NBIS and $CRWV are taking their time in the shower.
But does look like Neoclouds/Colo players are sharply recovering following new catalysts, such as Kimi compute shortage news and new contracts.
$IREN$HUT$CIFR$CLSK$WYFI$NBIS$CRWV$MSFT$NVDA
Some updates on bottleneck timelines:
- ABF substrates: 1 year
/ eg. Ajinomoto (2802) for ABF film, Ibiden, Unimicron, Nan Ya PCB, etc make the substrates
- HDI Boards: Over 6 months
/ Victory Giant (300476), Zhen Ding (4958), Unimicron, Compeq (2313), Meiko (6787)
- Multilayer boards: ~6 months
/ Victory Giant, WUS (002463), $TTMI, Gold Circuit Electronics (2368),
- CCL: Over 6 months (severe shortages of materials)
/ Elite Material (2383), Shengyi (600183), TUC (6274), ITEQ (6213), Nan Ya Plastics (1303), Resonac (4004)
Mitsui Kinzoku (5706) / HVLP copper foil. Nittobo / glass fiber/cloth
- MLCCs, chip resistors, tantalum capacitors, aluminum electrolytic capacitors: 15-20 weeks to 1 year+
MLCC: Murata (6981), Samsung Electro-Mechanics, TDK (6762), Taiyo Yuden (6976), Yageo (2327), Walsin (2492)
Chip Resistors: Yageo, Walsin, KOA (6999), Rohm (6963) and $VSH
Tantalum capacitors: Kyocera/AVX, Yageo/KEMET, $VSH again
Aluminum electrolytic capacitors: Nippon Chemi-Con (6997) Nichicon (6996) | Timelines sourced from Digitimes, did the honors of adding in related companies.
But it's slightly more nuanced since MLCCs and others mix. in commodity types vs. AI DCs.
Regardless, just some helpful mapping.
$TTMI$VSH$2802$300476$4958$2313$6787$002463$2368$2383$600183$6274$6213$1303$4004$5706$6981$6762$6976$2327$2492$6999$6963$6997$6996
@syl_52 I'm not posting anything actionable here. Just giving people a heads up on about ADR timeline conversion for SK Hynix on the 29th.
And that it's likely premiums might converge if institutions decide to arbitrage.
$SKHY
- Sk Hynix mainly traded in Korea
- $SKHY lists in the US with limited shares, ~2.5% of the float (this is called ADR)
- Even though SK Hynix are the same company, the shares trade independently.
- Sk Hynix US traded at a 20-50% premium to SK Hynix Korean listing due to limited supply, but lot of US demand.
-> ADRs allow for conversion between Korea Shares to US Shares, and conversion will start on the 29th
- If you convert 22.5% of the Korean supply to the US, that 20-50% premium is likely to go down
eg. If there's limited mangos, and someone pays $3 for mangos.
You buy the same mango for $1. You keep buying those $1 mangos and selling for $3 until the mangos pricing converge. That's called arbitrage and what likely traders would do.
$SKHY
For anyone watching the 25%+ premium in $SKHY versus SK Hynix's Korean shares:
The ADRs and local shares become convertible on July 29.
Should open the door for arbitrage and likely compress the ADR premium. Maybe lifting Korean shares or pressuring US shares.
2.5% currently is the US ADR stock, so an additional 22.5% can be converted.
$SKHY
If $AAOI are projecting $1.4B a quarter q3 2027 ($471m/month), which is $5.6B revenue annualized, (targeting 40%+ gaap gross margins).
And they’re a $8B MC…
Or if personal $SIVE CW Win capacity projections are around ~$400m midpoint array revenue off 60% gross margins.
And that’s a $1B MC.
Just applying a low 20 fwd p/e might rerate optical names considerably.
Even with other names like $LITE, they’re completely sold out for the next 2 years, and having that sort of demand visibility… Is not a bubble.
Europeans tend to use TTM to value companies while optical names are 2027-2028 growth stories.
$AAOI$SIVE$LITE
The nice thing about X is seeing cultural differences:
I get a bunch of sidelined European accounts up 2% YTD off bank saving interest.
Coming out of hibernation, and saying all along that investing in $AAOI for photonics or Samsung for memory is considered gambling.
And celebrating when everything AI from $MRVL to $NBIS to $INTC finally had a crash after a few hundred percent rally.
Think it’s mainly a lack of understanding of technological shifts mixed with capital preservation culture vs. growth.
↗ Quoting @luis_garci71455
$AAOI$MRVL$NBIS$INTC$SSNLF
@waynexonline $AAOI themselves gave a $471m / month estimate starting H2 2027.
If 800g gets revised up sharply across the board, that number might get hiked.
$AAOI
Thanks, love reading the comments!
Goldman Sachs raised Innolight PT to 2581 RMB. Roughly 163.6% upside from current valuations.
But the largest thing is its 2026–2028 earnings est revision raised by a whopping 65%/108%/119%, based on:
- Much higher silicon photonics module volumes
- scale out, scale up, scale across volumes
- 1.6T/3.2T lifting blended ASP + margins
- increase in AI capex
This is typically very material read through on the optical sector since:
I tend to think of Innolight as a $TSM (semi capex) type read on how the photonics landscape is doing.
Eg. Higher silicon photonics penetration means more TAM for cw lasers like $SIVE (cw) / SOI wafer demand for $SOI. ASP hikes for future gen is positive for the other optical markers too.
Think my other takeaway outside the report was Innolight stating 800g demand was growing more significantly than expected from their transcript on the 12th.
Which in turn signals more demand for names like $AAOI to $LITE next earnings.
TLDR: GS gives high earnings projections during a time of massive corrections.
Fundamentally, broader photonics ecosystem should be happy when it’s ER time.
↗ Quoting @cedricsx9
$TSM$SIVE$SOI$AAOI$LITE
$META in talks to lease compute to Anthropic in a $10B dollar deal.
Seems like they saw how profitable
$SPCX $45B compute deal was.
But just goes to validate Neocloud business models like $NBIS, $IREN, and co if hyperscalers are copying their homework.
Source: NYT
$META$SPCX$NBIS$IREN
Feels bad, -49.4% drawdown this month after the recent crash.
My portfolio is mainly AI chokepoints and bottlenecks.
In the memory, photonics, robotics, and upstream semis, (on margin) which all tend to be higher beta than others. But reduced leverage recently from the crash.
I see a lot of people making fun of the drop or AI names, saying it’s obvious that:
- “AI is a bubble”
- “memory/kospi is a bubble”
- “photonics is a bubble”
- “humanoids won’t get anywhere”
- “neoclouds will get replaced by hyperscalers like Meta”
And a bunch of retail + bots saying “sell everything, it’s never going to recover”.
But I have conviction that all these themes are backed by structural revenue growth or technological shifts.
And I’ve had similar drawdowns back when there admin threatened global tariffs, before markets pulled off a recovery.
I personally have a longer horizon + higher tolerance for volatility than others, to see how this plays out.
Especially considering a lot of retail view things on a week to week basis: no, my thesis isn’t wrong yet if I project revenue inflection in H2 2027 and it’s 2026 now.
Anyway, feels bad short term just wanted to share anyway for transparency.
↗ Quoting @aleabitoreddit
$META
@johnoao CPO hasn’t scaled up yet. Lot of their earnings come from 2028 TAM for FAU.
There’s just a lot of uncertainty recently due to CPO delay reports and $GLW glass bridge.
$GLW
@LetsGoBflo17 I actually like $IREN fundamentally post Mirantis acquisition. Since it combines software orchestration with their existing secured GW capacity.
But not hopping onboard personally unless they address executive stock based compensation and financing mechanics though.
$IREN
Agreed! It’s nice to remember your thesis during a market crash.
From my own personal thesis, if $AAOI hits $1.4B quarterly revenue start of Q3 2027. Which is annualized $5.6B off a $8B MC.
Is it “over” for the company if that revenue ramp hasn’t even shown up in the quarterly earnings… when it’s 2026?
Same applies to my CPO sector exposure like $SIVE, an architecture shift led by $NVDA.
If scale out volume ramps from H2 2026 into 2027, and scale up heavily volume ramps into 2028.
Is it “over” that $0 -> $91B TAM expansion (per GS) hasn’t even hit yet?
With robotics like Agility, is it over in 2026 if the listing hasn’t even happened yet and humanoids haven’t ramped?
I personally think current market conditions are a reflection of liquidity and leverage, not individual fundamentals.
It’s brutal for everyone to see KOSPI, TW, Nikkei, and AI, space, robotics sector stocks crash recently.
Especially when there’s a lot of irrational behavior stemming from those leverage.
In the end, we can’t tell you what stocks to buy, what timeframe you should sell, how to size your positions, or what you should do.
Only share personal thoughts or research and track if they get validated over time.
So it’s extremely important to build your own thesis, since everyone has unique risk tolerance or investing timeframes.
And that usually leads to having higher conviction during crashes.
↗ Quoting @pepemoonboy
$AAOI$SIVE$NVDA
@babybluecream Yeah, my $EWY longs crashed quite a bit.
I still think the operating income that SK Hynix and Samsung produces will catch up to the MC eventually, so I’m holding my memory positions.
Regardless, not a fun time to watch Asian markets from Nikkei to Taiwan to Kospi drop so much.
$EWY$SSNLF$HXSCL$N225$KOSPI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $EWYlong |
+0.2% | +0.3% | +10.6% | — | +12.5% |
| $HXSCLlong |
| | | | |
| $KOSPIlong |
| | | | |
| $N225long |
| | | | |
| $SSNLFlong |
— | — | — | — | — |
Kim Sunwoo of Meritz Securities: "This Is Not the Time to Sell Samsung Electronics and $SKHY"
They claim markets are excessively misunderstanding the situation with semis. And that DRAM shortage will intensify in the second half of this year.
- H2 2026: "suppliers can fulfill only 75%–80% of DRAM demand".
- 2027: "fulfillment is expected to fall into the 60% range."
In the article, they attached market forecasts that show SK Hynix with a 2027 3.5x P/E and Samsung a 3.9x P/E.
Think the $INTC CEO said it best around timeframes with his quote "no relief in memory supply or pricing until at least 2028".
Especially after $MU 16 LTAs with favorable take or pay volume contracts... memory demand seems structural.
$SKHY$INTC$MU
My guess is we’re close to market bottom on semis from $INTC to $LITE.
A good indicator is if everyone on $RDDT blew up their portfolios to $0.
$INTC$LITE$RDDT
I’m not sure if you’re aware but the entire AI sector is dropping indiscriminately right now.
A $1T company like Samsung is down -26% this month. $MRVL is down -31%.
So higher beta names tend to move a lot more like $AAOI and $SIVE with their 50% drops.
But recoveries tend to be a lot more volatile like $AEHR 50% single day gain after ER.
$MRVL$AAOI$SIVE$AEHR$SSNLF
Morgan Stanley listed $SIVE as the three core CPO laser players alongside $LITE and $COHR in their note 3 days ago.
Fidelity Research, JP Morgan and others have started to take active positions. They recently raised an oversubscribed institutional round at 57 SEK.
This is all ahead of US NASDAQ listing.
I personally see short term liquidity disconnects relative to forward revenue around now and I'm sure institutions are capitalizing on it.
$SIVE$LITE$COHR
I think people tend to forget that $LITE went from a $3B valuation to $60B+ in 2 years time from owning the EML chokepoint.
This was before the 9x TAM expansion to ~$154B per GS by H2 2028.
$SIVE has the opportunity to dominate the next CW chokepoint with 1.6T and CPO.
And it's sitting at ~$1.1B now.
$LITE$SIVE
Lot of people were curious about $SIVE capacity volume ramp modeling through fab-light (Win Semi + others):
Using 10% of Win's wafer capacity as a low-end allocation (65% yield assumption, $50-$75 ASP):
Sivers would support $341-$512M worth of annual array revenue. Given upper end of managements 50-60%+ gross margin target, would be roughly:
$205–307M of annual gross profit.
Against Sivers current ~$1.1B MC, would be ~:
3.6–5.4× MC/gross profit if this capacity scenario plays out in 2028.
And at 15% would be $307–461M in gross profit (2.4–3.6× MC/gross profit)
Sivers CEO also replied that they're working with more fabs for capacity. And from an older deck, there looks to be more qualifications since 2024.
So capacity targets might be larger than what's stated here as CPO takes off.
I also expect to see revenue pipeline projections hiked in future quarters, as more qualification suppliers to into HVM.
_
As for demand side, CW also happens to be very bottlenecked.
Lumentum are buying CW off the open market due to EML obligations from their ER transcript.
And $AMD are signing LTAs to secure CW capacity (from Trendforce). So when Sivers is ramping with $GFS, $JBL, Ayar, $POET, O-NET and others...
Given the current constraints, it's highly likely any independent qualified capacity that comes online would be absorbed.
And as a cherry on top, Morgan Stanley named $SIVE (~$1.1B) as one of the three leading CPO laser players .
Alongside $55B+ players Coherent and Lumentum in their recent note for a reason...
_
TLDR: Sivers only needs a low end allocation from Win to make substantial gross income relative to current valuations.
I think the largest revenue upside that isn't modeled in if they TAM expansion with M&A after US NASDAQ listing.
By copying the Lumentum playbook with Cloud Light to build out entire transceiver modules or with optical engines.
↗ Quoting @StormDirac
$SIVE$AMD$GFS$JBL$POET$LITE$COHR
I personally think valuations are extremely stupid now on $AAOI and $SIVE.
With AAOI you're doing $5.62B annualized revenue (probably higher), by midpoint next year. And it's a $8B MC.
With Sivers, I would est. it's close to ~5 forward 2028 P/E off 10% win allocation, 65% yield, and $75 ASP.
$AAOI$SIVE
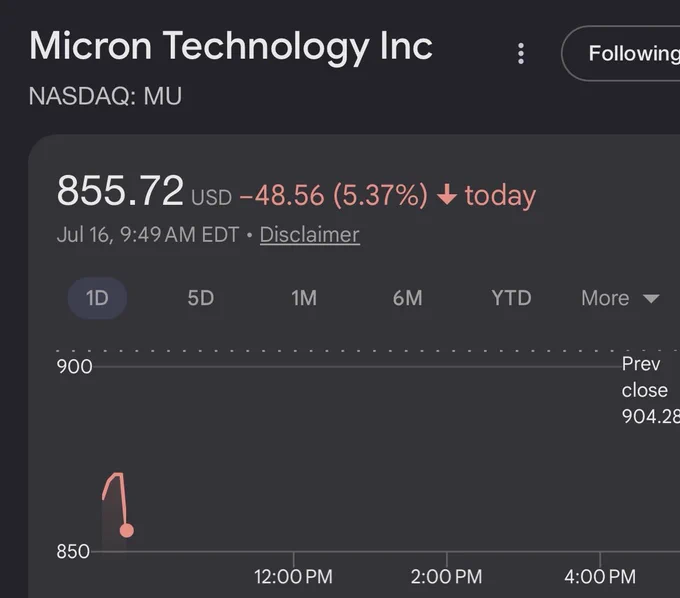
Today, $MU announced it signed memory LTAs with $QCOM.
Interesting reaction to see Micron proceeded to drop 5.37% right after.
Doesn’t quite feel like there’s anything individually wrong with memory or AI names with all these structural agreements signed?
More like the tail end of deleveraging / margin cascades.
$MU$QCOM

 @aleabitoreddit
Jul 21, 2026 · 04:13 ET
stock