Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
After $AXTI went from $13 to $140, somewhere along the way up they had a massive float expansion along with dilution.
Which it got approved, so as I mentioned before, I wasn't as comfortable talking about it if there's excessive dilution on retail investors.
But I do think it's undervalued if they weaponize price hikes like $SNDK.
$AXTI$SNDK
Are you stupid?
1. $JBL mass producing 1.6T LRO is revenue.
2 O-Net mass producing ELS is revenue.
3. $GFS using $SIVE as reference laser for the hyperscalers is revenue.
4. Ayar joining $NVDA NVLink for CPO and using $SIVE for mass production is revenue.
5. Other pluggable players, potentially Eoptolink/Innolight mass producing pluggables with $SIVE as lasers is revenue.
6. $POET entering volume production is revenue.
$JBL$GFS$SIVE$NVDA$POET
Nobody should care about TA charts since people just made up squiggly lines trying to convince others to sell.
$SIVE just raised an emergency $70M for mass production likely for allocation from fabs.
With $JBL, $POET, $AEVA, and others volume ramping near term.
Then $GFS, Ayar, and many other players are volume ramping later in 2027.
Sivers also confirmed intent to complete NASDAQ Listing in the next few quarters.
It's probably my highest conviction photonics long, everything seems to be coming into place.
$SIVE$JBL$POET$AEVA$GFS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AEVAlong |
+0.9% | -8.1% | -26.9% | — | -41.4% |
| $GFSlong |
-1.3% | -0.2% | -28.4% | — | -31.2% |
| $JBLlong |
-0.9% | -2.6% | -7.7% | — | -15.9% |
| $POETlong |
+2.2% | -0.7% | -20.2% | — | -14.6% |
| $SIVElong |
| | | | |
@ram_blings NP, I'm not sure if people remember this but $SIVE went up +70% in a day off $GFS news. And $AAOI has random +20-30% days.
They're also capable of doing the opposite.
Photonics sector are very volatile, but directionally they follow fundamentals in the long run.
$SIVE$GFS$AAOI
Photonics is backed by actual revenue numbers and it's an architectural shift championed by $NVDA.
Quantum barely has any revenue.
$LITE is completely sold out for the next 2 years (per $POET AGM) likely starting into 2029. Lumentum is so strained that they buy CW lasers off competitors (earnings transcript)
$COHR is bottlenecked, so they buy EML off Lumentum.
Then, $AAOI is coming in with Made-in-America independent CW capacity, are projecting $1.4B/quarterly revenue ending H1 2027 of a stupid $9.3B MC today.
So all the CW capacity from independent players who have it now like $AAOI or $SIVE are likely to become scarce resources.
Many other hyperscalers have already started LTA discussions (per Trendforce). And players like $AMD are currently talking with players such as $AAOI (Rosenblatt channel checks).
Thematically, next 2 years is 9x TAM to US$154B per GS reports, especially with 16x/45x dollar content increase in scale out/scale up.
Then there's the overall thematic AI drop from $META, which is widely misunderstood because people conflate what "excess capacity" means. And as UBS mentioned, Meta planning a cloud offering is NOT NEW NEWS.
Bloomberg just has a tendency to publish information that causes doom drops across the semi sector like Nvidia export controls a few months back.
But I'm familiar with what I'm holding so I'm confident in these numbers playing out.
Especially when all the major players are sold out, the fundamentals catch up eventually.
↗ Quoting @walker119298
$NVDA$LITE$POET$COHR$AAOI$SIVE$AMD$META
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+2.0% | +1.0% | -22.0% | — | -17.9% |
| $AMDlong |
+6.6% | +5.6% | -8.0% | — | +18.1% |
| $COHRlong |
+0.7% | -1.8% | -21.1% | — | -13.7% |
| $LITElong |
+0.4% | +7.9% | -2.0% | — | +33.2% |
| $METAlong |
+1.2% | +17.6% | +101.5% | — | +77.2% |
| $NVDAlong |
+0.4% | +4.1% | +3.0% | — | +17.4% |
| $POETlong |
+2.2% | -0.7% | -20.2% | — | -14.6% |
| $SIVElong |
| | | | |
Names like LeaderDrive are at all time highs? Depends on the company of course.
Liquidity works a little differently in America, usually focuses on downstream frontier industries like space, robotics, AI, and such.
If we look at $RKLB for space as one example that has premiums relative to revenue.
$RKLB
I’m personally long $CCXI and have highest concentration in Agility Robotics (NFA). It’s currently around a ~$4.9B valuation.
Figure’s last round was $39B last year, and that was before the increasing interest in humanoids/robotics this year.
Then a large part of $TSLA $1T+ valuations come from humanoids.
I like companies like LeaderDrive… but usually the downstream players capture the most value in the end.
And I find it rare to see one that has public exposure early on.
$CCXI$TSLA
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $CCXIlong |
-9.8% | -15.0% | -27.4% | — | -39.3% |
| $TSLAlong |
+6.7% | +3.3% | -20.9% | — | -9.9% |
I just realized Boston Dynamics CEO shared the same sentiment:
“Robotics is next. America’s next 250 years will be built by robots”.
However, currently China accounts for 54%+ of all global robotics deployments.
- calls for Internet scaleable database of physical world (kinda got reminded of Niantic that has a huge dataset from Pokemon Go)
- dedicated National robotics strategy to compete against China’s leadership in this space
- ISO + regulation for robotics safety
This is all high level:
But my prioritize thought process is how do we support and scale a Made in USA supply chain for robotics/humanoids?
I’ve been hammering home rare earths for the longest time, that the US isn’t doing enough to subsidize or scale this industry.
But another thing to take note is subsidies for components, forcing $TSLA and others to use Chinese suppliers over Western ones, even if assembly is done in USA… to keep costs down.
Which is why I’ve liked Agility Robotics $CCXI since they source 75% of parts from the US, despite higher BOM to start out with.
Regardless it’s pretty clear this Robotics is coming and becoming a national security priority:
From the days of backflipping humanoid YT videos.
↗ Quoting @aleabitoreddit
$TSLA$CCXI
@mazo7846 I actually think $IREN has potential after their Mirantis acquisition + capacity they have.
It’s just the way they do things with ATMs and excessive SBCs makes it hard to be bullish on just from financing structures.
$IREN
@KlNKLAADZE My opinion is that CEOs should keep the equity they have and work toward making that appreciate in value. Like what $RKLB founder does.
Rather than relying on large compensation grants.
$RKLB
$IREN founders award themselves $1.14B+ of stock based compensation.
Vesting over 4 years timeframe. This is amid their active $6,000,000,000 ATM.
I’m not going to say anything but I think it speaks for itself.
$IREN
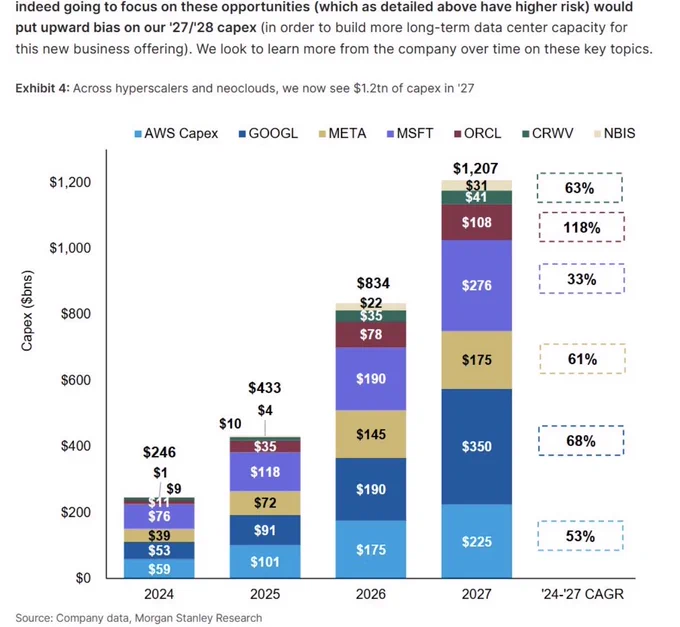
@mkfilko Morgan Stanley for example is expecting an upward revision on AI capex from the $META announcement too…
So selloff on all AI names seems like a bit much.
$META
@DogUrineCapital This is pretty disgusting to see $MRVL down -11%, $AMAT down -11% to $NBIS down -18%
On the bright side a lot of the higher beta/smaller names like $AAOI frontran the drop.
So those are faring better
$MRVL$AMAT$NBIS$AAOI
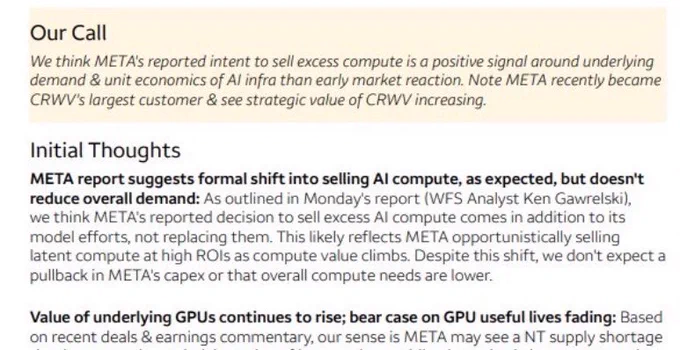
Wells Fargo: $META intent to sell excess compute is a positive signal around underlying demand and unit economics of AI.
“Despite this shift, we don’t expect a pullback in Meta’s capex or that overall compute needs are lower”
Regarding Neoclouds: WF thinks it validated the massive AI infra opportunity as well as acquisition opportunities. Despite any potential competition for Neoclouds.
I’m inclined to agree with Wells Fargo here and say markets completely misunderstood Meta’s excess compute comment.
$META
I feel like Trump is probably going to like this idea:
OpenAI discussed giving the US gov a 5% stake in its company per FT.
If this turns into an $INTC type situation, would be interesting if the US government becomes a soft backstop for their $1T+ in future capex/obligations.
$INTC
@runty_days Sure so when they go public, it’s just a ticker change from $CCXI to $AGLT.
At $10 it was around ~$3.1B MC including est. cash/pipe. At current levels it’s around ~$5.5B.
I personally benchmark it against Figure, which is last valued at ~$39B
$CCXI$AGLT
Where did I ever say that? Majority of my portfolio is concentrated in photonics with names like $SIVE and $AAOI.
However, I’m allowed to talk about other exciting developments as well… Such as the first listed US humanoid player?
I still think CPO/optics has the fastest TAM ramp out of any industry, just a bit early since I’m projecting revenue inflection really hits ~H2 2027.
I’m personally down a lot past few weeks, but I’m convinced my thesis with laser chokepoints and others plays out.
$SIVE$AAOI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-13.0% | -17.7% | -32.1% | — | -28.6% |
| $SIVElong |
| | | | |
@LedgerJuli19855 I’m aware of $XPEV and other names like Ubtech.
Even if I see them having potential (especially the robot AI girlfriend with the latter).
Just a personal preference to invest in America with more critical technologies like robotics.
$XPEV
Just dropping these 3 slides from Agility Robotics ( $CCXI ) presentations.
For the US robotic program doomposters:
1. “75% of parts” - sourced from the USA
2. Just eyeballing the graph, looks like <$30k BOM mass production.
People were just looking at the ~$145K cost.
3. 10,000 RoboFab capacity, and they build in Salem/Pittsburgh/Fremont (USA).
So looks like majority US supply chains with targets of <$30K mass production
It does help they’re backed by $AMZN / SoftBank / Foxconn / $NVDA as investors to get this done.
Just personal thoughts as a shareholder in $CCXI (NFA):
My personal biggest fear were US humanoid leaders like $TSLA were just building out their entire supply chains in China.
So US robotics could just be export controlled/halted down the road.
eg. South China Morning Post: ‘Optimus chain’: Chinese suppliers form the backbone of Tesla’s humanoid robot initiative and engaged with hundreds of Chinese component suppliers.
And that Western companies are not able to lower costs to a competitive level + are forced to use Chinese components.
I'm still not sure how they're going to do it but if Agility can achieve those mass production targets with that BOM cost in the USA/West.
It would be a great validation for Made in America US robotics programs.
IMO the top 5 US humanoid programs right now in terms of commercialization potential are:
1. Tesla Optimus
2. Figure
3. Agility Robotics
4. Boston Dynamics (yeah KR parent)
5. Apptronik
Tesla is a $1T+ company. Figure is private and valued around ~$39B. Owning Boston Dynamics through Hyundai is a bit messy.
And I’d prefer not to invest in adversarial programs just as a personal preference.
So I’ve been personally excited for Agility to be listed as early as September.
$CCXI$AMZN$NVDA$TSLA
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMZNlong |
+0.4% | +0.8% | +12.4% | — | +3.1% |
| $CCXIlong |
+12.0% | -10.6% | -18.8% | — | -32.0% |
| $NVDAlong |
-1.4% | +3.3% | +1.6% | — | +15.7% |
| $TSLAlong |
-7.5% | -7.3% | -26.8% | — | -16.6% |
There’s a lot of disinformation going around about $META “cutting capex” because they “overbuilt”.
This is an “if” they have excess capacity.
And it looks like the opposite right now:
Hyperscalers like $GOOGL are so compute constrained that they had to cut allocations to Meta back in March.
Since Meta was using too much for internal projects.
Meta was immediately constrained so it looks like they were forced to immediately sign massive $48B+ contracts with Neoclouds like $CRWV and $NBIS.
Meta is selling excess capacity if there’s any, especially since their large contracts are take or pay from the Neoclouds.
If anything, I’m expecting their guided capex to go up as they build out more independent capacity.
↗ Quoting @nabq321
$META$GOOGL$CRWV$NBIS
Basically pre-market right now with the Neoclouds like $NBIS in simpler terms.
Costco: sells $5 chickens.
Walmart: mass buys those rotisserie chickens and sells excess as “Walmart Chickens”.
Stock Market: sells off Costco.
$NBIS$COST$WMT
@Deebeeng10 The Neoclouds like $NBIS are probably the ones powering this offering lol.
$NBIS
Finally, $META to build a Cloud Business to sell excess AI compute per Bloomberg.
Thought Meta should go up against GCP, Azure, and AWS eventually to increase revenue streams.
Meta up 6.65% premarket.
$META$GOOGL$MSFT$AMZN
Just a random thought, leading US humanoid players strangely me of the current LLM dynamics:
Agility ( $CCXI ) kinda feels like Anthropic for robotics.
With $AMZN and $NVDA heavily backing it, ingrained with $GOOGL Deepmind (like TPUs). And it starts off with enterprise commercialization.
Optimus is kinda off doing its own thing like xAI.
Supported by Tesla/Elon and his visionary roadmap as usual.
Figure is like ChatGPT
With Microsoft/OpenAI investing (kinda like Microsoft), then ended up kinda competing them by building their own VlA and setting them behind.
But ends up top 2 leaders anyway.
Boston Dynamics is Gemini
Kinda started the entire humanoids thing like transformers with backflip videos.
With R&D supported by $GOOGL but somehow let everyone else leapfrog them in commercialization.
And then there’s $NVDA just chilling, silently powering the entire humanoids ecosystem.
$CCXI$AMZN$NVDA$GOOGL
@AleksandarGenov Probably Agility Robotics going public with $CCXI and all the media narratives around it was the catalyst.
Feels like $OUST, $AEVA and other names were pretty flat until the announcement.
As for energy like $FCEL, $BE, seems pretty fundamental with new upsized contracts
$CCXI$OUST$AEVA$FCEL$BE

 @aleabitoreddit
Jul 02, 2026 · 13:26 ET
stock