Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,509 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
@0xHyperEVM Yeah $MRVL was $87 or so, $ARM was $130.
$87 -> $288 for Marvell
$134 -> $347 for Arm
not too shabby for my names? I still think many have a toooon of room to go like $AAOI.
$MRVL$ARM$AAOI
@soulbiri1 I think only $IBIT / $XLU / $META / $CRCL are red since that mention.
Maybe like 1-2 flat like $HOOD
But 25 for 30 like $NBIS green, and many by triple digits is pretty solid if you do equal weighted.
$IBIT$XLU$META$CRCL$HOOD$NBIS
Still think this US list from $MRVL to $ARM to $INTC was goated.
Just as a recap if new followers were wondering what US equities I like.
Especially because I've been talking about international companies recently. https://t.co/tZGLrFEGoh https://t.co/1mkk0NG6Ao
↗ Quoting @aleabitoreddit
$MRVL$ARM$INTC
@LightLogix I mean...
> $SIVE reference laser for $GFS
> $SIVE laser 1.6T LRO with $JBL + many more pluggable players
> $SIVE + Ayar + $NVDA NVLink
> likely $SIVE + Lightmatter / $MRVL Celestial with $NVDA NVLink
> Likely $SIVE -> $AMD CPO ecosystem too.
very compelling long idea.
$SIVE$GFS$JBL$NVDA$MRVL$AMD
@_king142 It's primarily just new news of US institutional accumulation of 5%+ of the company.
Whether it's JPM asset management or hedge funds using JPM, since US retail doesn't have access to synthetic exposure to $SIVE.
$SIVE
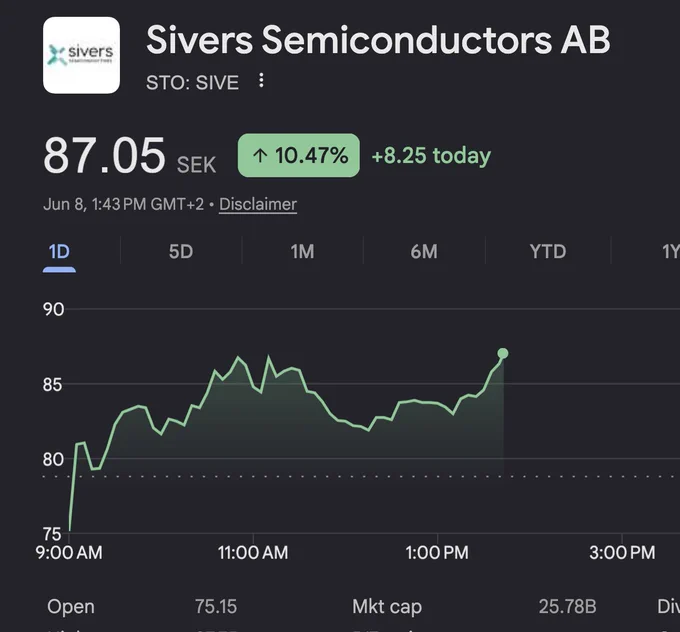
I think the implications of JP Morgan's disclosure of buying 5.25%+ of $SIVE is a lot greater than people think.
> $135M is pennies to US institutions. They can easily acquire 25% with their capital.
They're just constrained by the amount of float that's available from retail to buy.
> Signals to other institutions that other large institutions are buying up the float.
Which triggers more institutional interest.
> Given float is heavily shorted by Swedish Hedge Funds and random algorithmic ones.
If large US institutions like JP Morgan are starting to buying the float, it's a blaring signal to start and cover.
Of course, most of all, this is validating thesis of giving ideas to retail first to frontrun the institutions + the next CPO supercycle.
↗ Quoting @aleabitoreddit
$SIVE
All the outlets in China are just as confused as I am about 300376.
Just an FYI, these are all follower recommended stock ideas, not mine.
I’m just compiling all the shoutouts into a list of 30+ names related/adjacent to 800v DC exposure. https://t.co/e9yQiy71kG https://t.co/B80w74yFT3
↗ Quoting @aleabitoreddit
$300376
@ark_btc I compiled 32+ different names related to $NVDA 800V DC mentioned by followers. And posted them in a simple format for people to do research on.
Not my recommendations lol.
$NVDA
Surprised $SIVE is only up 3.36% off the news JP Morgan (institutional) bought 5%+ ownership of Sivers.
Just in the last month alone.
First major signal of major institutional buying of the float for Sivers. https://t.co/eSfKSQCEhM https://t.co/HCWzZjMG7t
↗ Quoting @aleabitoreddit
$SIVE
????
大家都知道这只是个众包名单吧?
300376怎么涨了20%啊哈哈 https://t.co/OdmqmIYB6V https://t.co/eactAFCmFg
↗ Quoting @aleabitoreddit
$300376
Okay chat, here's your compiled list chat of your favorite 800V DC related ideas.
1. $IFNNY - $115.8B
2. $ON - $46.2B
3. Lite-On (2301) - $16.03B
4. 6504.T - $14.1B
5. $VICR - $12.8B
6. $LFUS - $11.57B
7. https://t.co/1unM4FPf65 - $8.34B
8. $VSH - $7.86B
9. $ENPH - $7.36B
10. $NVTS - $5.77B
11. $POWI - $4.30B
12. $BDC - $4.18B
13. $EOSE - $3.86B
14. $SEDG - $3.82B
15. $AEHR - $3.1B
16. 6890.T - $2.66B
17. $WOLF - $2.16B
18. $CWR.L - $1.75B
19. $AMSC - $1.68B
20. https://t.co/43OXU9tx65 - $1.68B
21. $XFAB - $1.54B
22. $AOSL - $1.25B
23. $HYLN - $1.23B
24. $FCEL - $835M
25. $IQE.L - $780M
26. $ASYS - $276M
27. $RELL - $239M
28. 6844.T - $222M
29. 4973.T - $207M
30. $PAY.BR - $189M
31. 6616.T - $186M
32. 6882.T - $124M
33. $IPWR - $96m
Also included some adjacent ones you all mentioned like $FCEL or $EOSE anyway, tho idk it's great exposure. Ignored the clearer irrelevant stuff like $POET that people mentioned tho.
There's like 500 comments, but I guess X limits everything I can see.
We'll see how your highest conviction ideas do.
↗ Quoting @aleabitoreddit
$IFNNY$ON$VICR$LFUS$VSH$ENPH$NVTS$POWI$BDC$EOSE$SEDG$AEHR$WOLF$CWR.L$AMSC$XFAB$AOSL$HYLN$FCEL$IQE.L$ASYS$RELL$PAY.BR$IPWR$2301$6504.T$6890.T$6844.T$4973.T$6616.T$6882.T$PAY$POET
I do think LeaderDrive (688017) is China's standout component leader in the robotics sector.
I've done a lot of research on other robotics picks / $TSLA Optimus suppliers, but LeaderDrive is extremely unique.
Compared to others doing lower margin assembly, or lower value components, with higher design out risk.
Western institutions like Goldman Sachs Research flags LeaderDrive many times:
-> As a company with high technology barriers (eg. harmonic reduction gear).
-> and likely capturing high component value costs like planetary roller screws of each humanoid produced.
In simpler terms with LeaderDrive, you cover:
1. Many different components, with high barrier to entry
2. High BOM of each humanoid made, if you combine them together
3. Mass production capability at low cost.
For each humanoid made.
Please do your research on this topic before making your own decision; but long-term if you believe in humanoid sector growth: I think LeaderDrive (688017) is very compelling.
Risk is mainly coming from other emerging Chinese companies taking over market share of different individual components.
As well as mass-production margins decreasing over time; as seen with $VPG going from $750 (for early stage pre-production) -> $150 for sensors.
But in general, I don't believe companies outside China like Harmonic Drive (6324) can achieve the same costs for mass production, which is why $TSLA Optimus is creating extensive supply chains from China.
So we'll likely see supply chains be bifurcated with cheap mass production $15k-20K humanoids from Chinese supply chains. And higher cost humanoids from Western supply chains.
Again if you look at current P/E ratios and say it's high; a lot of it is misunderstanding comes from not looking at forward growth:
Nothing has been mass produced yet. AGIbot has recently achieved 10k units produced back in March.
But in the next 3-5 years, the TAM of the humanoid/robotics sector forecasted by Elon Musk and others very large, if he's expecting millions of humanoids to be produced a year.
So my expectation is the current $10.65B MC would look very tiny in hindsight of LeaderDrive's market capture of the overall robotics market.
So I don't believe thesis like this should be measured in short term timeframes (or that people should actively trade names like these).
Moreso a long term investment idea about how this company could capture a material part of the overall humanoid market that exponentially grows over the next few years.
↗ Quoting @_memein
$688017$TSLA$VPG
I appreciate the objective coverage from 中国证券报 (China Securities Journal) on my LeaderDrive (688017) analysis!
On the article:
“A single tweet ignites the leading robotics stock, who exactly is the "White-Haired God of Stocks" Serenity?”
Supply chains are global, and my research shows that Chinese companies like 688017 hold a dominant position over low-cost, mass production as humanoids scale up.
Just a heads up: I do believe Leaderdrive’s position is very undervalued long term (next few years), if you weigh component costs vs. current customers vs. robotics TAM.
But I don’t control any near term volatility, especially with macro climates.
I’m flattered regardless by the institutional coverage of my track record of picking longs like $MRVL and my investment framework.
As well as the recent support from the Chinese community.
↗ Quoting @crypto_cat888
$688017$MRVL
On top: $NVDA CEO also called out Silicon Photonics (optical networking) with memory.
Stating that Nvidia would require “supply volumes beyond imagination”.
What a bullish read through on the SiPH supply chain from $SIVE (now upstream Nvidia ecosystem) to $SOI https://t.co/m6jub4nfzx https://t.co/VhGfnaTpzh
↗ Quoting @aleabitoreddit
$NVDA$SIVE$SOI
Oh look… $NVDA CEO warned memory shortage is expected to persist for many years, due to massive scaling demand of AI infrastructure.
With further announcements tomorrow.
$MU and $EWY (Samsung/SK Hynix) operating profit projections aren’t looking too crazy anymore? https://t.co/OvjyrifRtO https://t.co/ozmd2ILXCx
↗ Quoting @aleabitoreddit
$NVDA$MU$EWY
Not all dilution is bad and depends on what structure.
If you're doing a $600m ATM to build out laser fab capacity with $AAOI for $471m / month H1 2027 (at lower MC ranges), then that's accretive.
If you're diluting 15% for NASDAQ listing requirements with $SIVE, and using proceeds for M&A, that's accretive.
If you're diluting with $IQE and doing private placements with $MTSI to wipe off old toxic debt, that's accretive.
If you're diluting $6,000,000,000 with $IREN, and likely selling that into the open market on every rally off the backs of $SLNH / $BKKT shills where majority of those retail went to 0, then that's predatory.
$AAOI$SIVE$IQE$MTSI$IREN$SLNH$BKKT
Sure, #1 thing is toxic financing structure/float dynamics.
Best example is current Neoclouds landscape:
- $IREN is basically trash, since they have $6,000,000,000 ATMs and virtually infinite dilution, likely selling into every rally (structural overhang)
- While $NBIS is now YTD 153%+, from optimal structures (eg. $NVDA direct funding, mix of convertibles, etc.).
- On the other hand, $CRWV has endless debt interest given they took out high interest rate loans to finance GPUs.
It's extremely nuanced, but you need to take a look at the float dynamics.
If they're legitimately a good company, then it might be a good idea to go long after all the existing holders get diluted to oblivion.
But if you care about your equity appreciation, it's a good idea to stay far away from toxic financing structures or toxic overhang (eg. debt interest, that eats away at a company FCF long term)
With smaller companies, they have this all the time, like
$SLNH, where there's new $500m ATMs on a $250m MC.
Or like $BKKT where there's endless dilution to fund executive pay.
With these companies you're basically transferring your money over to the company while influencers talk about them. So those are red flags.
With many software names like $SNAP, they mask stock-based compensation with profitability. So while the company optically looks profitable, you'll likely see the value of your equity decrease due to dilution.
There's endless types of these share structures you need to look when screening ideas.
↗ Quoting @chuge857
$IREN$NBIS$NVDA$CRWV$SLNH$BKKT$SNAP
I think my personal style of investing is a bit different, just some reflection:
It's inherently discretionary, based on stuff markets don't know yet. And a culmination of life experiences?
If you look at $AXTI, $RPI, $SIVE, $IQE and others.
Lot of it is guessing on unstructured relationships then seeing if it's right or not down the line.
$RPI is the perfect example:
1. Nobody really thought of Raspberry Pis for AI growth. Mainly people bought one or two just for class + education + hobbyist.
2. After OpenClaw, just noticed all my friends and people just buying Apple Mac Minis / RPIs for AI applications.
3. Found validation of that trend online with lot of people sharing video tutorials on AI orchestration with RPI.
4. AI was their ideal perfect growth vector, did some modeling, and thought it was compelling.
Earnings comes out and I was right.
Everyone in media was calling it a meme stock because there's nothing online that shows revenue growth from AI (was 14% forecasted revenue growth, turned out to be 58%, my projection was around 55%).
So it was a mix of guessing next industry trend (AI using lightweight hardware instead of GPU clusters), real life trends, then revenue forecasting off my guess.
For stuff like $AXTI:
1. Everyone called it a joke when I bought at ~$12. LLMs would hallucinate and say "hyperscalers/govs would have known about this by now and fixed this vulnerability with InP substrates"
2. Or would conflate very nuanced parts of InP substrate stack, where there's multiple different chokepoints in upstream processing.
3. So part of this was just discretionary based on what I've seen over InP substrate breakdowns, industry trends, etc.
4. Then also guessing the major supercycle was photonics (this was before everyone caught onto $LITE, and others). Or before you saw the $141B TAM projections from GS.
5. AXT owned 40% of InP supply chain, without them the supply chain just gets cripped).
6. All the "analysts" were forecasting steady InP substrate growth, few hundred million TAM, etc. or export controls.
7. Everyone kept trying to say $AXTI was overvalued based on TAM estimates. But if it's a few hundred million TAM you just think that's a joke and go into game theory over allocations.
8. Then I just had to guess, how much would this be worth if it were a NAND style bottleneck, what MC could it reach based on control, how much would hyperscalers price it as, etc.
A lot of the current research outputs from Goldman Sachs, or earnings reports from the Epiwafer companies, were confirmed after I published my piece on AXT. If you did research back then, lot of the same material /framing wouldn't have come up.
With stuff like $XFAB as you're seeing now, a lot of it is just pure guessing:
1. Not really any CPO materials, how much their MTP process makes in revenue, etc. Everyone online keeps saying they're not a photonics player.
2. But if you go through ASE docs or Gov websites, they all kinda cite XFAB as a major emerging player here.
3. $NVDA also evaluating them right now (maybe it's successful who knows).
4. No clear revenue around this area because their main silicon photonics process is still precommercial, but if you guess it's trying to create a EU supply chain to compete with $TSEM, once pre-commercial shifts to commercial, maybe similar but less volume contracts?
5. Then just seeing updates over the next few months to see if anything confirms this thesis guess.
_
I think a lot of information discovery still can be done with LLMs I'm seeing online. But it's also really hard to make a bunch of unstructured inferences based on unrelated material or even just trends you're seeing in real life.
So probably better to just do what's standard, eg. do valuation forecasting based on current numbers
Stuff like $AAOI, if they're projecting $471m/M h1 2027 and you see MC at $12B, probably undervalued might be a good idea to go long for next years.
Stuff like Samsung Electronics is easier, see what people are modeling for operating profits for 2027, 2028 then just seeing if it's undervalued or not at current levels.
Maybe something harder is $JBL. I haven't really seen any great volume numbers around 1.6T LRO, but you can just make a guess on how popular that might be then project how that might impact current MCs.
Or picking just good names everyone kinda agrees like $TSM, $INTC, $MRVL is also solid.
So a lot of things is just building up your life skills then applying that to markets. I don't think it's that can be taught with courses and stuff.
Of course, much of what I'm doing is just high conviction inference based on unconnected parts. Could always be wrong.
↗ Quoting @KingCola88
$AXTI$RPI$SIVE$IQE$LITE$XFAB$NVDA$TSEM$AAOI$JBL$TSM$INTC$MRVL
@vipmoaa $TSM is probably one of the better names to do that for.
Probably better RoI than your depreciating car
$TSM
Just very helpful timelines reiterated around glass substrate (source: Trendforce):
- SKC Absolics (011790) H2 2026 (first mover x $AMAT) - $AMD customers
- Samsung electromechanics h2 2027 (009150) x Sumitomo Chem (4005) - Apple / $AVGO / hyperscalers
Idk about $INTC 2030 reports, we’ll see.
$TSM CoPoS was 2-3Y was correct though from recent TSM chairman comments. Innolux was interesting beneficiary. $SHMD should be too off TSM but financials were pretty toxic.
Same players should appear multiple times, eg innolux + SKC.
Also applies to $LPK and upstream equipment seller around these ramps.
$AMAT$AMD$AVGO$INTC$TSM$SHMD$LPK$011790$009150$4005
If you’re curious:
$4649 for 107,894,491 (100M+) impressions!
All of this is going to dog rescues, will be doing large donations later!
It’s ~$600 / dog rescued, so it scales proportionally with Serenity fan count!
I also believe in making all my profits off $SIVE to $AAOI with stocks in the market, not off followers.
Especially if I’m a good enough investor.
So never felt the need to have high paywalls or do paid ads. (I’d do this anyway even if it weren’t monetized).
I’m glad I can help things I care about just by posting ideas throughout the day for fun.
And I’ve seen a lot of followers recently donate to their local shelters in my name.
So genuinely thank you all for that, makes me happy.
$SIVE$AAOI
Apparently I’m all over Chinese news now?
I just published some research on LeaderDrive (688017) and their role in humanoid supply chains.
Looks like China’s robotics stock sector went up and 688017 hit 20% limit up?
I appreciate they called me “Overseas God”. https://t.co/mdASEvmsj0 https://t.co/FM6fLGGKjX
↗ Quoting @aleabitoreddit
$688017
Uhh, $XFAB de-risked foundry. Compelling upside from CPO if they make things work in H2 2027/2028?
I call this frontrunning institutions... since it's a massive guessing game few months ahead of normal repricing.
Cause it's a lot of customer/document mapping + timeline guessing without formal volume contracts in place.
But I think I'm right? We'll see.
$XFAB
Okay... just some more weekend shower thoughts about $XFAB.
I still feel like it could be the next $TSEM, just early stage at a $1.4B MC?
They kinda leapfrogged current gens (which $TSEM are getting volume from) to compete for H2 2027 CPO scale up inflection point ($ASX docs cite Xfab (aka. photonixFAB) as focusing on CPO)
By building out some black magic MTP (transfer printing) architecture for lasers w/ other stuff like TFLN.
Basically next-gen integration IP, they're still behind on yields, sure.
But $NVDA evaluating it for transceivers/switches to see if it can volume ramp. That $NOK sets the specifications/assembly for. (nvidia invested in nokia for this these switches/networking too btw).
And if their MTP supply chain works... (eg. with Smartphotonics providing lasers, EU players doing assembly).
It basically volume ramps with $NVDA just like why Nvidia signed long term agreements with $TSEM?
Downside risk?
Already below replacement book value, can always go lower yeah, but typically to a certain point.
Maybe more CHIPS act subsidies next few months from chips act 2. If it doesn't go well there's SiC (152% Y/Y Growth, 195% Y/Y SiC wafer shipment growth)/GaN power semi upside.
Europeans /LLMs will say "oh evaluations doesn't mean it's a future contract!".
This is kinda different since the European Union is behind this effort and $XFAB for soverign photonic supply chains.
Not your typical company + hyperscaler evaluation, since $NVDA wants to be nice to Europe's regulators. They'd prob be pissed if nvidia just stayed in US/Taiwan/China.
So if they can make this MTP black magic work with mass production, feels almost for sure nvidia/nokia volume ramp on some tiny $1.4B silicon photonics foundry or at least throw them a bone with smaller contracts.
In terms of timelines, maybe just a months early since it volume ramps H2 2027/H1 2028 (which happens to be in line with CPO scale up timelines)...
Or just unknown because they named their project something stupid like photonixfab?
Like XFAB Photonics would have been better? so institutions/screeners can connect the dots when looking at CPO silicon photonic foundry players?
Automotive should also coming out of a slump medium term, sped up by self-driving (TSM Chairmain comments yesterday said ai automotive was TSM's growth vector alongside robotics). So their core business also should pick up speed too medium term.
Obviously markets/europeans want a "Nvidia signs $2B+ contract, XFab volume ramping 2027!"
But by then it will be a $9B+ company and you miss out on all the upside. And especially since everyone analyst/institution is blind to volume expectations for these....
Normally don't invest in companies in evaluation stages, but this just seems very de-risked by EU sovereignty + Gov backing, and you have Nvidia + Nokia there for volumes if they can make the IP work.
I think markets are probably missing something here... there's almost 0 value being assigned to being CPO exposure in Europe as their long term upside.
$XFAB$TSEM$ASX$NVDA$NOK
@Jornka329996 > posts an idea about a 2027 silicon photonics foundry evaluted by $NOK and $NVDA last week
> sells on macro drop few days after
> complain
$NOK$NVDA

 @aleabitoreddit
Jun 08, 2026 · 10:22 ET
stock