Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
Came across an interesting report from SVRC Research called "State of Robotics 2026", published in April.
Which listed:
1. Figure AI
2. Agility Robotics $CCXI
3. Apptronik
4. $TSLA
5. Boston Dynamics
6. Physical Intelligence
7. 1X Technologies
8. $AMZN Robotics
9. Covariant
10. Skild AI
As the National Champions of the United States robotics program.
"The United States leads the world in where robotics is heading: Fundation models, OpenAI-style scaling laws applied to action, autonomous vehicles.
While losing the race on where robotics is shipping today."
Then it frames:
1. Rare Earths Exposure: from Neodymium for motors to samarium-cobalt for high-temp applications as a critical vulnerability.
2. Actuator dependency. Series elastic actuators, quasi-direct-drive motors, and precision reducers overwhelmingly sourced from Japan, Germany, and China
As one of the main vulnerabilities alongside Manufacturing velocity/data collection cost/regulations. Then their take was:
"With at least six well-funded US humanoid companies competing for a market still in early formation, we expect at least two significant consolidation events (acquisition or merger) in 2027".
With Logistics / E-commerce (like $AMZN / $FDX) and Automotive from $GM to $FORD as being the immediate top use cases for deployment.
I think it's just interesting to see a lot of my points I've been talking about reiterated by research firms. Regardless, I do think it's going to be a major frontier race between the US and China.
Agility Robotics (which I own), Tesla, Figure, and Apptronik as leaders representing the USA. Competing against Unitree, AGIbot, Ubtech, and others in China.
$TSLA$AMZN$FDX$GM$F$CCXI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMZNlong |
+0.6% | +1.8% | +11.9% | — | +2.7% |
| $CCXIlong |
-9.8% | -15.0% | -27.4% | — | -39.3% |
| $Flong |
+3.5% | +1.9% | +9.9% | — | -8.8% |
| $FDXlong |
-1.0% | -0.7% | -1.8% | — | -8.6% |
| $GMlong |
+2.4% | +0.9% | +16.9% | — | +1.5% |
| $TSLAlong |
+6.7% | +3.3% | -20.9% | — | -9.9% |
No, it’s the same if not higher. Markets are closed and if there’s no new developments, then I have nothing new to add.
$SIVE is personally one of my largest holdings and I’ve posted all my thoughts on their hyperscaler supplier relationships. So I’m just waiting for volume ramps and company execution and ignoring a lot of noise.
The convertible notes is not new information and was likely priced in for awhile. Having it executed now is not a positive thing like others are framing, since Bootstrap Europe is a venture debt fund.
There’s likely instituonal swaps happening given oversubscribed instituonal demand around these levels. $140m is not a big amount in terms of institutional flows.
$SIVE
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $SIVElong |
| | | | |
So positive readthrough on the upstream glass substrate supply chain:
- Sumitomo Chemical and Samsung Electro-Mechanics formally establish JV in Korea within the year to handle the glass core substrate business (GlaSSEM).
Main thing was timeline/funding was finalized: "full scale commercialization targeted H2 2027" for the Samsung/Dongwoo JV / KRW 482.1B planned capital.
Think the "full scale commercialization" is the word to highlight, since that would imply timeline moving faster than expected than starting ramp or early production H2 2027.
So... TGV/LIDE with $LPK (that I own)/E&R and Onto in terms of yields are just some examples of possible sector beneficiaries.
Since companies like LPK stated in the past: “80% of customers among major global players have selected LPKF equipment” and targeted "70% of LIDE market share target for TGV in the glass-core ramp".
These players also typically have revenue pulled forward, since equipment orders during capex cycle hit before actual ramp.
Regardless, just an update on developments.
$LPK$ONTO
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $ONTOlong |
-1.2% | +3.1% | -15.9% | — | +0.1% |
| $LPKlong |
| | | | |
@zhouyuan888 I personally heavily added to some of my optical positions today.
Immaterial selloff off false meta capex cuts and false CPO delays.
I can’t give advice on what others should do though.
$META
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $METAlong |
+4.7% | +13.6% | +69.8% | — | +75.1% |
@ontrialperiod when global and US markets crash off misinformation and out of context quotes from $META. I probably want to clear that up?
That thing said, $AAOI, $SIVE, and $CCXI do make up large concentration in my portfolio.
$META$AAOI$SIVE$CCXI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+2.0% | +1.0% | -22.0% | — | -17.9% |
| $CCXIlong |
-9.8% | -15.0% | -27.4% | — | -39.3% |
| $METAlong |
+4.7% | +13.6% | +69.8% | — | +75.1% |
| $SIVElong |
| | | | |
@SUOHA_AI I remember first investing in $RKLB back at $15 or so.
It just find it rare to get exposure to a downstream + frontier sector leader. So I’m personally not missing this chance again with $CCXI.
$RKLB$CCXI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $CCXIlong |
-9.8% | -15.0% | -27.4% | — | -39.3% |
| $RKLBlong |
-7.3% | -17.8% | -35.3% | — | -30.6% |
Nobody should care about TA charts since people just made up squiggly lines trying to convince others to sell.
$SIVE just raised an emergency $70M for mass production likely for allocation from fabs.
With $JBL, $POET, $AEVA, and others volume ramping near term.
Then $GFS, Ayar, and many other players are volume ramping later in 2027.
Sivers also confirmed intent to complete NASDAQ Listing in the next few quarters.
It's probably my highest conviction photonics long, everything seems to be coming into place.
$SIVE$JBL$POET$AEVA$GFS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AEVAlong |
+0.9% | -8.1% | -26.9% | — | -41.4% |
| $GFSlong |
-1.3% | -0.2% | -28.4% | — | -31.2% |
| $JBLlong |
-0.9% | -2.6% | -7.7% | — | -15.9% |
| $POETlong |
+2.2% | -0.7% | -20.2% | — | -14.6% |
| $SIVElong |
| | | | |
Photonics is backed by actual revenue numbers and it's an architectural shift championed by $NVDA.
Quantum barely has any revenue.
$LITE is completely sold out for the next 2 years (per $POET AGM) likely starting into 2029. Lumentum is so strained that they buy CW lasers off competitors (earnings transcript)
$COHR is bottlenecked, so they buy EML off Lumentum.
Then, $AAOI is coming in with Made-in-America independent CW capacity, are projecting $1.4B/quarterly revenue ending H1 2027 of a stupid $9.3B MC today.
So all the CW capacity from independent players who have it now like $AAOI or $SIVE are likely to become scarce resources.
Many other hyperscalers have already started LTA discussions (per Trendforce). And players like $AMD are currently talking with players such as $AAOI (Rosenblatt channel checks).
Thematically, next 2 years is 9x TAM to US$154B per GS reports, especially with 16x/45x dollar content increase in scale out/scale up.
Then there's the overall thematic AI drop from $META, which is widely misunderstood because people conflate what "excess capacity" means. And as UBS mentioned, Meta planning a cloud offering is NOT NEW NEWS.
Bloomberg just has a tendency to publish information that causes doom drops across the semi sector like Nvidia export controls a few months back.
But I'm familiar with what I'm holding so I'm confident in these numbers playing out.
Especially when all the major players are sold out, the fundamentals catch up eventually.
↗ Quoting @walker119298
$NVDA$LITE$POET$COHR$AAOI$SIVE$AMD$META
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+2.0% | +1.0% | -22.0% | — | -17.9% |
| $AMDlong |
+6.6% | +5.6% | -8.0% | — | +18.1% |
| $COHRlong |
+0.7% | -1.8% | -21.1% | — | -13.7% |
| $LITElong |
+0.4% | +7.9% | -2.0% | — | +33.2% |
| $METAlong |
+1.2% | +17.6% | +101.5% | — | +77.2% |
| $NVDAlong |
+0.4% | +4.1% | +3.0% | — | +17.4% |
| $POETlong |
+2.2% | -0.7% | -20.2% | — | -14.6% |
| $SIVElong |
| | | | |
I’m personally long $CCXI and have highest concentration in Agility Robotics (NFA). It’s currently around a ~$4.9B valuation.
Figure’s last round was $39B last year, and that was before the increasing interest in humanoids/robotics this year.
Then a large part of $TSLA $1T+ valuations come from humanoids.
I like companies like LeaderDrive… but usually the downstream players capture the most value in the end.
And I find it rare to see one that has public exposure early on.
$CCXI$TSLA
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $CCXIlong |
-9.8% | -15.0% | -27.4% | — | -39.3% |
| $TSLAlong |
+6.7% | +3.3% | -20.9% | — | -9.9% |
Where did I ever say that? Majority of my portfolio is concentrated in photonics with names like $SIVE and $AAOI.
However, I’m allowed to talk about other exciting developments as well… Such as the first listed US humanoid player?
I still think CPO/optics has the fastest TAM ramp out of any industry, just a bit early since I’m projecting revenue inflection really hits ~H2 2027.
I’m personally down a lot past few weeks, but I’m convinced my thesis with laser chokepoints and others plays out.
$SIVE$AAOI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-13.0% | -17.7% | -32.1% | — | -28.6% |
| $SIVElong |
| | | | |
Just dropping these 3 slides from Agility Robotics ( $CCXI ) presentations.
For the US robotic program doomposters:
1. “75% of parts” - sourced from the USA
2. Just eyeballing the graph, looks like <$30k BOM mass production.
People were just looking at the ~$145K cost.
3. 10,000 RoboFab capacity, and they build in Salem/Pittsburgh/Fremont (USA).
So looks like majority US supply chains with targets of <$30K mass production
It does help they’re backed by $AMZN / SoftBank / Foxconn / $NVDA as investors to get this done.
Just personal thoughts as a shareholder in $CCXI (NFA):
My personal biggest fear were US humanoid leaders like $TSLA were just building out their entire supply chains in China.
So US robotics could just be export controlled/halted down the road.
eg. South China Morning Post: ‘Optimus chain’: Chinese suppliers form the backbone of Tesla’s humanoid robot initiative and engaged with hundreds of Chinese component suppliers.
And that Western companies are not able to lower costs to a competitive level + are forced to use Chinese components.
I'm still not sure how they're going to do it but if Agility can achieve those mass production targets with that BOM cost in the USA/West.
It would be a great validation for Made in America US robotics programs.
IMO the top 5 US humanoid programs right now in terms of commercialization potential are:
1. Tesla Optimus
2. Figure
3. Agility Robotics
4. Boston Dynamics (yeah KR parent)
5. Apptronik
Tesla is a $1T+ company. Figure is private and valued around ~$39B. Owning Boston Dynamics through Hyundai is a bit messy.
And I’d prefer not to invest in adversarial programs just as a personal preference.
So I’ve been personally excited for Agility to be listed as early as September.
$CCXI$AMZN$NVDA$TSLA
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMZNlong |
+0.4% | +0.8% | +12.4% | — | +3.1% |
| $CCXIlong |
+12.0% | -10.6% | -18.8% | — | -32.0% |
| $NVDAlong |
-1.4% | +3.3% | +1.6% | — | +15.7% |
| $TSLAlong |
-7.5% | -7.3% | -26.8% | — | -16.6% |
@alGix0 I’m not concerned with short term volatility, which is expected with high-beta photonics and current macro.
I’m long on $SIVE to see my thesis play out with laser volume ramp.
Dilution could be a short term factor, but I see the development as positive long term
$SIVE
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $SIVElong |
| | | | |
Yep! Agility Robotics is currently my favorite humanoid/robotics position.
They're set to be listed on NASDAQ via $CCXI as early as September (per Digitimes).
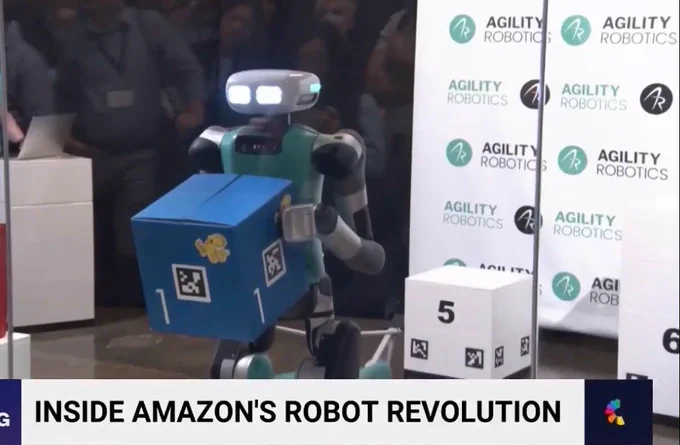
Just for informational purposes: Their V4 humanoid robot is already operating in sites like Amazon. And have V5 slated for mass production next year (they have a 10,000+ /year capacity).
Investors include Foxconn, $NVDA, $AMZN, Softbank, and now Serenity.
I've been personally waiting for humanoid exposure for awhile (Agility is set to be the first US pure-play listed one) to the point I was actually planning on investing in Unitree's IPO.
But I'm glad now I personally have a compelling alternative now since I prefer to invest capital to build up Made in America supply chains (75% of their components are US-sourced from investor desks).
There are risks assigned to SPACs such as listing delays, or cancellation. But excited to see what happens next with developments.
I do hope this encourages other frontier companies to go public early on.
↗ Quoting @suoha_ai
$CCXI$NVDA$AMZN
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMZNlong |
+1.4% | +3.2% | -1.2% | — | +4.5% |
| $CCXIlong |
-2.2% | -9.1% | -19.8% | — | -33.5% |
| $NVDAlong |
-1.3% | -1.6% | -2.5% | — | +14.3% |
@gurukid5995 Markets tend to rotate from bottleneck to bottleneck.
Memory from $SNDK to $MU was the market's main focus this month, while optical names like $AAOI corrected.
I think we'll see a rotation back into photonics eventually, it's personally my highest concentration theme.
$SNDK$MU$AAOI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-1.3% | -17.8% | -49.0% | — | -33.9% |
| $MUlong |
+0.8% | -14.0% | -35.5% | — | -6.7% |
| $SNDKlong |
+10.9% | -14.9% | -50.5% | — | -15.1% |
For robotics companies, I have a favorable view on Unitree and Agility Robotics, two humanoid players.
And I have largest concentration in Agility Robotics, since I personally prefer US humanoid players.
For upstream component exposure, I currently own:
- Harmonic Drive (6324) given high content BOM on things like harmonic reduction gear.
- Vishay Precision for sensors and a possible candidate for Telsa Optimus.
LeaderDrive (688017) and Schaeffler I have favorable views on but don't own personally.
Many of the other AI DC players, I have indirect exposure to robotics like memory.
Don't recommend anyone to copy, just sharing personal positions/thoughts.
Humanoid sector is large, and as seen with Goldman Sachs report that "Korean companies will command a 30% direct and indirect share of global humanoid robot production".
Lot of players out there globally. This was an older report but just linking it again since you see all of them pop up in GS institutional reports + what they cover.
Agility Robotics is my personal favorite as of now.
↗ Quoting @pdrakoul
$6324$VPG$TSLA$688017$SHA$GS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $GSlong |
-0.9% | +3.4% | -3.9% | — | -11.3% |
| $TSLAlong |
+2.1% | +1.9% | -27.6% | — | -13.9% |
| $VPGlong |
+5.5% | -13.4% | -42.8% | — | -49.5% |
| $6324long |
| | | | |
| $688017long |
| | | | |
| $SHAlong |
| | | | |
pls don’t blindly follow along, esp. since I actively manage my own positions!
$CBRS is just a cautionary position for me right now.
Cause things evolve every month in the AI space (eg. Custom jalapeño chips, maybe OpenAI has troubles, rate hikes), etc.
But if it’s compelling to you, you do you.
$CBRS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $CBRSlong |
+19.0% | +12.8% | +9.7% | — | -2.1% |
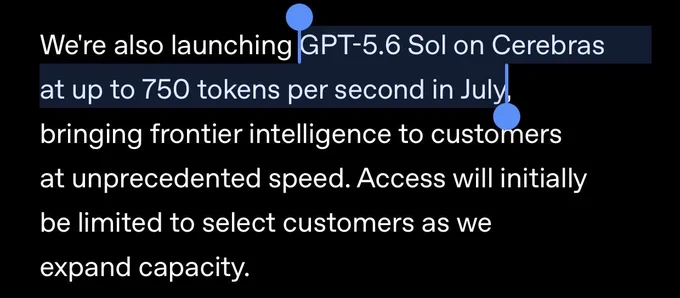
Kinda nutty OpenAI’s is launching its heavyweight 5.6 Sol frontier model on $CBRS.
At up to 750 tokens/sec, which is obscene performance.
American inference go brrr.
I actually picked up starter positions on Cerebras for the first time in the ~170s (below $185 IPO price) after seeing this news yesterday.
Feels like validation of its tech. IMO a bit overvalued compared to profitable companies like $JBL at the same valuation.
But there’s likely premiums for OpenAI exposure, as long as they stay the leader.
↗ Quoting @aleabitoreddit
$CBRS$JBL
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $CBRSlong |
+19.0% | +12.8% | +9.7% | — | -2.1% |
| $JBLlong |
+4.2% | -4.8% | -12.8% | — | -20.0% |
You've been supporting me from the very start, thank you so much!
I still remember your first translation post helped me get popular.
Before I was just able to wait for my thesis to play out like $NBIS even in the drops, since I didn't have so many followers.
Now everyone's monitoring day-to-day price volatility and commenting about it so it's harder to ignore.
$NBIS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $NBISlong |
+8.7% | -10.3% | -21.9% | — | -1.8% |
OFC I'm aware. But I'm personally sleeping comfortably since I have conviction in my hyperscaler mapping research with $SIVE.
And yes, I still have my million+ share position.
Not sure if people realize this: but I'm only here to share my thoughts/ideas.
I don't control market volatility, what decisions you all make, or how markets react to new information synthesis.
It's much safer for analysts to just reactively tag along Morgan Stanley/JP Morgan/Goldman Sachs research whenever it's created and just summarize.
Rather than coming up with new ideas from OSINT mapping and waiting them get validated.
Because when you discover a new angle:
Everyone keeps heatedly debating topics of 4-6 inch InP fabs, employee count, who their hyperscaler customers are, volume ramp timelines, etc to try and play devils advocate with a thesis.
Then actively monitoring every single 5-20% price movement.
I'm forced to stay on this topic more since it's less validated + there's always heated discussions. Just like $EWY in Feb, which I did memory projections on + Helium/LNG/Oil analysis.
But months later everyone sees memory looks structural with Micron's 16+ LTAs and LNG isn't taking down SK Hynix margins.
Or $NBIS from last year in terms of sum-of-parts / dilution structures vs $IREN.
And now it's close to ATHs and listed on $QQQ.
I'm personally just waiting Sivers to volume ramp in 2027 + listing on NASDAQ to support their M&A efforts.
So they can walk down the same path as $LITE when they scaled from $3B to $60B+.
↗ Quoting @Ecom_Venture2
$SIVE$EWY$NBIS$IREN$QQQ$LITE$MU
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $EWYlong |
+0.1% | -8.7% | -17.4% | — | -7.3% |
| $IRENlong |
-2.8% | -17.8% | -21.5% | — | -13.4% |
| $LITElong |
+4.2% | -10.9% | -6.6% | — | +18.8% |
| $MUlong |
+1.1% | -13.8% | -18.7% | — | -5.6% |
| $NBISlong |
+8.7% | -10.3% | -21.9% | — | -1.8% |
| $QQQlong |
+2.5% | +0.9% | -3.2% | — | +4.8% |
| $SIVElong |
| | | | |
FYI, I posted ideas about $AXTI at $15, $AAOI at $30, $TSEM at $115, $LITE $300, $MU $300, $SNDK $400, $EWY $110, $SIVE $4.
$IQE $13, $SOI $44 and so on.
So when they finally have a massive correction due to macro drop the ideas are wrong? And most are still up a few hundred percent.
TW CPO names are just really early and I’m down a lot on those but I expect them to recover in due time.
$AXTI$AAOI$TSEM$LITE$MU$SNDK$EWY$SIVE$IQE$SOI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-2.1% | -12.7% | -27.7% | — | -28.4% |
| $AXTIlong |
+1.6% | -18.0% | -31.6% | — | +12.1% |
| $EWYlong |
-3.8% | -12.1% | -20.5% | — | -10.8% |
| $LITElong |
-5.2% | -15.5% | -11.5% | — | +12.6% |
| $MUlong |
-6.7% | -19.6% | -24.1% | — | -11.9% |
| $SNDKlong |
-10.5% | -25.3% | -38.5% | — | -25.5% |
| $TSEMlong |
-7.4% | -18.8% | -13.5% | — | -15.8% |
| $IQElong |
| | | | |
| $SIVElong |
| | | | |
| $SOIlong |
| | | | |
Think so. But in the meantime, I call my strategy: Diversified Losses.
With $AXTI, $SOI, $AAOI, and many others.
Had a massive drawdown recently,
CPO exposure was hit the hardest (Foci, Msscorp, etc) and adjacent names, feels bad.
Probably lesson personally, I had too much concentration in photonics vs. memory/other sectors without weighting/hedging properly.
With Soitec, there's been a few negative institutional reports that I'd disagree with.
Think AXT was hit harder in specific just because of float expansion/dilution concerns. AAOI, probably just brought down with the theme.
I can't give advice on buying, so completely up to you to make for cost averaging or entering positions.
But I do think we're still early in the Supercycle with photonics, there's bound to be corrections/crashes along the way up.
If my personal thesis is correct though, many of these names will have a major inflection point in midway through 2027 scaling up to 2028.
Markets don't typically wait to price things in advance, but some ideas might be a tad early or in the buildout given it's H2 2026 now.
Which is why it's important to build your own conviction.
↗ Quoting @tsazeng
$AXTI$SOI$AAOI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-5.7% | -5.4% | -31.9% | — | -32.5% |
| $AXTIlong |
-1.5% | -7.3% | -32.7% | — | +10.4% |
| $SOIlong |
| | | | |
Fun new information discovery from Poet OSINT community:
Seems likely that $POET / $SIVE are going to power a Top-3 hyperscaler (either Amazon, Microsoft, Google).
Given a Linkedin update from Ankur Singla (CEO of Lumilens).
Who stated their customer is one of the top 3 hyperscalers with their post focusing on CPO/NPO.
With that clue, seems more likely the Sivers CW DFB light source path over other EML suppliers given it's CPO Scale Out/NPO.
If you don't remember, Sivers is the laser supplier to Poet. And Poet has purchase agreements with Lumilens.
Always fun to find major potential breadcrumbs in the wild before they're officially confirmed. (Disclosure, long Sive)
$POET$SIVE$AMZN$MSFT$GOOGL
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMZNlong |
-3.1% | +3.2% | -0.9% | — | +6.4% |
| $GOOGLlong |
-0.5% | +4.6% | -7.4% | — | -0.3% |
| $MSFTlong |
-3.5% | +5.1% | +4.4% | — | +40.6% |
| $POETlong |
-5.0% | -9.0% | -35.4% | — | -29.8% |
| $SIVElong |
| | | | |
@SMike1271547 I actually just added on $AAOI.
Was talking about in general since everything dropped across the board, not specific names MB.
$AAOI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-0.3% | +0.5% | -24.0% | — | -32.7% |
Dip looks like a clear buying opportunity for me personally from $MU, $INTC, to $TSM.
Since we got a massive drop off BS narratives like 3 rate hikes off no newly material macroeconomic data (which comes out Thursday).
If institutions really believed 3 rate hike sellside garbage that BofA put out:
They would profit off it with CME/prediction markets.
Which are still projecting 74% no rate hike in July. But they don't.
So they're feeding retail investors garbage.
↗ Quoting @Bulls_Run
$MU$INTC$TSM$BAC
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $BAClong |
-0.3% | -1.6% | +5.8% | — | -5.5% |
| $INTClong |
-0.5% | +5.6% | -24.2% | — | -9.1% |
| $MUlong |
-0.3% | +9.7% | -5.8% | — | +1.6% |
| $TSMlong |
+1.0% | +9.4% | -4.8% | — | +4.8% |
IMO photonics theme + CW laser chokepoint is goated.
It's legit like markets have short term memory loss and forgot how $LITE went from $3B -> $65B+ from 2024 to now.
Because $NVDA caused EML bottlenecks, and forced architectural changes.
We're literally seeing the same thing today with CW lasers + 1.6T/CPO shifts with Nvidia signing LTAs everywhere.
Now, $AMD + other CSPs are hunting for remaining scraps with large LTAs for CW lasers + optical components.
GS Research's ~9-10x $154B optical TAM in 2028 and near $0 -> $91B CPO TAM in just 2 1/2 years.
Don't just magically disappear from a month of trading volatility.
$AAOI sitting at ~$13B, $SIVE sitting at ~$3B, and other CW laser players look strategically very valuable.
And next year I think we'll look back and say "Why didn't I learn my lesson the first time with EML from Nvidia and pick up CW laser adjacent names!"
Then there's likely gonna be some new mini trend 1-2 years from now like microled or quantum dot and we're gonna see the same thing repeat.
Think Sumitomo's projections with CW laser share + silicon photonics being majority / dominant architecture should be correct.
I'm personally just focusing on that bottleneck as you've seen with $SOI, $TSEM, $SIVE, and others.
↗ Quoting @veggiepoultry
$LITE$NVDA$AMD$AAOI$SIVE$SOI$TSEM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-13.9% | -12.3% | -35.5% | — | -42.0% |
| $AMDlong |
-5.8% | -2.2% | +0.1% | — | +10.9% |
| $LITElong |
-7.4% | -4.8% | -7.2% | — | +8.5% |
| $NVDAlong |
-4.1% | -6.6% | +1.6% | — | +9.6% |
| $TSEMlong |
-10.8% | -19.3% | -21.2% | — | -28.3% |
| $SIVElong |
| | | | |
| $SOIlong |
| | | | |

 @aleabitoreddit
Jul 05, 2026 · 16:32 ET
stock
1st mention
trade
position