Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
I remain convinced nobody knows how to pronounce or talk about $AAOI in real life.
It’s one letter too long to say $TSM or $AMD.
And nobody ever says to a friend“Wow, I like applied optoelectronics!”
$AAOI$TSM$AMD
$AAOI is an end of H1 2027 volume ramp player for me, since around then is when they hit inflection point of $471m/month revenue projections.
Recent drafted ban on new optical transceivers coming from Innolight and others, increase weight on players like AAOI, $SIVE / $JBL, $LITE, $COHR for their 1.6T+ programs as well. Especially if finalized in 2026.
Since there's likely going to be price hikes, and more demand concentration over capacity from the select few Western players.
$AAOI$SIVE$JBL$LITE$COHR
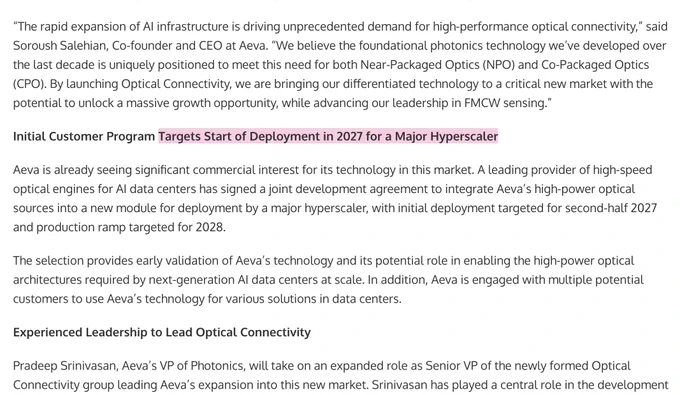
The unexpected thing of the week... Was $AEVA becoming a CPO/NPO optical source player.
For background: $SIVE is viewed as the high confidence CW DFB laser supplier to Aeva (which is known for lidar).
Today, Aeva reacted with +18.26% AH on news that they signed a JDA with an optical engine player for deployment at a major hyperscaler in H2 2027, production ramp 2028.
"Optical Connectivity will leverage that foundation along with Aeva’s EXISTING high-volume manufacturing and foundry supply chain" for:
- ELSFP (similar to O-Net/Enablence + $SIVE), with Sivers as the likely CW laser + potential amplifier supplier
- On-chip integrated light source (likely $SIVE DFB + Aeva PIC on the architecture/integration side)
TLDR: New TAM and a hyperscaler programs for Aeva for CPO/NPO, positive read through for upstream suppliers like $SIVE.
↗ Quoting @RobertFritzson
$AEVA$SIVE
Funniest callout of the year from $VIAV on CPO timelines:
"Well, there's been a lot of industry talk [about delays], like, 'Oh, because the yield is going to be slower.'
That's all nonsense. CPO and all that thing is moving forward"
They stated that Yes there's always issues, but the process is being improved and things are getting better.
To follow up on that, the CEO stated:
- Viavi has POs for CPO-testing activity
- “We’re already getting [CPO revenue] this quarter, and probably in December it will start accelerating.”
On a side note, they also stated, 1.6T is "ramping very quickly", should reach parity with 800g next year, and signaled longer tail for 800g demand.
TLDR: Seeing CPO test revenues hit for $VIAV to $FORM around now. Nvidia also stated switch-side CPO for scale out and scale across has entered mass production earlier.
As for scale up timelines, early production should be H2 2027 for some players, with other CPO players Ayar stating 2028 is the volume inflection period.
Basically, all the timelines seem to be the same as before and revenue is starting to hit testing players first.
$VIAV$FORM$NVDA
@zcelestialbaby It's material to $RKLB, since it will be validating their new reusable medium lift rocket Neutron as well as their newer satellite platform.
I don't really post much updates on Rocketlab (yes I own Rocketlab). unless it's something that catches my eye.
$RKLB
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $RKLBlong |
+0.5% | +7.4% | -14.3% | — | -6.4% |
$RKLB has been awarded a $397M contract by the US Space Force.
To build out Flatellite satellites and launch them on their Medium Lift rocket, Neutron.
$RKLB
@R_o_LwSzr $AXTI is too far upstream. I definitely do not see them going to be export controlled by the US.
But they could be used in retaliation, we’ll see.
$AXTI
@NoKorea_YesUSA OE Solutions is developing vertically integrated 1.6T optical transceivers with in-house EML/CW.
But its early stage compared to the others.
A very material catalyst came about for Western supply chains from $AAOI, $SIVE / Jabil, to $LITE and Coherent:
The Trump administration is drafting a ban of new Chinese optical transceivers and DC devices.
Which would likely hit China’s Innolight, Eoptolink, and other Chinese optical interconnect supply chains.
"The agency would ban all imports of new transceiver models and then exempt many non-Chinese suppliers from the restrictions"
We'll likely see a larger bifurcation of supply chains with even greater importance put on Western players.
$AAOI$SIVE$JBL$LITE$COHR
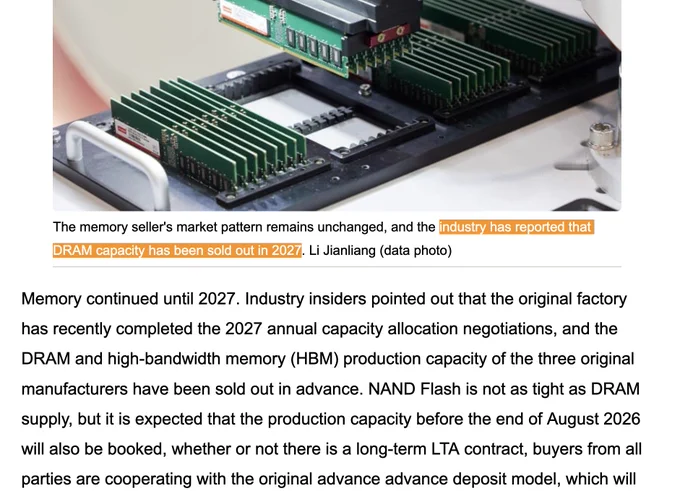
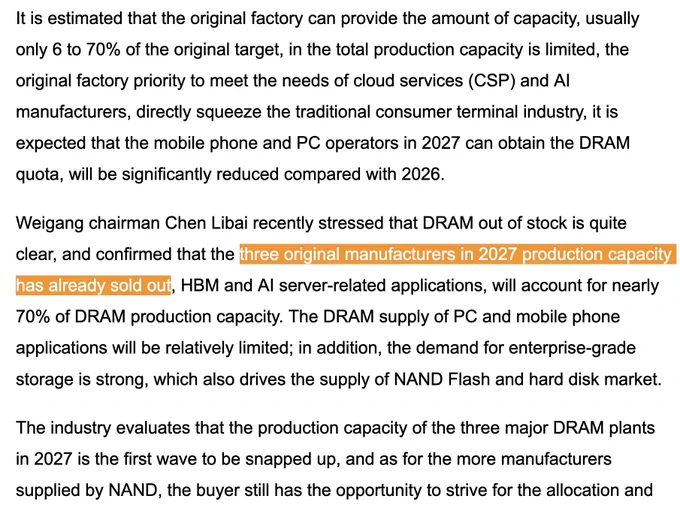
SK Hynix, $MU , and Samsung have sold out of 2027 capacity for DRAM/HBM.
$SNDK, Samsung, Micron current annual NAND capacity has been sold out, with Kioxia and SK Hynix expected to finalize allocations by August 2026.
- Customers are being allocated only 60–70% of the volumes they initially requested
- industry insiders pointed out that 2027 will enter the most severe moment of memory shortage
- Allocation amounts are mostly decided, but final shipment pricing will be determined closer to delivery
Source: Digitimes, citing industry sources.
Hard to see those memory "oversupply" claims in early-mid 2027 when they're all sold out of capacity already.
$MU$SNDK
$LITE CEO Michael Hurlston at the RAISE Summit warned that the supply gap for InP lasers for AI DCs:
Is facing a more severe supply chain crisis than memory.
And with Lumentum's 5 InP fabs, shipments would be more than 30%+ below customer demand.
This is especially visible with EMLs today but is already expanding to CW, especially as CPO ramps.
I've always been a fan of the laser chokepoint + bottleneck from $AAOI, $SIVE, $LITE, and $COHR. And glad this thesis is starting to see validation.
$LITE$AAOI$SIVE$COHR
@optionsreaper His ideas would have played out anyway with $SNDK or $BE even without anyone from retail knowing he existed.
Retail wouldn't have changed a thing with NAND shortages or hyperscaler demand for Bloom.
Downplaying that to just retail copying him is also terrible.
$SNDK$BE
The media framing and X reactions around Leopold are egregious.
Framing his successful multi-year thesis from $SNDK to $BE as a "collapse" or "failure".
After July's surprising crash, then personally attacking him on top is just pathetic to witness.
It's almost like everyone is cheering for the downfall of others.
Yes, July's crash exposed problems with SA’s leverage, liquidity management, and hedging.
But his current YTD performance remains +80%, ranking among the best performing hedge funds. And he still has public equities after all this (just removed leverage).
I think he's doing something unique while being successful at it. And this draws the envy of others.
$SNDK$BE
Thesis is more for CPO scale up expecting complexity making make MSSCorp a monopoly-type chokepoint over inspection yields (they were claiming 90% market share target). Although they can be used for other segments.
$FORM ramped a lot earlier, so maybe will revenue would start to appear in next earnings?
Regardless, Asian names sold off extremely hard on CPO timeline delay report that I found to be incorrect with my channel checks at the $AMD conference.
Don't think my views have changed, it's moreso waiting for 2027.
Names with more confirmed scale-out switch volumes like Shunsin + laser names like $AAOI / $SIVE ramp a lot earlier. It's just timelines in my view and when markets want to price that in.
$FORM$AMD$AAOI$SIVE
Situational Awareness / Leopold was completely right in terms of US shifting more toward inference + large energy demand.
I had a similar thesis with Neoclouds like $IREN, $NBIS, $CIFR, $WULF, and others last year in 2025.
But shifted more towards upstream bottlenecks + networking personally. It's just a little unfortunate the fund couldn't fully survive the drawdown.
We did overlap in memory concentration but energy/grid from $BE, $TE, or neoclouds like $SHAZ / $IREN but I'd expect them to outperform given compute/capacity shortages.
$IREN$NBIS$CIFR$WULF$BE$TE$SHAZ
Hmm, I personally added $AMKR in the $40's since I thought it was surprising it dropped that much after ER, even after $NVDA $1.5B deal + $TSM 10Y agreement.
It's more of a 2028 name though, though they have separate ramps in 2027.
- Did some cost averaging on names like Foci on drop to 400 (leading FAU supplier to $TSM COUPE + $NVDA, COUPE shows signs of ramp now from other ERs like $FORM). Added some $XFAB too after earnings since they verified CPO + 800V exposure, might be a bit of waiting though.
Added $LPK on the 13 EU doomdrop, GCS isn't going anywhere, think volume ramp just got delayed a quarter because of Absolics delay and I'm fine waiting 3 months. CoPoS, Samsung, and others should drive demand more in 2027.
And added OE Solutions on drop to ~14,000 KRW, thought it was strange Korea's leading EML company with independent InP fabs was only worth ~$110M MC.
- Names like Win Semi + others are really really compelling to me but just dont have enough capital to add sadly without going on heavy margin.
Probably want to scale into $SIVE and $AAOI more since those are my two favorites.
And looking at $CCXI opportunities given Unitree IPO is around 3 weeks, that listing should boost humanoid/robotics sector a bit similar to the $SPCX halo effect.
TLDR: Just moving capital around, my own personal risk management. Same names as before.
$AMKR$NVDA$TSM$FORM$XFAB$LPK$SIVE$AAOI$CCXI$SPCX
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+16.8% | +43.8% | +12.6% | — | +5.2% |
| $AMKRlong |
+1.9% | +10.8% | -4.0% | — | +5.2% |
| $CCXIlong |
+11.6% | +19.9% | +0.8% | — | -16.3% |
| $FORMlong |
+2.4% | +10.5% | -4.2% | — | +40.7% |
| $NVDAlong |
+2.9% | +11.6% | +8.4% | — | +13.9% |
| $SPCXlong |
+5.7% | +22.8% | +30.6% | — | +39.2% |
| $TSMlong |
+0.5% | +3.9% | +3.3% | — | +13.1% |
| $LPKlong |
| | | | |
| $SIVElong |
| | | | |
| $XFABlong |
| | | | |
As a earnings recap: $AMZN, $META, $GOOGL, and $MSFT guided a 2026 combined capex forecast to ~$720-$745 Billion.
Up from $695-$725B Billion previously.
Amazon: $220B
Google: $195B-$205B
Meta: $130B-$145B
Microsoft: $175B
We've already seen significant deleveraging and retail/institutional margin liquidations (maybe it continues for more time, who knows).
But medium-long term, I'm not quite sure how anyone can be bearish the upstream semis or neoclouds.
Given each hyperscaler has flagged either compute shortages, rising cloud demand + pricing power, or increased spending for chips/networking.
My "bottleneck" thesis with many of these upstream semi supply chains is that when trillions in capital flows into things from InP substrates or memory (which were both treated as cheap commodities) or even energy.
Lot of these current AI names that were treated as useless before in telecom cycles or even toilet sellers.
Gets rerated when their inflection period hits and capex flows into their balance sheets.
As seen with $NVDA GPUs past few years, memory this year, CPUs/MLCCs next few years, CPO in 2027, Glass Substrates in 2027, 800V in 2027, and so on.
$AMZN$META$GOOGL$MSFT$NVDA
@SammyJ51 Kenneth will need to do some magic to liquidate me of my 1 $IREN share.
$IREN
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $IRENlong |
+8.0% | +12.0% | -3.7% | — | +11.1% |
@amitisinvesting Agreed on $RDDT, the -22.61% reaction seems overblown to me off those earnings/projections. Their monetization strategy seem to be working wonders.
AI licensing seems inevitable as well given your frontier labs always want more data. Was one of the more confusing selloffs.
$RDDT
@tax_evader666 US DAU*, they beat heavily on financial metrics and raised forward guidance above street expectations.
But people like to make up some narrative every time something drops.
-22.6% selloff on $RDDT is very surprising to me.
$RDDT
$RDDT ER in a nutshell:
Revenue: $804.9M vs. $730.4M (expected).
EPS: $1.25 vs. ~$0.95.
Net income: $252.8M vs. $196.5M
Q3 guidance:
Revenue: $860–870M vs. 829.1M
Adjusted EBITDA: $385-395M vs. $369M
Blowout financials, market always like to explain the drop 22.6% off some new BS narrative.
Last quarter: "AI will disrupt Reddit causing revenue loss!"
This quarter: "See, DAU fell .6%!" (proceeds to ignore any revenue/profitability growth)
$RDDT
Just a TLDR of this week:
Media: Hyperscalers overbuilt and are selling excess compute.
-> $GOOGL, $MSFT, $META, and $AMZN: Demand for compute far exceeds capacity. Capex go brrr.
Institutions: Emergency rate hike or 3x rate hikes, it's all over.
-> Kevin Warsh: No rate Hike.
Retail/Media: AI is crashing because it's a bubble.
-> Citadel looking to buy AI leveraged hedge funds positions: 👀
Jim Cramer: Sell all your leveraged DC stocks.
-> Koreans: SK Hynix +30%, Samsung +26.81%
$GOOGL$MSFT$META$AMZN
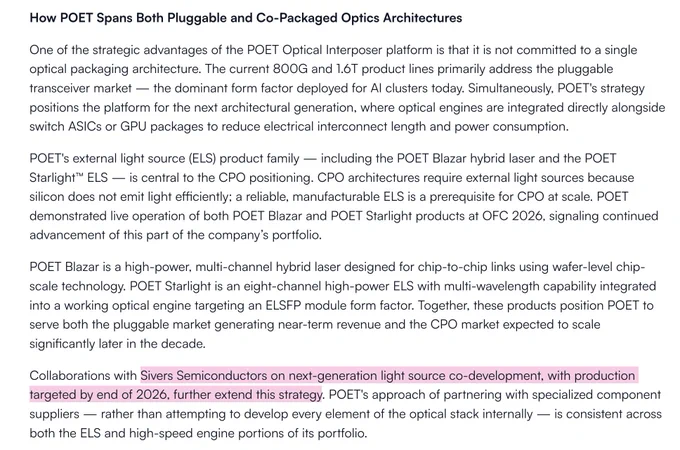
Now that I think of it more, $POET optical interposer piece is actually a little more material than I thought with $SIVE.
Originally the wording was "readiness" for EOY 2026.
But $POET upgraded that wording, by stating "production" with Sivers lasers projected EOY 2026.
So a volume orders from across $JBL to $POET, should hit in H1 2027. Which makes a bit of sense, since Sivers did raise an institutional oversubscribed round for future mass production.
On a side note, can't believe it's already August and 5 months left until 2027... Which was my inflection window for glass substrates, CPO, 800v, and new architectures to ramp.
↗ Quoting @A22GEO
$POET$SIVE$JBL
Yeah my thought was $XFAB could be an early $TSEM with actual SiC/MEMs foundry kinda bridging the gap while they develop their photonics arm.
They did reiterate exposure to CPO and 2028 timeline isn't priced into any revenue models yet (which I liked about them).
Might be a tad early, but we're getting closer in H2 2026 and the ER statements were very helpful.
$XFAB$TSEM
For $XFAB ER transcript:
Just to recap, my idea on $XFAB foundry growth opportunities stemmed from SiC for 800v and photonixfab/MTP for CPO applicability.
- $XFAB: "We are making progress in co-packaged optics".
- "The transition to 800v... is expected to support demand for both SiC and GaN... for XFAB"
So those analysts/people that were confidently bearposting about $XFAB that they had "0 exposure to 800V, photonics, CPO" just turned out plainly wrong.
At the time I shared my idea, industry materials showed ASE and others cited photonixfab + XFAB as an upcoming CPO player in EU. And filings showed they had exposure names like $NVTS / $POWI in general.
So glad $XFAB went out to explicitly clear things up to state they were developing in CPO/800v.
Okay back to the ER:
- "We continue to expect photonics volume production to start in 2028". Company currently has three silicon photonics projects in development with key partners.
I thought it would ramp sometime in H2 2027, but was probably early by a few months.
- Several new data center design wins, eg. 3 new SiC design wins (consistent with general 2027 ramp as 800v deployment takes off).
So once those ramp in 2027-2028, (markets tend to price things ahead of time), I'd expect $XFAB to be rerated based on growth opportunities.
TLDR:
- Current revenue numbers not as impressive.
- $XFAB confirmed direct exposure to CPO and 800V shifts (biggest win for thesis)
- 800V exposure opportunities for SiC (should be 2027)
- Timeline is 2028 ramp for photonics volume production
Happy exposure thesis to CPO/800V was confirmed from this ER. Might be a bit of waiting for revenue ramp.
↗ Quoting @jim29223471
$XFAB$NVTS$POWI

 @aleabitoreddit
Aug 06, 2026 · 05:56 ET
stock