Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
I’m actually kinda curious about $SIVE securing more foundry allocation given widespread CW DFB shortages now.
Since I’m pretty confident it sells out once qualifications go into volume ramp.
But aside from that
> reaffirm demand/supply imbalance from other earnings like $MTSI / $AAOI helps
> new development/qualifications mentioned in previous earnings with pluggable players, probably most material
> Progress with $JBL, ~ $AEVA, $POET, $GFS or other opportunities, maybe initial POs would be nice.
> Nasdaq listing update reiterated (we already got updates it’s planned completion next few quarters). I still place that on priority personally since it unlocks more funding for their M&A efforts, hopefully down the pluggable stack.
I think the revenue inflection starts around H1 2027, so current revenue/profit numbers are not very material.
An $AAOI statement like anything we make we expect to be sold in 2028 or something would be kinda goated.
$SIVE$MTSI$AAOI$JBL$AEVA$POET$GFS
@softmaxedx This is just laser array capacity modeling.
The bull case is $SIVE pulling their own Cloud Light acquisition and multiplying TAM starting from the laser chokepoint.
I have much higher expectations personally, but people can make their own valuation estimates.
$SIVE
I think it’s a good time to revisit $SIVE ~$427m/yr midpoint capacity revenue modeled projections.
Given recent industry earnings:
> $AAOI cited +20-40% demand imbalance for transceivers (with lasers as the bottleneck).
> $MTSI saying many "Customers are coming to us with urgency due to the general supply shortage of indium phosphide DFB lasers" (in other product lines)
> US proposal ban on new Chinese optical transceivers (Innolight/Eoptolink)
> AOI no meaningful participation in first-gen CPO deployments due to lasers being allocated toward transceivers.
The read through is that it’s possible to apply the same capacity-demand absorption modeling applying to $AAOI, but for other laser players like Sivers too.
Given the widespread shortage and demand imbalance for InP CW DFB capacity.
↗ Quoting @aleabitoreddit
$SIVE$AAOI$MTSI
Yep, I'm still bullish on Win. They're coming online with rare independent capacity for InP lasers (we know from Sivers) and maybe PiC foundry services (presentation slides) for AI DCs, during a time of a bottleneck.
And my guess is its optical foundry might drive surprising revenue growth 2027 onward.
$WIN$SIVE
@MDjavanmard This is satire about Michael Burry's long $LULU short $NBIS trade if you didn't get the reference (don't actually take this post seriously).
$LULU$NBIS
Today I'm writing a weekend guide on how to do DD when shorting $NBIS:
First, you look at hyperscaler earnings for AI cloud read through:
> $GOOGL: reports record AI cloud demand + backlog + margin increases from earnings
> $AMZN: reports record AI Cloud demand + backlog + margin increases from earnings
> $META: reports higher than expected prices for available capacity from earnings.
Now, time to look at Nebius:
-> $NBIS: Growing hundreds of percent to $7-9B ARR by Q4. Growing margins, and guided 4GW+ contracted power.
-> Sees Uber/Waymo splitting, putting more focus on Avride
-> Sees Clickhouse growing rapidly every quarter.
Okay looks bad! But next, you need a hedge?
-> Wow! A $NIKE brand executive, after the stock dropped 75% over the past 5 years, went to $LULU to save that brand next? Lululemon seems good.
Conclusion: Short Nebius and go long on $LULU
$NBIS$GOOGL$AMZN$META$NKE$LULU
Yes, I'm still bullish on memory like $MU / Samsung.
As I said earlier, markets tend to rotate from bottleneck to bottleneck.
This week it looks $AXTI to $LITE in the photonics sector is the focus again.
The thing is... the primary thing that changed are the stock prices, followed by some narratives + updates sprinkled in here and there.
For photonics:
> We already knew $COHR / $LITE lasers were completely sold out for the next 2 years during July's drop.
> We knew about demand imbalance from $AAOI from last quarter's earnings calls.
Nothing deteriorated fundamentally during July's crash, other than listed price after liquidations.
Yet tons of people called $AAOI a "scam" when it dropped to $75, or $AXTI a "scam" on its drop to $35...
But are bullish again at $140 or $80, when the transciver/InP substrate bottleneck hasn't changed at all, but maybe even got worse... (eg. draft for US ban on new china optical transceivers, scale up demand projections)
For Memory:
I'm witnessing a lot of retail capitulation, but the same people I'm seeing were mega bullish after $MU signed 16 SCAs and gave exceptional projections a month ago.
Or were celebrating Samsung having the highest operating profit in the world.
There's updates here and there eg. Rubin Ultra with memory optimizations (which Nvidia strives for every generation), with prices no longer being hiked way above expectations to the extreme.
But the operating income relative to MC is just absurd around current prices, especially memory becomes structural.
And the demand imbalance should be even worse next year.
People tend to capitulate and follow narratives when a sector drops (eg. Helium/LNG back in Iran war), even if the bottleneck or fundamental situation hasn't really changed much (eg. $SPCX Elon earnings call reiterating memory tightness).
I can't tell others what to to do:
But $AAOI at $140 and $AAOI at $75 are the same company.
Samsung at a $1.5T MC and Samsung at a $980B MC are the same company.
Just valuations and narratives (often noise) change, and markets rotate from sector to sector.
↗ Quoting @KostasMoschovas
$MU$AXTI$LITE$COHR$AAOI$SPCX$NVDA$SSNLF
I've mapped the entire Wall Street bear playbook on AI names:
Have your favorite institution/media insert one of these name down below:
1. < ______ [GPUs, Transcivers, MLCC, Memory...] are a commodity set to crash>
2. < ______ [YMTC, CXMT, Dongshan...] from China will flood the market >
3. < ______ [Micron, Nvidia, ...] from unverifiable channel checks is facing issues >
4. < ______ [Kospi, Sivers, ...] is a bubble like the ____ [2007, 2021] crash>
5. <____ [1,2,3, ...] unexpected rate hikes this year>
6. < _____ [Google, Nvidia, Deepseek ...] optimization removes the need of this!>
in a new headline, and it's ready to go!
$NVDA$MU$GOOGL$KOSPI
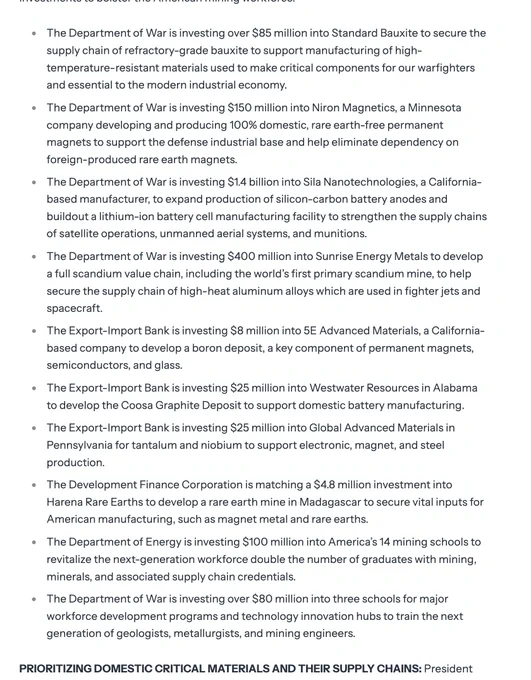
There we go, White House finally invests in more breath in critical minerals/materials. Amazing policy move, as a TLDR:
- $WWR receives $25M (graphite)
- $SRL (ASX) receives $400M (Scandium)
- $FEAM receives $8M (Boron)
- $HREE receives $4.8M (magnet rare earths)
out of the public companies.
With more private investments from $150 million into Niron Magnetics or $85 million into Standard Bauxite.
It's literally spare change to the US gov, for ENORMOUS amount of downstream applications.
More should be done with funding amounts to accelerate development and derisk supply chains (don't own any of the above, just support the policy move), but great announcement.
$WWR$SRL$FEAM$HREE
Good question! This something year-by-year, can't really predict shortages into 2030 from 2026, but it's definitely a structural multi-year demand cycle.
Something that I want to flag is that it looks like lasers in specific would likely have extreme shortages for the next 2-3 years, especially during CPO scale up at the very least.
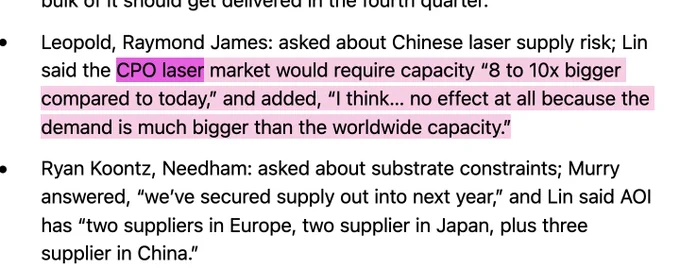
eg. CPO laser market would require capacity "8 to 10x bigger compared to today," and added, "I think… no effect at all because the demand is much bigger than the worldwide capacity."
As for InP substrates, $AAOI said they were fine for 2027 calendar year but wanted to form JVs because of likely how critical they are since.
$AXTI looked like they were just multiplying capacity year after year and depends on who you ask..
Some of the Taiwan epiwafer players say it's extreme shortages for InP substrates, when they feed into your laser players.
Your laser players like $AAOI and $MTSI say they're fine.
Regardless, we see that convert into revenue inflection points with AXTI anyway (~$130m/quarter in 2027), but I'm expecting ASP to be hiked along the way given their positioning.
$AAOI$AXTI$MTSI
Some more TLDR takeaways from $AAOI ER:
- They also flagged DSP and TIA bottlenecks, which is a positive industry read through for names like $MXL, then $SMTC and $MTSI.
- For revenue growth, they're expecting more than $500 million revenue Q4, which is absurd growth.
For reference:
Q2: $191.9M
Q3: ~$255M-$290M
Q4: $500M+
By mid-2027: ~$1.41B quarterly revenue run-rate
Always impressed by the revenue ramp from some of these optical players.
↗ Quoting @aleabitoreddit
$AAOI$MXL$SMTC$MTSI
I usually make fun of sellside, but Rosenblatt has pretty goated channel checks on optical names, and their reports are one of the few I like talking about.
$AAOI, $LITE, $SIVE, and the laser party has started to recover around the est. timing windows.
eg. last month: "Multiple short sellers told them they will likely close their positions... late July and early August".
They might have missed that they believed $AMD would be $AAOI's first CPO customer... since AAOI said they would be missing from first-gen CPO (maybe future gen?)
But lot of their talking points about China CPO laser positioning (eg. 2-3 years behind) got corroborated word-for-word from AAOI earnings today.
$AAOI$LITE$SIVE$AMD
Unitree, China's humanoid leader, is set to IPO this month at a $9B valuation! (~$6.2B originally per March filing).
Derivative markets are pricing open at an implied $36.04B MC, roughly ~4X listing price.
$CCXI / Agility Robotics, the first US publicly listed pure play humanoid leader, is also going public later in Q4, at a ~$2.5B pre-money valuation.
It will be interesting to see how markets price in America vs. Chinese Humanoid leaders.
$CCXI
Unitree is being listed this month, and is expected to open around a $30B valuation (pre-IPO perps) from ~$5.6B -> $9B now.
Given Agility is valued at $2.5B premoney with $CCXI, I’m just watching what happens to the robotics sector and especially Agility, when Unitree goes public.
I’ve already laid down my thesis with humanoids and I’m personally waiting for it to play out.
$CCXI
Uhh I don’t want $SIVE to be acquired given how attractive their laser assets are. Since I see potential for them end up as the next $LITE.
Honestly carving out OE solutions complete optical transceiver business or something similar that’s distressed from a private startup might be interesting.
My guess is it comes after Nasdaq listing within next few quarters or so. I think the CEO knows what to do, so I’m just tagging along for the ride.
$SIVE$LITE
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $LITElong |
-8.6% | +4.0% | -1.0% | — | +9.0% |
| $SIVElong |
| | | | |
For now yes, because Lumilens has a direct hyperscaler customer and multi-billion dollar purchase agreements. While $SIVE is an upstream laser supplier.
Sivers needs to work its way downstream to capture more TAM with selling optical engines, ELS, or complete optical transceivers like $LITE did after M&A eg. Cloud Light.
My opinion is that it’s easier to move downstream than upstream as you seen with the limited amount of qualified laser suppliers out there.
$SIVE$LITE
Earlier today, optical interconnect company Lumilens "emerges from stealth" at a $5.5B valuation, after raising $700m.
Just as a recap from $POET / $SIVE Linkedin OSINT mapping I shared earlier, Lumilens was supplying a top 3 hyperscaler customer.
So we got confirmation of that a month later, along with the material figure that Lumilens has a "multi-billion-dollar customer agreement".
And just for reference, $POET has existing contracts with Lumilens ($50m purchase order, up to $500m) + contracts with $SIVE (depending on product lines).
I actually took tiny positions in POET again after reading this news, since it finally gives them visibility into extremely well funded hyperscaler suppliers (on top of Poet's really large balance sheet).
But TLDR:
> Lumilens around similar (or even higher) valuations as Lightmatter/Ayar, bigger than markets thought with hyperscaler customers.
> nice read through upstream on $POET (derisking) / $SIVE.
> Great for optical valuations in general, seeing a company go to $5.5B in 2 years.
$POET$SIVE
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $POETlong |
-3.9% | +7.5% | -11.1% | — | -16.0% |
| $SIVElong |
| | | | |
I literally and legally can't give you advice.
I'm personally long and still bullish on $AXTI since I don't think InP substrate demand imbalance will be going anywhere over the next 2-3 years.
And my InP substrate bottleneck thesis + AI buildout disruption got validated midway through the year from Reuters to other epiwafer earnings calls.
You do you
$AXTI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AXTIlong |
-16.7% | -7.8% | -30.4% | — | -12.6% |
It's because $AAOI already has a massive 20-40% demand imbalance for their 800G/1.6T optical transceivers...
They can't make enough to satisfy demand. That's a positive thing.
But not being able to fulfill all demand, means there's market opportunities for smaller CPO laser players.
$AAOI
I'm extremely bullish on $AAOI, it's one of my top holdings?
But there's an unholy amount of things to unpack when AOI said they're not participating in first-gen CPO deployments because there's not enough capacity.
1. Independent CW DFB capacity, even less than markets thought.
2. Qualified CPO laser players, even less than markets thought.
3. I remember Rosenblatt thought $AAOI would be $AMD's first CPO customer, but might not be the case anymore...
And since $LITE and $COHR are in camp $NVDA and sold out for next 2 years...
Some other CPO players might be more valuable than others think.
$AAOI$AMD$LITE$COHR$NVDA
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-2.1% | +10.8% | -22.2% | — | -26.8% |
| $AMDlong |
-2.9% | +6.4% | -1.2% | — | +26.6% |
| $COHRlong |
-14.2% | -14.1% | -25.7% | — | -24.1% |
| $LITElong |
-8.6% | +4.0% | -1.0% | — | +9.0% |
| $NVDAlong |
-2.9% | +0.5% | +2.9% | — | +2.1% |
Wow, there's gem after gem in $AAOI earnings for $SIVE + other laser player readthrough.
1. AAOI not meaningfully participating in CPO first-gen deployments.
"We just can’t make enough of them [CPO lasers] to be involved in their current first-generation [CPO] deployments because there’s just not enough capacity. We have to prioritize our ability to make lasers for our own transceivers first"
So first-gen CPO laser deployments, might even be narrowed down further for Western players like $SIVE, $LITE, $AVGO, and $COHR.
And independent CPO CW laser capacity became more valuable if $AAOI had to turn away more customers...
Also remember Trendforce was talking about $AMD singing CW LTAs? $COHR / $LITE have capacity signed with $NVDA ...
I thought it would be $AAOI, but they might be out of the equation. $MTSI also doesn't look meaningful with early CPO participation (eg. no mention in ER aside from NPO, and removal from Ayar website).
So I wonder who players like $AMD is going to go with for Helios (eg. Sivers + Ayar more likely candidate now)?
Btw, this is not bearish AAOI because they have too much demand for optical transceiver business. Just more bullish on the existing few qualified CPO laser names that have capacity.
2. Demand imbalance and bottleneck for InP lasers / optical transceivers.
AOI's CEO stated kinda supported that when they said: "The customer demand is 20%-40% higher" than expanded built out capacity.
"We are getting this kind of demand from several big customers almost every week. Lasers are the biggest bottleneck right now for the transceiver business"
3. China being years away from having CPO DWDM specification lasers.
I covered this earlier when looking at CPO competition from channel checks.
But AAOI confirming that China is "easily at least two, three years or even longer from having CPO lasers is incredible tread through on defensibility Western laser positioning in the CPO laser chokepoint.
TLDR:
- High demand imbalance for CW lasers and optical transceivers.
- $AAOI not in first-gen CPO due to capacity constraints (not exactly bearish AAOI because they have too much demand for their optical transciver business, but even better news for the few independent players with capacity coming online like $SIVE)
- China years behind in CPO lasers.
$AAOI$SIVE$LITE$AVGO$COHR$AMD$NVDA$MTSI
$MTSI earnings transcript:
"Customers are coming to us with urgency due to the general supply shortage of indium phosphide DFB lasers"
Emphasis on "Urgency", CW "DFB lasers", "coming to us".
CW DFB names, such as like $SIVE and $LITE should be happy to hear about this laser bottleneck getting validated.
$MTSI$SIVE$LITE
It makes me happy that people are reiterating my $AXTI thesis from last year like it's a legitimate threat to the AI buildout now.
Also just some nuance Innolight, buys EML/CW lasers off other players, which is the bottleneck. Not so much downstream assembly/integration layers.
$AXTI
$LITE CEO said even as their 5 InP laser fabs come online, shipments would be 30%+ below customer demand. (and worse than the current memory shortage)
$AAOI said something similiar with a 20-40% figure.
My guess is that InP substrates and lasers both will be one of the most severe bottlenecks in 2027.
Which is why I place a lot of value on any independent capacity that comes online whether it's $SIVE with Win or $AAOI.
$LITE$AAOI$SIVE
Just some TLDR notes on $AAOI earnings:
- Expects full qualification of 1.6T products by their hyperscaler customer within next couple of weeks
(helpful revenue ramp #2, timelines)
- Continues to believe that AOI will have the largest AI DC transceiver production capacity in the US
(reiterating ambitions during a time when their competitors might get banned)
- Expects facilities toward InP capacity to come online in early 2027
(timeline FYI in terms of further ramp)
- Total capacity is approaching 200,000/u per month, EOY 650,000/u per month of 800g/1.6t. EOY 2027, 930,000/u
(this is the ramp i want to see)
- "increase our manufacturing capacity for our external light source or ELSFP. That's for co-packaged optics or CPO". we anticipate ramping production later this year and into 2027, ultimately culminating in about 400,000 pieces per month in 2028
(need some time to model this into revenue)
- "As we have mentioned before, we've been manufacturing lasers internally for many years. This has allowed us to avoid some of the shortages that have affected others in the industry"
(vertical integration bull case during CW/EML laser shortages)
- We believe that in the future, CPO will continue to drive increased demand for high-power lasers
(thesis validation on CPO sector)
- "to our long-term objective of returning non-GAAP gross margins to around 40%"
- "We ended the second quarter with $508.8 million in total cash equivalents"
I need to double check if the ATM finished or not
- "our ability to deliver revenue in general, and specifically when it comes to 800G products, is limited by our production capacity right now" "If we could produce more, we could ship more right now"
Demand > Supply validation.
- "Most of the increased capacity will be in U.S. Even so, let me say that, like I keep emphasizing, that is not good enough for the customer demand. The customer demand is 20%-40% higher."
Unholy photonics demand validation across the whole sector, read through for $LITE, $SIVE / $JBL, and others is amazing.
- "Not in the next two, three years, especially the demand is so big. Okay? Even combined AI, $LITE, $COHR, $AVGO all together, it's still very tough to meet the customer demand in the next few years"
More optical sector demand validation.
- CPO Timelines: "If you're talking about really high volume manufacturer [for CPO market], I would say more like the late Q3 next year" and "We have been working very close with at least five customer"
If you care about current earnings (which I'm not really looking at closely)
Revenue: $191M vs. $190m
EPS: $.06 vs. $.02
TLDR: Extraordinary demand across the laser + optical sector read through. Kinda supporting Lumentum CEO statement that laser shortage is worse than memory shortages.
2027 capacity ramp on track. To map inflection period with timelines, would be around early next year, as stated in their previous earnings call.
AAOI has the customers now. Limitation is making enough lasers and transceivers.
$AAOI$LITE$SIVE$JBL$COHR$AVGO

 @aleabitoreddit
Aug 08, 2026 · 21:32 ET
stock