Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,505 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
I feel like traditional "value investing" went into hibernation.
Before it was finding a 10x -12x P/E company like $UPWK or $PYPL, Dominoes, Pepsi. Or even a cheap Japanese company below book value.
Then just enjoying slow growth but buyback/dividend appreciation from their cashflow.
Now you can find 1.8x runrate P/E company like $ESMT that grew revenue 605.24% Y/Y.
And the main thing you need to argue about is duration.
Or a 16.2x trailing P/E Sumitomo, despite having way too many hyperscaler LTAs in AI from fiber to lasers.
AI created much bigger medium-term anomaly, where "value investing" went towards high growth, "deep value" companies.
$UPWK$PYPL$ESMT$DPZ$PEP
Wow Bitcoin + Ethereum pulled pretty extreme recoveries.
Looks like $HOOD / $COIN / Crypto is back?
On-chain equities trading + regulator exemptions probably put a lot of fuel into the fire for the sector.
That aside... crypto is usually a great indicator for high-beta AI equities believe it or not (they tend to frontrun broader market drops or rallies).
So overall market risk appetite might be coming back despite the rate hikes.
$BTC$ETH$HOOD$COIN
All right $META Muse is cooking.
I can hear all the $AMD, $INTC, and $ARM CPUs vrrrring in the background.
Along with the memory + components (NICs, SSDs, DRAM) needed for all the browsers/VMs
When I ask it to do a bunch of long form tasks…
Intel CEO also said recently that CPU demand is so strong they can only support 50% of what customers need, so there’s some signals there.
I’m also curious how much $AMZN or $NBIS is involved with running Muse, or if Meta hosts everything inhouse.
Kinda an ADHD post but Meta beat my expectations with this release.
Will keep trying it out
$META$AMD$INTC$ARM$AMZN$NBIS
We’re in the modern agricultural revolution.
In terms of civilization-level impact of AI.
So… not sure how anyone can be bearish so early on into the singularity and before mass deployment of physical AI. https://t.co/uJAXpZm4MP https://t.co/ZuvSRNIaxs
↗ Quoting @openai
ridiculous report. The way $NBIS does financing is much more sustainable than $CRWV and other neoclouds.
There were also claims about falling GPU pricing but Nebius hiked rates by like 17-21% (oracle also hiked pricing for 4+ year equipment).
Sum of parts is also something many analysis miss, Clickhouse would likely drive a lot of value to nebius. As well as Avride (with Uber) + their other companies.
$NBIS$CRWV$ORCL$UBER
@Frenchie_ AMS Osram is not a current bottleneck, but likely a future one. Microleds will have its time to shine in 2028.
$AMS
Glad $AXTI also went up +12.4% today. It's probably being used like a chess piece in terms of Xi + Trump discussions right now.
Since InP substrates would bottleneck the optical buildout by the US for AI.
But if they have more control over pricing... I do think there's a lot of room for rerating.
$AXTI
$SIVE and $AAOI, yes for a 2027 timeframe. That's the nuance.
Sivers you're coming on with 100M CW DFB laser capacity + 2 external foundries (maybe 300M in total), and all my supply chains mapping maps to larger hyperscaler suppliers.
AAOI you're coming on with $471m transceiver revenue + 400K ELS units for 2028 timeframe. With hyperscalers + demand eating up all their capacity. There's just a $600m ATM which presents overhang near term.
$NBIS already got re-rated but it's very positive upcoming for Q4 2026 (esp. with price hikes).
Legacy memory like $ESMT + (some I haven't named yet) + regular memory names like Samsung, I do think will strongly outperform near term. And obviously CPUs names like $INTC $AMD $ARM as of recent.
$SIVE$AAOI$NBIS$ESMT$INTC$AMD$ARM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
-1.5% | -10.9% | — | — | -8.7% |
| $AMDlong |
+1.3% | -1.2% | — | — | -0.6% |
| $ARMlong |
+3.2% | -12.3% | — | — | -10.3% |
| $INTClong |
+1.7% | -4.7% | — | — | -1.3% |
| $NBISlong |
+1.4% | -0.4% | — | — | +1.3% |
| $ESMTlong |
— | — | — | — | — |
| $SIVElong |
| | | | |
$SOI is the perfect example of a complete monopoly over silicon photonics. (lot of folks float 95% figures like UBS or Shin Etsu that Soitec basically licenses), but practically speaking...
It's kinda 100% since it's used to manufacture all SOI Wafers, people just don't like to use the word monopoly in markets.
Depends on all their LTAs that they're going to sign as well as pricing. I would appreciate it if they abused their position to secure higher pricing.
We'll see on the scale of their agreements if it deserves to be ATHs again
$SOI
I'm not having a fun day since I got sick today. But the bottlenecks are having a good time:
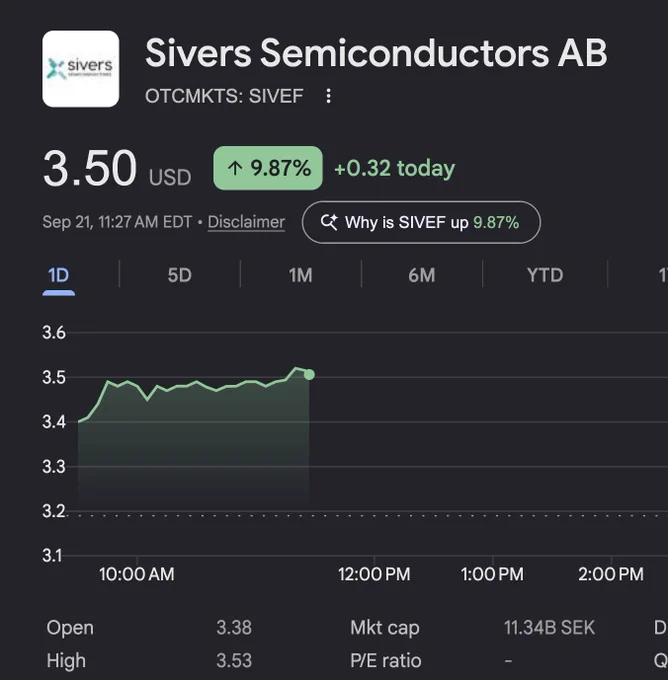
$AMD +9.13% | $INTC +14.16% | $ARM +14.33%
CPUs go brrr
$SIVE +10.32% | $AAOI +3.39% | AMS OSRAM +24.61%
Lasers go brrr
$EWY +4.08% | $DRAM +2.83% | $MU +2.23%
Memory go brrr
$NBIS +4.7% | $CRWV +5.03% | $IREN +1.73%
Compute go brrr
Probably most material developments were CPU:GPU ratio expectations + CPU demand (from new AI releases).
As well as optical developments from ECOC 2026 (as seen with $MRVL PR + others)
Still a lot to catch up on.
↗ Quoting @aleabitoreddit
$AMD$INTC$ARM$SIVE$AAOI$AMS$EWY$DRAM$MU$NBIS$CRWV$IREN$MRVL
I personally think $ESMT should be a lot higher since July net income was absurd (~$111M, <2 annualized July RR). Growing revenue ~16.5% M/M is also absurd from July -> August.
And I did track their products, which has high sensitivity to hikes... (which are heavily expected H2)
Markets aren't always efficient, and maybe just needs a reminder after Q3 earnings.
$ESMT
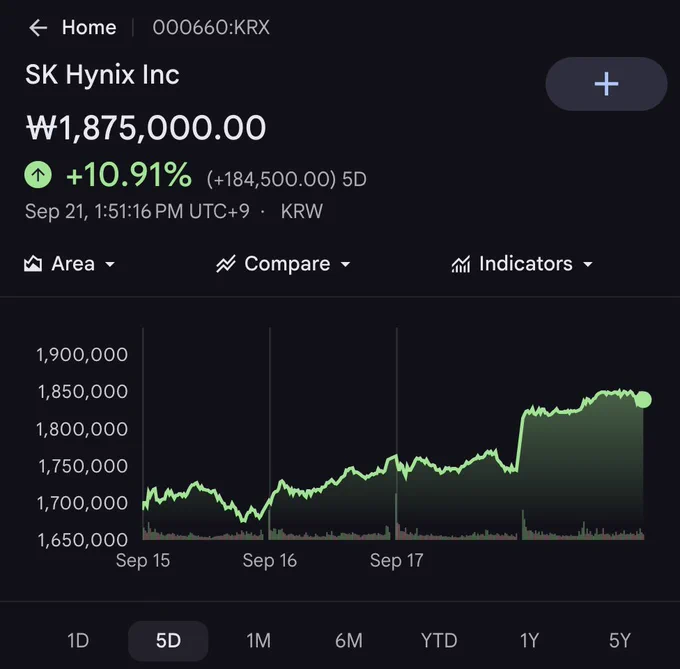
The main duo $SKHY and Samsung are having a fun day.
I'm still long memory (eg. $EWY / $DRAM ) since if capacity agreements extend 3-5 years... and your analysts model 2.8-3.3x 2027E. Risk/reward is attractive over time.
But I think legacy memory a very interesting trade currently due to ASP hike potential..
It also just so happens these same companies procure memory from even smaller memory companies (that might have higher sensitivity)...
So if you want to, you can track $PSMC wafer allocations, and find some interesting companies that likely replace $MU discontinued legacy memory through Alliance or supply directly to Samsung.
Won't mention them on X, but just throwing out some research ideas.
$SKHY$EWY$DRAM$PSMC$MU$SSNLF
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $DRAMlong |
+3.3% | -3.1% | — | — | -2.2% |
| $EWYlong |
+1.8% | -2.9% | — | — | -3.4% |
| $MUlong |
+5.0% | +1.0% | — | — | +2.4% |
| $SKHYlong |
+3.4% | -3.7% | — | — | -2.5% |
| $PSMClong |
| | | | |
| $SSNLFlong |
— | — | — | — | — |
@Pau1R0b $RDDT will probably get more accounts + revenue from AI bots that act like human so I’d guess earnings beat.
Changing public opinion with AI is really bad for democracy and long term platform health though.
$RDDT
@cchronobreakk I mean Sam Altman was working on iris scan with his World project, so he probably saw it coming.
But human verification is probably needed across the board now for each account.
$RDDT doesn’t require much so platforms like that are first to be manipulated.
$RDDT
The internet is now cooked soon?
With $RDDT to other social media like X more at risk due to AI.
You can have new decision models like Jev making autonomous computer interaction at near $0 cost. (With actions becoming more human-like/adapative)
Then LLMs outputs influencing behavior or leading conversations.
So at scale, a malicious actor can spawn 50,000,000 bots just roaming the internet, with LLM prompts convincing people + manufacturing public opinion.
The main bottleneck would be phone number, IP, account age, maybe hardware for compute + device identifiers (which is extremely cheap still)… rather than LLM cost.
I’ve already anecdotally seen short sellers use AI bots to spread negative misinformation about companies like $SIVE.
Or bots market ____ account as the best one to follow in the comments.
Or as seen with X uncovering 200+ bots manipulating debate about datacenter public opinion.
But the scale might be exponentially worse soon.
Scary to think about.
$RDDT$SIVE
@Temptemo95 Thanks for following all this time! Entire training arc from $RDDT to 1M followers on X has been quite a rollercoaster.
Guess like I need to start drawing anime and league characters on top of the $INTC or $NBIS charts again.
$RDDT$INTC$NBIS
While everyone is focused on Bessent/He Lifeng talks today. Or $LITE / $MRVL / $SIVE at ECOC optical conference...
I'm just curious why my followers can leave 2K+ comments if I post in Chinese...
But if I share something in English: I only get 50 comments.
Feels bad anon https://t.co/Pg6fojfMFx
↗ Quoting @aleabitoreddit
$LITE$MRVL$SIVE
Just floating out an idea to $AVGO:
If you lock up $SIVE laser supply for next few years since you need “more laser capacity”.
You could unintentionally cause bottlenecks across your main ASIC competitors:
Like $MRVL (Celestial), AlChip, Mediatek, GUC (Ayar CPO), first gen deployments.
Where many also seem to be aligned with your best friend $NVDA…
Maybe it’s worth discussing spending spare change to lock up the remaining merchant laser supply?
$AVGO$SIVE$MRVL$NVDA
So on optical vs. photonics... Memory like $MU / $SKHY is in it's current supercycle.
-> RBC channel checks for example projects 80-100% HBM ASP hikes for 2027.
-> Per $NVDA ER, Hyperscaler capex goes up in 2027. Then you have 68% of hyperscaler capex per Trendforce going to DRAM/NAND.
-> 50-70% for next 3-5 years already allocated toward LTAs.
So supercycle is here... demand visibility is high and the price hikes are still ongoing.
As photonics like $SMTC to $AAOI, I expect to cook heavily in 2027 since we're already seeing widespread optical shortages in 2026.
Plus, you're going from $67.7B in 2026 (per GS) to $131.4B TAM in 2027 for optical modules...
Which impacts the DSPs/TIAs/lasers/fiber suppliers before CPO scale up really takes off in 2028.
I don't think we'll ever see the same scale of memory price hikes, but I do think there's a lot room for more for MC growth in optical supply chains (given smaller starting point eg. $1B CW laser supplier vs $1T memory maker).
But still there's room for price hikes on laser content (eg. $15–$20 for 4 70 mW lasers per GS note) since starting point is really cheap... and one component, like cheap InP substrates can break hundreds of billions worth of supply chains downstream.
We're already seeing laser price hikes tho from CIOE channel checks confirmed by both Innolight / $SIVE from the Serenity's follower channel checks.
So entering uncharted territory.
TLDR: Messy thought but, memory has near term earnings power, midst of current supercycle.
The next "memory" ASP hikes I'm seeing is clearly legacy memory (DDR2/DDR3/SLC NAND) from cascading bottlenecks. It just looks to be an extension of the memory theme.
Maybe MLCC looks similar in terms of earlier cycles.
If we were to track supercycle impact on the supply chain in the space...
I'm confident next thematic one looks to be photonics entering 2027.
↗ Quoting @blkslymn
$MU$SKHY$NVDA$SMTC$AAOI$SIVE
TLDRs of things I found interesting this week:
- $INTC CEO says some memory prices have risen 5-7× and warns the shortage will worsen in 2027.
$SNDK / $MU / Samsung bros will be happy to hear this... (from the AI Infra Summit 2026 in Santa Clara)
- $GFS + $MRVL sign extended SiGe capacity agreement for pluggable/NPO/CPO. "Expected to add significant capacity to support Marvell’s growing requirements."
I like to keep an eye out on Globalfoundries related updates given $SIVE is their reference laser for SCALE.
- $CIEN expects roughly 30% annual revenue growth, 50% adj. gross margin, 20% FCF margin, through FY2029.
The company says component availability, not demand, is limiting growth... Seems common across $NVDA to upstream suppliers that supply is the limiting factor for revenue growth.
- Winbond acquires Infineon's NOR Flash and F-RAM business for $1.12 billion.
Very surprised Infineon sold considering NOR Flash ASP + importance just keep going up and up and up, but good for Winbond consolidation.
- Samsung reportedly expands outsourcing of DDR5-module and SSD assembly.
I think some local Taiwan reports flag Transcend and Apacer as possible beneficiaries. The report specifically identifies Dreamtech, Hanyang Digitech and SFA Semicon.
I've noticed other Korean firms entering new Samsung Electronics contracts for likely legacy memory modules maybe like ~1-2m ago.. So think some media commentary probably missed this too. Maybe too small for them to notice?
- $NBIS raises AI cloud prices for the 2nd time in three months (~17-21%), bullish read through for other Neoclouds like $CRWV to $IREN earnings.
- $AMZN signs $2.4B agreement with $GNRC for generator deliveries throughout 2027-2028... and received warrants tied to as much as $8B of aggregate purchases
Good to keep an eye out on who Amazon signs these warrant agreements with (eg. Alchip, $AAOI, $QCOM, $MRVL, etc) and what type of infra procurement they want.
- $TSEM and NewPhotonics begin volume shipments of laser integrated optical engines.
Not familiar with newphotonics, so not going to leave much commentary here. But will do some research today.
- Goldman Sachs reportedly sees the ABF deficit expanding from 14% to 51%. Forecast shortages are 14% in 2H26, 34% in 2027 and 51% in 2028...
More substrate bottleneck stuff, not surprising regarding demand imbalances.
- Crusoe raises $3.9B at a $30.9B valuation.
Okay this valuation is better than Instinct raising at a bubble $10B valuation off 100k users...
- Japan and the U.S. reportedly discuss a $12.9–19.3B $GFS run fab.
That's like half of Globalfoundries marketcap lol. Not much details here.
- $ARM CEO Rene Haas said he is confident that they can secure enough supply to meet $2B in customer demand (for their AGI CPU).
There's probably a lot more demand, probably supply constrained growth as usual so good $ARM signaled confidence in securing allocations.
- Supply chain sources said Kioxia has about 50% of its LTA capacity tied up, while SK Hynix/Samsung reserve about 70% of capacity for LTAs for 3-5 years.
Not sure how people are bearish on memory....
I don't like posting updates one-by-one like a news reporter, so hope this saves some time of stuff I like looking at.
On a side note was surprised markets from $AMD to $INTC rallied today after rate hikes. Think high-beta overshot the selloff the most.
$INTC$SNDK$MU$GFS$MRVL$SIVE$CIEN$NVDA$NBIS$CRWV$IREN$AMZN$GNRC$AAOI$QCOM$TSEM$ARM$AMD$GS$IFX
@DanilSer33 Legacy Memory prices are rising more than the Shield Hero
$ESMT$WINBOND$FIDELIX
Just in case you're wondering why I'm so bullish on legacy memory...
Their hikes seem a lot extreme than $NBIS reported +17-21% GPU rentals today or Taiyo-Murata type MLCC hikes.
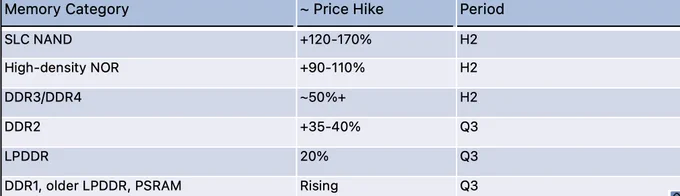
Price hikes projections expected for H2:
- SLC NAND: +120-170% in H2 vs H1
- High-capacity NOR: +90-110% in H2 vs H1
- ~DDR3/DDR4: +50% Q3
- DDR2: +35-40% in Q3
- LPDDR: +20% or more in Q3
- DDR1, older LPDDR and PSRAM: also rising
As a consolidated view...
Lot of these are stacked off existing hikes H1, (eg. 130-150% for H1 SLC NAND), so you get +406%-575% cumulative throughout 2026.
Which impacts blended net income overall more than upstream wafer COGS hikes (eg. +45% DRAM wafers from $PSMC)
So I'd expect Q3 earnings for a lot of the legacy memory fabless companies to cook
$NBIS$PSMC
@StephanTeo39458 I think $IQE, VPEC and your recent epiwafer foundry type company commentary was very strategically bullish on $AXTI.
This Foxconn note wasn’t clear on InP substrates.
The main thing going forward is if AXT is able to pull off $SNDK style price hikes given their market share
$IQE$VPEC$AXTI$SNDK
Reminiscent of $NVDA w/ $LITE + $COHR:
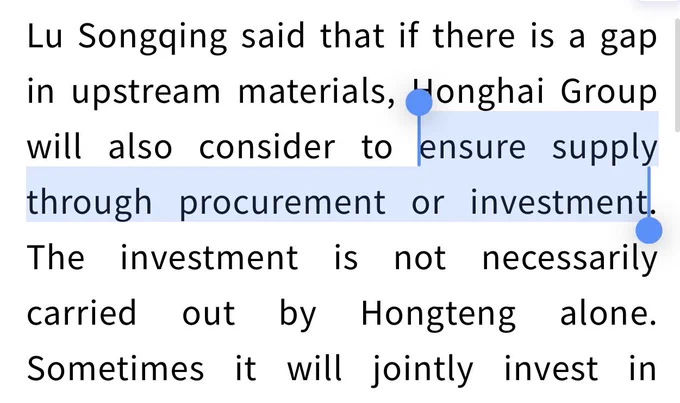
Foxconn is now considering joint investments to avoid upstream material shortages.
Foxconn Interconnect Chairman identifies CW lasers and fiber as the biggest bottleneck in photonics.
Very interesting to see these two themes reiterated across industry commentary.
Almost like a certain Anime character on X was right about CW laser bottlenecks.
↗ Quoting @aleabitoreddit
$NVDA$LITE$COHR
@ptcalad
$SIVE$SOI$AXTI

 @aleabitoreddit
Sep 22, 2026 · 09:36 ET
stock
1st mention