Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
@lijiu163076 $NVDA is growing at a capacity constrained 70% next year, which is ridiculously good.
My opinion is that it's hard to go wrong with Nvidia, because it's almost like a semiconductor ETF? They own decent parts of $INTC, $MRVL, $LITE, $COHR, $NBIS, and Mediatek now.
$NVDA$INTC$MRVL$LITE$COHR$NBIS
I mean I do have 1 single share of $IREN now, so I'd love to see them get a deal with Anthropic.
There were leaked memos suggesting that Anthropic was looking to secure more in Australia, and that just so happens to be the country Iren was heavily investing in.
Buuut, the $25-30B capex number is always a bit daunting during current macro, despite securing a lot of financing via prepayments.
$IREN
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $IRENlong |
-0.8% | +20.4% | +10.1% | — | +10.1% |
Anthropic signs a $35B AI compute deal with $NVDA backed Lambda.
$HUT / DC, with Lambda / GPUs.
Frontier model demand is rapidly outpacing the ecosystem's ability to build capacity.
It also looks like Anthropic is securing more compute... Which neocloud/colo player is next?
$NVDA$HUT
@mykwantitative Yep, probably that as well in a similar window. Seeing $SNDK go vertical at close was interesting
$SNDK
Interesting to see $QQQ spike when Trump gave a comment on potential rate hikes:
Answer: "Trump: No, I have a lot of respect for him, and he'll do what he has to do.
I think our interest rates are too high."
$QQQ
Macro has clearly cut high beta AI valuations over the past few months. But I try to stay focused on fundamentals.
If you're curious about my take though:
We're seeing record visibility with
- memory (2031), photonics (2029-2030), etc LTAs
- $NBIS, $AWS, etc. massive demand imbalance for compute despite capex spend.
- combined with record projections ( $NVDA 70% growth 2027, $SMCI $60B+ new server orders, etc).
vs.
uncomfortable macro where:
- Warsh said the Fed has "more work to do" if underlying inflation isn't clearly returning to 2%.
- July PCE came in at 3.7% Y/Y
- July jobs report payrolls fell by 23k with unemployment at 4.1%
-10Y Treasury high/ 30Y highest since 2007
- Iran tensions continuing
- Japan Yen weakened to 160/ 2 rate hikes in Korea
And with rate 40/60 in favor of 25BPS near-term hikes.
There's definitely implications on financing + too many third/fourth order effects for me to personally map.
I'm not a macro expert but my take is:
The AI buildout will continue w/ $1.3T+ capex poured upstream expected next year, flowing through many bottlenecks and chokepoints.
While markets chopped off forward valuations and rotated toward currently profitable/defensive companies.
I don't know what's going to happen, especially since rate hike odds are almost a coinflip, and Trump posts can change sentiment overnight.
As long as I don't see indicators of hyperscalers cutting capex or demand wavering.
I'm staying long despite macro volatility, since I want ownership of the names controlling the future of the AI buildout.
And if there's any indicators of better macro climates, high beta are typically the fastest to recover.
↗ Quoting @dBooray
$NBIS$NVDA$SMCI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $NBISlong |
-3.3% | +9.7% | +14.3% | — | +14.3% |
| $NVDAlong |
-1.5% | +4.3% | +3.6% | — | +3.6% |
| $SMCIlong |
-1.5% | +6.2% | +10.1% | — | +10.1% |
Yep, with $NVDA investing $3.5B into Mediatek.
It does feel like Nvidia is playing kingmaker with the next generation of ASIC winners like $MRVL / Mediatek, with a second order effect of eroding $AVGO position.
Playbook feels similar to what they did with Neoclouds like $NBIS and $CRWV (vs. hyperscaler cloud programs)
Help create the next leaders, then make them both financially and strategically aligned with Nvidia.
I do think it’s brilliant, but moves like this might push $AMD, $AVGO, and certain hyperscalers closer together.
Regardless this move cements Nvidia’s strategic position in inference (where hyperscaler ASICs were a former long-term bear case).
↗ Quoting @workerlucky777
$NVDA$MRVL$AVGO$NBIS$CRWV$AMD
@balllvest With how the trends are going with $MRVL and Mediatek. My guess is Alchip (disclosure, I own this) or $QCOM might be next.
I think the ASIC pie gets bigger for all of them though.
$MRVL$2454$3661$QCOM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MRVLlong |
-0.6% | +5.6% | +24.8% | — | +24.8% |
| $QCOMlong |
-2.3% | -0.5% | +8.5% | — | +8.5% |
| $2454long |
| | | | |
| $3661long |
| | | | |
@Matrix_B0SS I actually learned today that Mediatek is partners with Ayar for CPO (not just investors) from public filings.
And of course it's known that $SIVE is the primary laser supplier to Ayar. But Sivers is probably too far upstream for now.
$SIVE
Today, $NVDA has announced a $3.5B investment into Mediatek.
It appears Nvidia is "networking" itself into the broader ASIC ecosystem, from $MRVL to MediaTek.
And have future ecosystems aligned with Nvidia standards. (maybe to fend off $AVGO as well)
$NVDA$MRVL$AVGO$2454
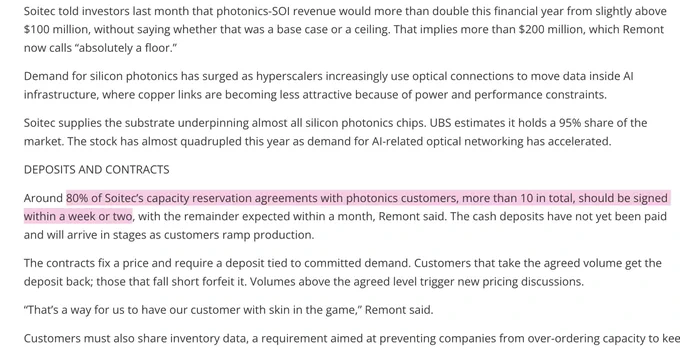
Remember my $SOI thesis anon? Soitec interview commentary today:
- 80% of capacity reservation agreements expected within 1-2 weeks, with more than 10 in total.
- $200M Photonics-SOI revenue now described as "absolutely a floor"
$TSM also sees SiPH going mainstream in 2027 with market share topping 50%+ of the optical transceiver market
If you hold a monopoly-like position over a chokepoint:
(UBS estimates Soitec has 95% share of the market for substrates underpinning silicon photonics chips)
Revenue usually flows through you.
$SOI$TSM
“Memory is a bubble.”Explain this then, KOSPI bears:
Samsung has reportedly reserved ~70% of its memory production capacity through 2031 via LTAs with $NVDA, $MSFT, and $GOOGL as main counterparties.
Five years of demand visibility…
$NVDA$MSFT$GOOGL$SSNLF$SKHY$KOSPI
Imagine Celestial ($MRVL acquisition) was public.
The valuation would probably be astronomical in US markets (if I had to guess, $6-10B)
Because 2028 revenue projections were $500m (q4 annualized runrate), 2029 revenue projections were $1B.
And because Celestial is a core part of hyperscaler CPO programs.
Celestial's 2026 Q2 earnings would have been:
- Close to $0 revenue (Marvell said "revenue and earnings since the acquisition were not material")
- Losing -$12.5M/quarter ($50M/year)
Would people who knew what they were talking about looking at qualification cycle players say...
1. based on Celestial's Q2 P/S numbers and because it was losing -$12.5M a quarter... That it's a worthless meme stock?
Or
2. with CPO hyperscaler opportunities for 2028, it should be valued at $6-10B?
And I think that's a core cultural disagreement between US / EU cultures + markets.
If you knew how to evaluate qualification cycle players, which number actually matters? I'd argue overwhelmingly the latter.
$MRVL
Yes, I added that as a side note. But my theory is $RPI eventually gets the overflow from mac Mini shortages.
Same idea with Openclaw now applied to frontier lab agent RL training.
And those sales would be economically meaningful given Raspberry Pi’s size relative to Apple
No proof of that yet, just a guess.
$RPI$AAPL
@jukan05 Yep, reasonable point on the duration. I just found $AAPL AI windfall to be pretty amusing.
$AAPL
$AAPL is now an important AI company apparently?
-> "OpenAI Hoarding Tens Of Thousands Of Apple Mac mini and Mac Studio" for reinforcement learning
-> Anthropic is renting Apple Mac mini units from $AMZN to complete similar AI tasks
I've never seen a company win so hard by doing nothing.
But whenever I see Apple + AI, I think of my beloved $RPI. Apparently Anthropic is working with Raspberry Pi now for their new model Hardware Standard, as of the 27th.
There's nothing yet about Anthropic/OpenAI buying Raspberry Pi devices for similar tasks, but maybe some OSINT researcher can do some digging.
$AAPL$AMZN$RPI
@nosignal62478 I think $AAOI is fine. I didn't list them here because they're not known to be a merchant cw laser supplier (given they use them internally for transceivers).
Demand visibility into 2027 is incredible, there's just a $600m ATM, which presents a lot of short term overhang.
$AAOI
@SidkMena Yeah, I was forced to averaged down during that massive July sector crash.
Now up ~55% on FOCI and ~50% on Xintec at least but some of my other names are still recovering
$FOCI$XINTEC
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $FOCIlong |
| | | | |
| $XINTEClong |
| | | | |
$TSM Vice President of Advanced Packaging:
"Foundries can scale up the optical engine, but the real bottlenecks to large scale deployment lie elsewhere...
Including lasers, optical fiber, fiber-optic connectors, and test" (UDN)
Just some bucket ideas:
Lasers: $LITE, $SIVE, $COHR, LandMark (3081), LuxNet, Sumitomo, Furukawa
Optical fiber / FAU: Foci, Browave, $GLW, Sumitomo
Fiber Optic / CPO Connectors: BizLink, $GLW , Fujikura, Nextronics, COXOC
CPO testing: MPI (6223), Advantest, $FORM, Msscorps, $KEYS, Chroma
(disclosure: exposure to theme above, individual names not named by TSMC)
There are others I like as well, such as ShunSin, which now has explicit TSMC COUPE exposure but probably belongs under a different category like packaging/integration.
eg. "Foxconn unit ShunSin confirms TSMC COUPE partnership"
I don't think there's anything too new vs. H1, aside from ongoing news (eg. FAU looks like there will have a demand imbalance in 2027, from a report last week).
But it's helpful to reiterate overall beneficiaries from time to time...
$TSM$LITE$SIVE$COHR$GLW$FORM$KEYS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $COHRlong |
-2.1% | +1.5% | +3.6% | — | +3.6% |
| $FORMlong |
-5.2% | +3.3% | +48.5% | — | +48.5% |
| $GLWlong |
-2.1% | +3.7% | +3.4% | — | +3.4% |
| $KEYSlong |
-1.1% | +1.4% | +12.8% | — | +12.8% |
| $LITElong |
-5.0% | -3.7% | +6.1% | — | +6.1% |
| $TSMlong |
-0.3% | +3.3% | +10.1% | — | +10.1% |
| $SIVElong |
| | | | |
ESMT (3006) is 1.9x P/E ratio off July's earnings annualized.
Latest net income was: $109M net income/July, which is ~$1.3B annualized. With ~$395.9M net cash and with $249.6M in inventory.
The market cap less net cash and inventory is equivalent to:
~17 months of July earnings.
Where monetizing that inventory benefits from rising memory prices.
Their ASP hike expectations were +105–113% Q/Q last quarter from other analyst notes.
DDR2/DDR3, NOR Flash, SLC NAND, prices are expected to keep rising H2.
The main question is duration, but I personally think legacy DRAM/NAND shortages tightens throughout 2027. Others might disagree.
Other analysts like Huanan argue that PSMC wafer hikes are largely pass through (we'll find out H2).
Most people are finding companies with ~20 forward P/E ending 2028 to be attractive...
But 1.9x current runrate P/E seems like an anomaly to me personally.
That's my take on the company/legacy memory theme, I'll let others/markets decide if that's undervalued.
↗ Quoting @ShrugFred
$ESMT
I'm going to miss the days of Korean retail reacting heavily to $EWY / Samsung / $SKHY daily volatility.
New piece: "Korean day traders flee leveraged chip ETFs as regulatory curbs bite"
- Trading value in ETFs designed to deliver 2x daily returns of Samsung / SK Hynix has fallen to just 4% of its June peak
- The requirement follows earlier measures, including a higher minimum deposit, aimed at cooling speculative activity
- And then came the final boss... A 5 day trading course where:
"Investors must download a Windows-only program and spend at least one hour each day trading with virtual funds"
$MSFT Windows wiped out the Korean retail.
$EWY$SKHY$MSFT
@Myv3rz 如果你在 $IBKR 搜尋 <3006>並啟用台灣證券交易所,就可以找到。
不過這不是投資建議。
$IBKR
The more I look at ESMT, the more excited I get researching legacy memory themes.
So looked through H1 sellside models...
From March ESMT reports:
Huanan: DDR3 4Gb ASP +50% QoQ in Q2
Fubon: cited roughly +40% Q2 DRAM pricing
By August... Huanan was citing ESMT Q2 ASP growth of:
+105–113% Q/Q blended.
Saying DDR3 pricing had come in substantially better than expected.
So legacy memory pricing translated into much more operating leverage at ESMT.
About PSMC wafer cost hikes: Huanan estimated manufacturing costs could rise ~100% in 2H26, but customers remained highly willing to accept the pass-through
If we look at July net income was roughly $109M... way above the earnings levels the earlier models were built around.
If I had to give a TLDR "consensus" of reports
1. DDR3/DDR2 supply remains structurally tight as competitors move capacity toward higher-value memory.
2. Concord saw no conditions supporting a price reversal during 2026.
3. Concord expected contract-price increases to cover higher foundry costs.
4. Huanan later found that customer willingness to accept those cost increases was stronger than expected.
Fun thing I read from Huanan was DDR3 is used in products such as IP cameras and HDDs where the memory component is a relatively small part of the customer's total BOM.
So even very large legacy DRAM price hike may only add a few dollars to the finished product's BOM... and for many customers, paying a few extra dollars would be more economical than redesigning + requalifying (but this flows materially into ESMT's net income)
Anyway, just excited about this idea (*disclosure I have positions)
TLDR:
-> Huanan updated ESMT blended Q2 ASP to +105-113% Q/Q
-> Given July's blowout net income (putting ESMT at 1.9x p/e annualized RR), implications for the future are exciting if inelasticity continues + ESMT has the ability to hike further due to low % of finished product BOM cost.
-> Indication customers were still willing to accept pass through for PSMC wafer hikes.
↗ Quoting @QQ_Timmy
$ESMT$PSMC
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $ESMTlong |
— | — | — | — | — |
| $PSMClong |
| | | | |
Just some random ideas from Elon’s post:
$AAON - Chillers / liquid cooling
$NVT - Cooling
$MOD - Chillers / Cooling
$IESC - Wiring
$MTRS - chillers
$JCI - chillers
$HPS.A - Transformers (disclosure I own positions in this)
$PRY.MI - networking/wiring(fiber)
$CRDO / $AAOI (same) / $LITE / $COHR - networking
Since Elon Musk cited:
- transformers
- wiring
- liquid cooling
- massive chillers + complex networking
As the point of failure for AI compute buildout.
Which is “harder than finding power”
↗ Quoting @elonmusk
$AAON$NVT$MOD$IESC$MTRS$JCI$HPS.A$PRY.MI$CRDO$AAOI$LITE$COHR
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+1.4% | -0.7% | -4.5% | — | -6.6% |
| $AAONlong |
+0.1% | +4.8% | +17.6% | — | +9.2% |
| $COHRlong |
-0.5% | +1.0% | +6.0% | — | +3.1% |
| $CRDOlong |
-2.8% | -26.7% | -9.4% | — | -16.3% |
| $IESClong |
-2.2% | +4.1% | +4.6% | — | +3.7% |
| $JCIlong |
-1.0% | +3.8% | +7.9% | — | +6.8% |
| $LITElong |
+2.2% | -1.5% | +5.2% | — | +8.4% |
| $MODlong |
+0.5% | +9.6% | +11.5% | — | +5.4% |
| $NVTlong |
+1.5% | +5.1% | +10.7% | — | +8.0% |
| $HPS.Along |
| | | | |
| $MTRSlong |
| | | | |
| $PRY.MIlong |
| | | | |
@Omardrisss There’s bubbles within the broader AI supercycle (eg. frontier lab valuations, some Neoclouds).
And some pop here and there.
But the overall theme with $NVDA and $TSM in the center of it all looks structural and would keep ramping up.
$NVDA$TSM

 @aleabitoreddit
Aug 31, 2026 · 20:53 ET
stock