Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
Yes surprised in a very good way, the amount of laser capacity $SIVE is targeting is enormous.
And Q4 2027 operation is a lot sooner than I expected (around initial cpo scale up laser shipments)
During shortages, I expect western laser ASP to have stronger pricing power as well.
$SIVE
@Sigurd_Drivenes I’m glad management finally provided clarity on their long term goals.
Changed my negative view about their hybrid manufacturing model capex given new capacity targets.
$SIVE
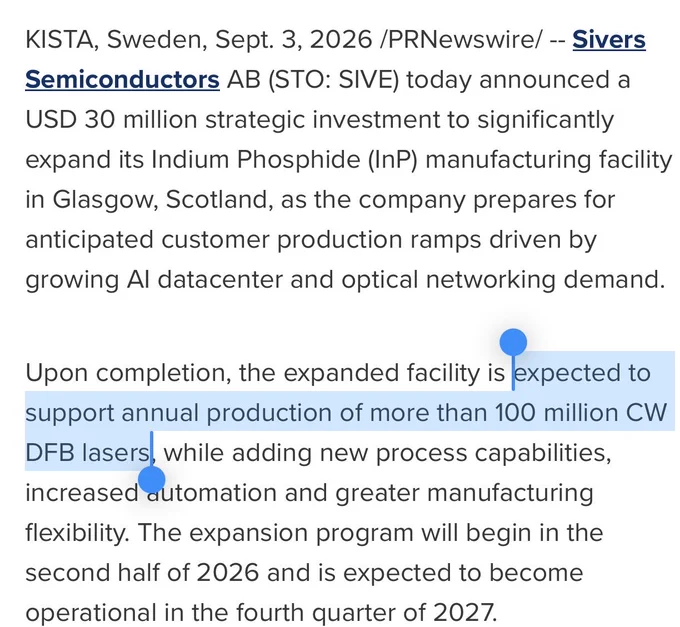
$SIVE announced today that it is expanding InP manufacturing in Glasgow.
The new capacity target is:
~100 million CW DFB laser annual production.
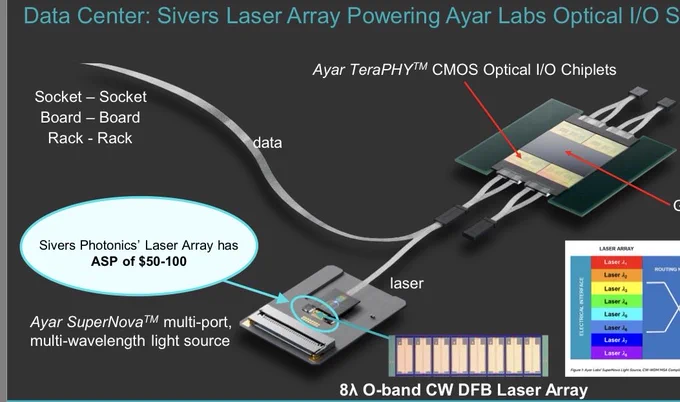
Using Sivers’ historical $50-$100 per 8-laser array pricing, the implied revenue capacity might be ~$625M-$1.25B/year (not guidance, just illustrative modeling)
I’m personally very surprised by the amount of capacity coming online from their new hybrid manufacturing model, targeted Q4 2027.
Especially during an industry shortage, mentioned by $AVGO earnings call today.
$SIVE$AVGO
@wannabepanacea If you're not capacity constrained and growing 70-100% a year like $NVDA or $AVGO, apparently you'll get sold off on earnings.
Will take a look at $CRDO earnings in a bit, there's quite a lot of companies to track.
$NVDA$AVGO$CRDO$FCEL
$AVGO CEO: "Demand for lasers, whether it is EML lasers, CW lasers.
Is far surpassing supply out there in the industry"
Pretty material coming from one of the largest laser suppliers in the world... Even while they 3x laser capacity.
Exciting validation for laser companies. https://t.co/l4alSsexMT https://t.co/SF1OTJfhZi
↗ Quoting @aleabitoreddit
$AVGO
There we go, $AVGO earnings call to clarify miss. Broadcom expects:
FY27E: ~$115B (+100% growth)
FY28E: ~$230B (+100%), think analysts were modeling ~$180B.
Demand actually exceeds this outlook, and Broadcom will work to improve supply. This is way above street estimates, similar to $NVDA earnings.
"very much on target to exceed $30 in earnings per share in fiscal 2028." ~12.2x forward p/e (of $367/share)
Also just a brownie quote: "AI networking revenue is expected to grow just as fast as XPUs over the next few years."
Way more bullish forward guidance relative to next soft quarter revenue projections, think the few percent AH selloff was an overreaction.
Just my initial thoughts.
$AVGO$NVDA
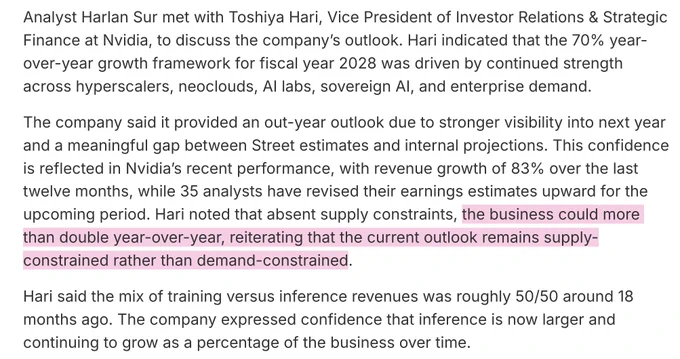
$NVDA told JP Morgan... That their revenue could increase more than 100%+ Y/Y unconstrained.
But ended up giving a ~70% growth projection because that's what Nvidia believes they can supply.
FY27 est: ~$401B revenue...
FY28: ~$682B at 70% or >$802B unconstrained.
- Nvidia IR said it gave the updated outlook because it had greater visibility + saw a meaningful gap between Street ests. and its own projections
- Inference is now larger than training after being roughly 50/50 about 18 months ago
I wonder if Nvidia will be the first $10T company... this growth is absurd.
$NVDA
Supplier relationships are not going to be public, which is why it's fun looking into these clues.
I just found it very interesting $MRVL optical program lead had Europe in mind for laser supply sourcing.
It's like if they randomly named dropped Africa for supply chains, probably not many players to choose from there.
Maybe innolume is the other private player I can think of? but they're much smaller
$MRVL$SIVE
$MRVL SVP and CTO of Optical Engineering Radha Nagarajan, at Semicon Taiwan:
1. Names Europe/Japan for laser supply sourcing as examples for SiPH modules.
Very interesting that Marvell's SVP had Europe in mind when giving examples of laser supply sourcing for SiPH modules.
I can't really name any notable public EU merchant laser suppliers other than $SIVE. Japan I can namedrop a few like Sumitomo/Furukawa etc.
Maybe I'm reading too much into the geography, but a lot of US players like $LITE / $COHR / $AAOI are redirecting laser capacity internally, so it's interesting that the US wasn't mentioned.
2. Silicon photonics, high-speed drivers, amplifiers and DSPs come from other suppliers, with final integration taking place in Taiwan
Makes sense, with $TSM COUPE / $ASX / ShunSin, and others.
3. Nagarajan appears to say NPO could arrive first around late 2027–2028, with full CPO continuing afterward.
Good to hear more about commercialization timelines.
$LITE similarly sees NPO around late 2027-H1 2028, while expecting CPO laser shipments in H2 2027 ahead of CPO scale up deployments in 2028.
Revenue from upstream suppliers usually hits a bit earlier.
4. $MRVL on Google's TPU program vs. $AVGO / Mediatek and others.
"Hyperscalers are seeking greater supply-chain diversification. If Google selects Marvell for a particular AI-chip segment, that does not mean it will stop working with MediaTek or Broadcom".
Guess he's just trying to emphasize pie keeps growing for ASIC suppliers, nothing really too new.
5. All of Marvell's advanced ICs and ASICs are manufactured at TSMC, making the foundry central to the broader architecture.
$TSM backbone of AI as usual.
TLDR:
- Very odd Marvell's SVP highlights Europe for laser sourcing, given how small a pool for merchant suppliers there is...
- NPO volume looks late 2027, CPO after that. Upstream optical suppliers should start seeing revenue earlier
$MRVL$SIVE$LITE$COHR$AAOI$TSM$ASX$AVGO$GOOGL$NVDA
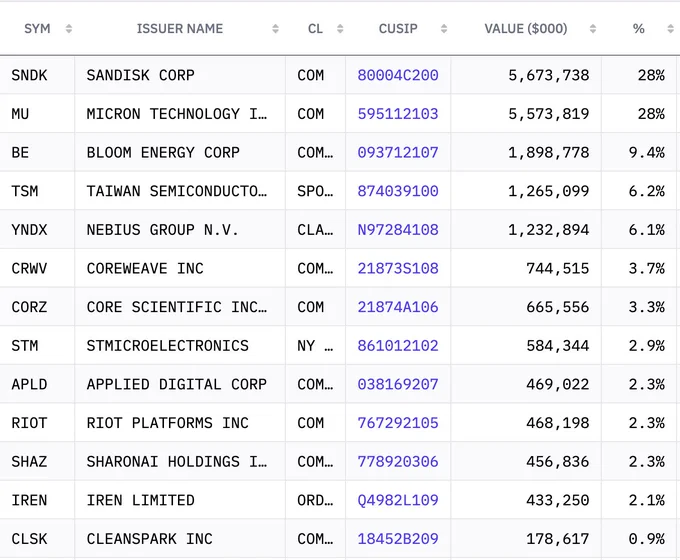
Just taking a look at Leopold's Situational Awareness Q2 13F latest holdings as of June 30th:
1. $SNDK - $5.674B
2. $MU - $5.574B
3. $BE - $1.899B
4. $TSM - $1.265B
5. $NBIS - $1.232B
6. $CRWV - $744.5M
7. $CORZ - $665.6M
8. $STM - $584.3M (new)
9. $APLD - $469.0M
10. $RIOT - $468.2M
11. $SHAZ - $456.8M
12. $IREN - $433.3M
Less material positions includeed $CLSK, $KEEL, sei-network:native, $WYFI, $BTDR, $TE, $HIVE, $VSH, and others.
Seems like Situational Awareness concentrated around memory (Sandisk, Micron), that have low forward multiples but high visibility into 2030.
As well as Anthropic/energy/power adjacent from colo/neoclouds + Bloom.
Some of the bottlenecks like the MLCC trade, he couldn't see play out (Taiyo Yuden, etc). due to July's liqudation. And some are new like $STM (eg. MCU price hikes).
With core winners of everything such as $TSM (but less high-beta).
This looked similar to my H2 2026/early 2027 portfolio with Nebius, Micron, TSM, colo players and others as core focus. (I've heavily concentrated on upstream networking/legacy memory currently, with a lot of name overlap).
But always cool to see what others are doing.
$SNDK$MU$BE$TSM$NBIS$CRWV$CORZ$STM$APLD$RIOT$SHAZ$IREN$CLSK$KEEL$SEI$WYFI$BTDR$TE$HIVE$VSH
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $APLDlong |
+4.0% | +9.0% | — | — | -2.2% |
| $BElong |
+8.4% | +23.9% | — | — | +27.5% |
| $BTDRlong |
+10.9% | +14.8% | — | — | -2.3% |
| $CLSKlong |
+11.0% | +17.2% | — | — | +13.6% |
| $CORZlong |
+6.5% | +7.6% | — | — | -4.9% |
| $CRWVlong |
+4.5% | +17.3% | — | — | +7.6% |
| $HIVElong |
+12.1% | +14.0% | — | — | +8.3% |
| $IRENlong |
+5.2% | +14.6% | — | — | +3.2% |
| $KEELlong |
+7.7% | +19.3% | — | — | +13.7% |
| $MUlong |
+0.2% | +7.5% | — | — | +11.8% |
| $NBISlong |
+3.2% | +17.8% | — | — | +15.6% |
| $RIOTlong |
+13.4% | +18.4% | — | — | +8.1% |
| $SEIlong |
+0.5% | -3.5% | — | — | +48.9% |
| $SHAZlong |
+1.3% | +4.5% | — | — | +0.8% |
| $SNDKlong |
+0.1% | +13.6% | — | — | +12.0% |
| $STMlong |
+1.1% | +1.7% | — | — | +5.4% |
| $TElong |
+6.3% | +15.0% | — | — | -9.6% |
| $TSMlong |
+0.4% | +4.8% | — | — | +10.0% |
| $VSHlong |
-0.5% | +3.5% | — | — | +6.7% |
| $WYFIlong |
+8.5% | +11.6% | — | — | +4.1% |
@dockery58 Yeah, CPO volumes haven’t even started… everyone forgot that $SIVE was a major CPO laser supplier because management focused so much around wireless/5g/fwa/satcom.
Pluggables like $JBL were supposed to be the bridge for 2028 CPO ramp but somehow became the dominant focus.
$SIVE$JBL
I want as much % ownership of the companies that lead AI’s next architectural shift as possible.
Not optimizing for USD returns at this point since even if Sivers goes to $0, I’d be completely fine.
Also my thesis was for H2 2027 for CPO scale up, not August 2026 wireless revenue.
There’s still time for management to reorganize, and I think this crash sends a good message.
$SIVE
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $SIVElong |
| | | | |
I don’t want to play investor activism here:
But I hope the recent crash sends a message to $SIVE what investor base + focus really matters (not Sweden, not wireless).
As well as that they should fire whatever board member or executive gave into local media criticisms:
And told the CEO to prioritize on non-photonics / near term revenue, since the discussions was on AllSpace + pipeline conversion now. Not Ayar/GFS and H2 2027/2028 opportunities.
It’s not hard to set clear future goals like NASDAQ listing filing by H1 2027 and use all your resources to execute on that.
Not vague post and language hedge like no-growth conservative companies do.
I’d argue this is better long term so they consolidate around:
NPO/CPO, US funding, and forward vision + execution through scaling/M&A.
Including divesting wireless/satcom/5G to 100% focus on photonics, if those are redirecting priorities.
I’m still holding my 1M+ share count position but not going to blindly cheerlead or hold a company if they become misaligned on what I originally invested in them for (CPO).
↗ Quoting @elpidalymp33598
$SIVE$GFS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $GFSlong |
+1.3% | +4.5% | — | — | +9.3% |
| $SIVElong |
| | | | |
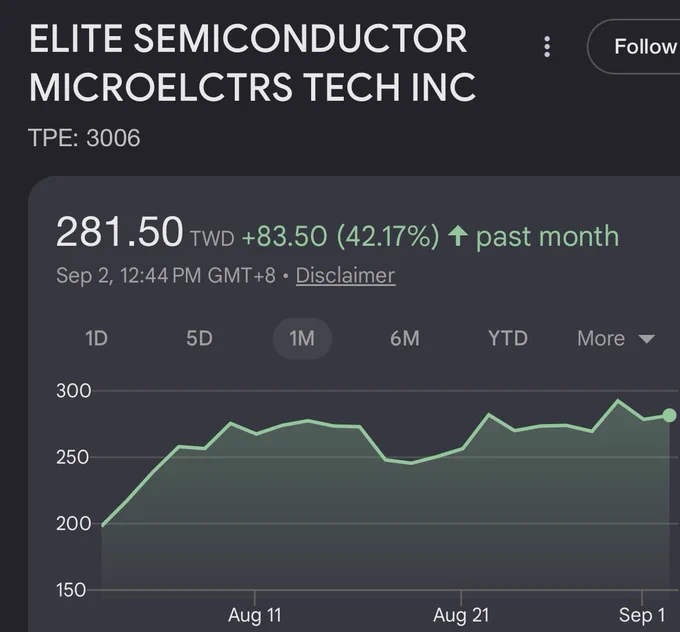
Very interesting to notice Taiwan wildly outperform the rest of the World like US/EU.
Foci ($NVDA / $TSM FAU supplier) went from 400 -> 900 -> 400 -> 800, and recovered insanely fast from July.
Not sure if earnings like Etron or others are just absurd to not care about macro?
$NVDA$TSM
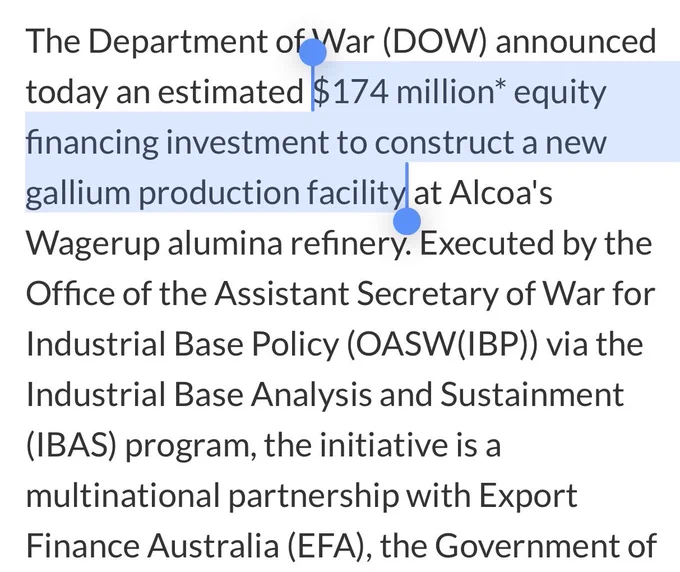
US Department of War announces $174M financing for securing Gallium Supply Chains. Beneficiaries are:
- $AA (Alcoa Corp) for Gallium production at its refinery.
- Sojitz (2768) as the Japanese JV offtake partner
Good to see US critical minerals supply chains investments.
$AA$2768
After seeing everything from $AXTI to $IREN get nuked… I’m starting to believe in the:
“September is the worst month of the year” myth.
$AXTI$IREN
I don’t want to be on any board or be an activist investor, pls stop recommending me lol!
I’m just putting out my thoughts on how I see them become a $LITE type company, and operationally they’re in an amazing spot.
In the end, it all comes down to the leadership’s execution on their vision, and that part is out of my hands.
I’m still holding my positions, but people should make their own judgement on what they see happening.
$SIVE$LITE
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $LITElong |
+0.2% | +12.6% | — | — | +11.7% |
| $SIVElong |
| | | | |
@johnternus Good first day at work
$AAPL
@GGFitim1 Definitely not! But this is just as amusing to me as that shoe company $BIRD becoming a neocloud.
$BIRD
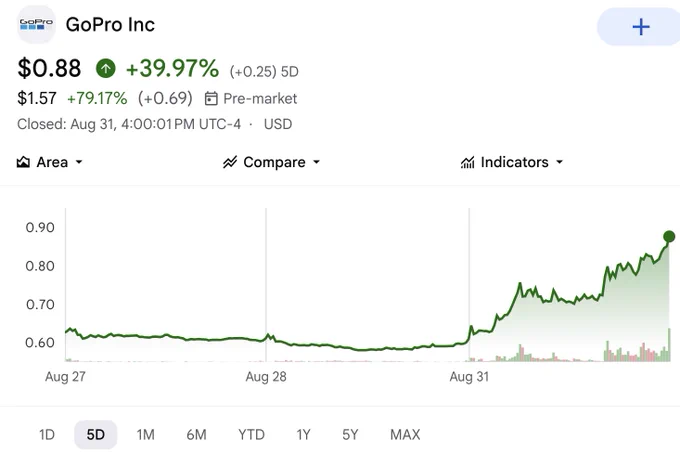
What... $GPRO is up 79.17% after planning to merge with a photonics company "Starman Optical"
To build US 800G/1.6T optical transceivers for AI data centers.
GoPro trying to compete with $AAOI was definitely not on my radar.
$GPRO$AAOI
I can’t give advice over what people should do with their trades.
Personally speaking, I think $AAOI outperforms in 2027 and the $AXTI InP substrates bottleneck/chokepoint got validated.
With AXT it’s more of a matter of ASP hikes moving forward with their agreements like $LITE and $COHR. AXT is negatively affected by high beta AI sector selloff recently with macro.
AOI has a very disappointing $600m ATM so that’s a lot of near term overhang. But doesn’t affect their 2027 transceiver demand visibility and they should finish 1.6T qualifications soon.
Past 2 month has seen major corrections, but there’s a lot of opportunity too depending on what you find compelling
$AAOI$AXTI$LITE$COHR
@Bejewele_din_Fr - Nvidia likes investing in ASIC companies
- Memory/MLCC/ABF/SOI brrr from long term visibility
- legacy dram to brrr from Chinese memory moving to higher end
- China EU fighting over companies
- cpo timeline in tact
- planetary roller screws in robotics are cool
$NVDA
Bit of both, mainly around communication.
Operationally things look ideal, they have Jabil, globalfoundries, Ayar, and ~6 pluggable engagements, with 2 foundry capacity during a major bottleneck.
$JBL timelines were in line with what I expected.
But communication focused around focused on near term wireless/revenue + financials to appease local investors.
Instead of significant future economic opportunities for CPO/others.
Communication was also horrendous and noncommittal, especially around Nasdaq listing compared to two months ago.
This was the only material delay I’m very unhappy with, since it’s an execution failure despite having the 57 SEK institutional fundraising round.
And the legal language that the CFO added just introduces uncertainty for no reason, when there wasn’t much before then.
Market definitely not hestitate sending sivers down 28% from that stupid language hedging
$SIVE$JBL$GFS
Management feels increasingly misaligned with my expections
Sivers could use the current bottleneck to radically restructure around photonics. Use US capital to speed up timelines, and leverage NASDAQ for further growth with 1.6T/CPO.
But got no sense of urgency, especially on listing timelines.
I also genuinely don't understand continuous emphasis on SATCOM/Wireless which would be better off divested. Or the near term contract values that are invisible relative to photonics TAM.
Not a single mention of Ayar, globalfoundries, and any other big program that US investors care about.
$SIVE
Just some TLDR news I found interesting:
1. $GOOGL (missed this) also invested in Mediatek alongside $NVDA for their $3.9B raise.
Google/Nvidia are goats with investments you look at $SPCX to Anthropic.
2. Samsung Electro-Mechanics discloses $778.9M MLCC deal / $CAPA (new MLCC ETF) also gives exposure now for folks without Korea/Japan/Taiwan market access.
But thing is more accelerators x MLCCs per accelerator might indicate a more future extreme bottleneck than people expect.
3. China channel checks state: planetary roller screws, 6D force sensors, and dexterous hands resist domestic substitution.
Then planetary roller screw as the top with lowest domestic substitution rate. eg. $SHA0.DE for planetary. Just interesting to hear moats I guess.
4. Samsung reportedly has ~70% of memory production capacity committed through 2031 / commodity DRAM has also fallen into short supply - Seoul Economic Daily. TrendForce expects server DRAM contract prices to rise 13-18% QoQ in 3Q26
SK Hynix also publicly stated the memory shortage lasts through 2030.
5. $CXMT has begun producing HBM3E in small quantities and reportedly claimed mass production of LPDDR6. Implications are even more positive for legacy DRAM shortages.
6. Cisco at SEMICON Taiwan said CPO is ready for mass deployment; pluggable modules will remain the market mainstay.
$MRVL also said customers are actively planning scale-up optics deployments as early as 2027
7. Wingtech -> bought Nexperia -> Netherlands effectively removed Wingtech’s control -> Wingtech is fighting back through Chinese courts.
But Nexperia got $300m of their assets frozen.
More geopolitical drama of course, always entertaining. $AAPl also explicitly accused OpenAI of destroying crucial evidence... (for more fun)
8. Not much description around ASP hikes regarding SOI substrates $SOI, but they now have 10+ customers involved with LTAs, $200m revenue described as a "floor", comments about customers more concerned about obtaining wafers than where they are manufactured.
So basically moving into capacity reservation now stages as silicon photonics takes off in 2027.
9. Some channel checks put lead times for high power MOSFETs and large area TVS diodes as high as ~52 weeks. ($STM also reportedly implemented its 3rd 2026 price increase on August 23)
10. Traditional packaging capacity could face a deficit exceeding 20% by 2027" with "wire bonding equipment" emerging as the primary bottleneck", covered this earlier this week with beneficiaries like
11. Claims that all six major ABF suppliers are booked for 2026, with 12-14 month lead times and some suppliers auctioning remaining capacity; $NVDA, $AMD and hyperscalers locking ABF capacity through 2028 and pushing suppliers to plan 2029–30 expansions.
Names like Kinsus (3189), Unimicron (3037), Nan Ya PCB (8046), Ibiden (4062), etc are all probably happy.
12. CCL leading laminated board products increased by another 10%-20%, 7th price hike this year (eg. Kingboard). Industry estimates put the HVLP4 copper-foil shortage at ~48% in 2026 / 43% in 2027, while Low-Dk/T-Glass lead times have stretched beyond 30 weeks.
13. "(GaAs) substrate materials and gallium epitaxial source materials are also facing another round of price increases in the third quarter of 2026, reportedly 5 to 6 times higher than at the early stage of the restrictions."
"China has recently eased some substrate export controls" but there's a "severe InP substrate shortage" per digitimes. Just some $AXTI related updates
14. $AMD and $AVGO reportedly booked most of Powertech's planned FOPLP capacity ahead of mid-2027 mass production
15. $INTC considering $INTC foundry for HBM4E base dies. But $SKHY responded directly that "some of the content is different from the facts".
16. "OpenAI Hoarding Tens Of Thousands Of $AAPL Mac mini and Mac Studio" for reinforcement learning. Anthropic has been renting mac mini units from $AMZN as well. Kinda sad Tim Cook retired, but dude had a goated run.
Just random interesting notes
$GOOGL$NVDA$SPCX$CAPA$CXMT$MRVL$AAPL$SOI$STM$AMD$AXTI$AVGO$INTC$SKHY$AMZN$SHA0.DE

 @aleabitoreddit
Sep 03, 2026 · 06:20 ET
stock