Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
@demarscrypto $RDDT S&P 500 inclusion go brrr
$RDDT
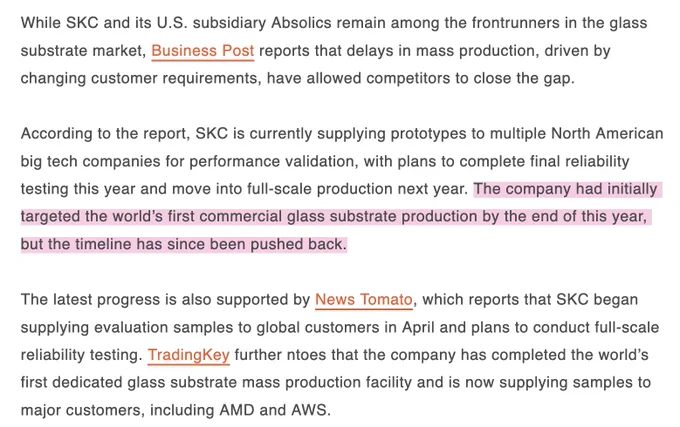
Feels like glass substrate timelines got pushed back at least another quarter.
- "Samsung Electro-Mechanics Delays Semiconductor Glass Substrate Investment" due to a bottleneck in customer reliability evaluations of prototypes.
At its recent second-quarter earnings presentation, less than a month later, the company revised the start of operations to 2028.
- "SKC Reportedly Pushes Glass Substrate Mass Production to 2027, Targets Final Validation by Year-end" (Trendforce), earlier last month.
TLDR:
- SKC Absolics H2 2026 -> H1 2027
- Samsung H2 2027 -> H1 2028
Not everything is always good news with timeline shifts, but glass core substrate shifts do feel imminent.
Volume ramp for some players eg. $LPK / Philoptics (161580) / E&R (8027) likely track these mass production timelines.
$LPK
@Highonstocks_ Yeah I personally bought $SMCI on earnings day after I saw the guidance.
At a certain point, hairdryers should only weigh down a stock so much right?
$SMCI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $SMCIlong |
+1.7% | -6.8% | +2.4% | — | +4.9% |
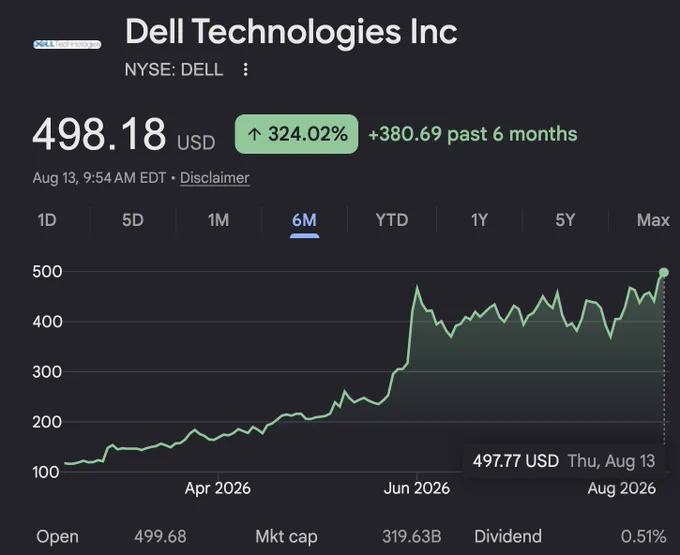
In another world, $SMCI would look more like $DELL?
If they didn't try smuggling $NVDA GPUs using hairdryers...
Regardless, SMCI guiding $65-72B FY 2027 revenue off a ~$25B MC is pretty crazy the more I look at it.
$SMCI$DELL$NVDA
@Papsytwinz Uhh nothing really too interesting aside from a new $2.3M purchase order for $POET
Will need to wait for earnings call.
$POET
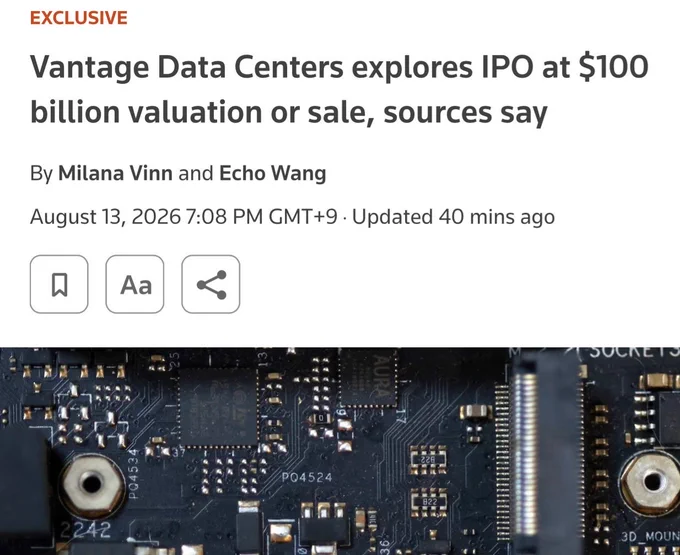
In IPO news… Vantage Data Centers is exploring going public at an enormous $100B valuation.
If you’re not familiar, $ORCL is their anchor tenant for Stargate (OpenAI end user), and Vantage develops/operates hyperscaler DCs.
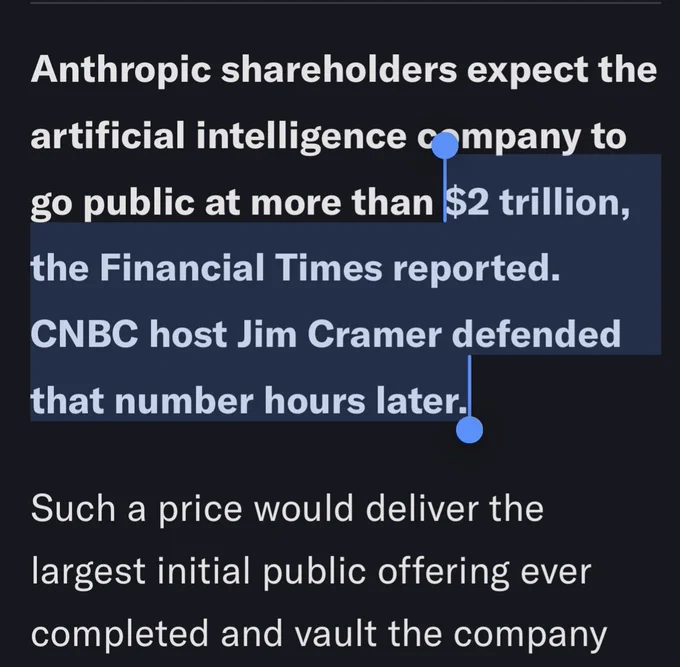
Anthropic IPO is also expected, with investors expecting $2T valuation, eclipsing $SPCX per FT.
Yeah… idk about Anthropic valuations. Jim Cramer defending that valuation is never a good sign.
On a side note, Opus 5 is probably the worst consumer LLM I’ve used to date, it’s like a 5 IQ LLM operating off terrible data retrieval. With a Fable-like God complex on top.
Enterprise is probably having a better time though.
Unitree IPO is also expected this month and priced it at a $9B valuation. Which is a positive tailwind for Unitree for the humanoid sectors.
Not really an AI name but SHEIN is going public as soon as the 19th this month.
Go ask any girl you know and they’re probably familiar with this platform.
$ORCL$SPCX
I'm not sure if it's just me, but I'm just seeing enormous CW demand imbalance right now (thank you $NVDA).
And this is before scale up and other 1.6T ramps even arrive. Then you have $AAOI and $SIVE appear with scarce, independent CW laser or transceiver capacity...
That usually leads forces your other major players like $AMD and hyperscalers to look at them. $MTSI said their capacity only starts to come online H2 2027 and customers are already approaching them with urgency...
CW lasers is one of my favorite bottlenecks right now.
$NVDA$AAOI$SIVE$AMD$MTSI
@dra99aso I usually just post research along the way as new news comes out (eg. Lumilens $5.5B valuation announcement + hyperscaler contracts).
But I'll drop it in disclosures if I have a position on something like $POET or $SMCI earlier. Maybe I'll do a roundup TLDR later.
$POET$SMCI
If I had to categorize it:
$SIVE = Waiting for Revenue Conversion
Tons of hyperscaler suppliers + demand visibility for the CW DFB. How do markets want to price in or assign a premium on the waiting game for 1.6T H1 2027 to CPO scale up for H2 2027?
$AAOI = Waiting for Capacity Execution
Extreme demand visibility for transceivers. Can they ramp up capacity to meet their $471m/month projections?
$POET = Waiting for Customers
Too much cash relative to MC + heavily funded supply chain capacity setup, little demand visbility.
$SIVE$AAOI$POET
Okay here's my take on $POET, since apparently people are celebrating on the subreddit that I took small positions.
- I have 0 idea. ZERO. How they convinced shareholders to allow them dilute SO MUCH to the point:
They have an absurd ~$830m cash on hand now.
And my guess is that they're close to done, since I would be in disbelief if they needed more.
So now... they have ~$830m to grow their business like M&A, and EV actually dropped really low recently (eg. $1.25B MC vs. $830m cash on hand), that I thought it was compelling to take a risk.
- Annualized production capacity target is 12M optical engines/year for 2027, which is pretty absurd ramp.
Need to do more research into ASP for Poet's products, but maybe $125-$200? So at ~$150 ASP, $1.8B revenue ceiling.
But they're like inverse AAOI right now: no visible demand to fill all that capacity. Aside from Lumilens, which is now a highly valued hyperscaler supplier (probably Amazon or Microsoft), with billions in customer agreements.
The interesting thing is if Poet signed prepayment EML agreements with players like Mitsubishi, or CW agreements with Sivers behind the scenes with that balance sheet.
And given the current bottleneck, players might use Poet as a workaround for supply procurement.
But basically, you have a super cash-rich company with a ton of capacity coming online. And they're not really disappearing anytime soon with their financials.
I don't quite think it's as technically defensible compared to upstream laser chokepoints with something like $SIVE around the same valuation in terms of technical moat for CW lasers vs. OE packaging side. As you've seen recently with Celestial and Poet.
But maybe... there's a chance some hyperscaler or downstream company announces a volume agreement sometime in the future. and $POET takes off. And they do have the supply chain setup for ramp with that.
That's the risk I ended up taking, but it's not exactly a clear as day long for me like $AAOI.
↗ Quoting @liulu1537335
$POET$SIVE$AAOI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AAOIlong |
+15.5% | -0.8% | -19.0% | — | -23.7% |
| $POETlong |
+7.5% | -7.2% | -10.8% | — | -16.0% |
| $SIVElong |
| | | | |
Feels like my $IQE thesis Feb this year got validated alongside $AXTI and others. (I still long on both)
So I stopped covering them as much. But TLDR on updates:
Early this year, IQE was a distressed but critical chokepoint in the optical supply chain with links to $LITE and others when I published my thesis on it.
Since then:
- $MTSI signed long term epiwafer supply agreements, took a stake in the company, now IQE is bank debt free (Macom has convertibles, but that's positive)
- $TSEM signed agreements for InP epiwafers.
- Management explicitly said its IQE agreement was signed to secure the "strategic III-V epiwafer supply required for that roadmap"
- IQE signed another ~$14M mysterious AI DC contract.
The only part that's still playing out with my earlier thesis is IQE converting their latent/underutilized capacity toward AI DC segment, to match peers like Landmark in the space (which takes time, like slightly over a year if I remember correctly).
There's some national security implications that I'll avoid talking about that makes them more important.
But basically:
FY2025 revenue: £97.3m
FY2026 guidance: over £126.5m
They're rapidly growing again in the optical sector, out of bank debt/distressed liquidation state, and remains a critical chokepoint in Western optical supply chains.
Now... with new agreements with your leading photonics companies for revenue growth, and players like Macom serving as a soft backstop.
After a thesis gets validated, typically I just sit back and enjoy growth of a business.
↗ Quoting @Lee_Trades
$IQE$AXTI$LITE$MTSI$TSEM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AXTIlong |
+5.4% | -5.6% | -16.4% | — | -0.1% |
| $LITElong |
+5.2% | -0.1% | +5.3% | — | +10.2% |
| $MTSIlong |
+3.1% | -13.3% | -10.5% | — | -7.2% |
| $TSEMlong |
+5.0% | -11.5% | -16.4% | — | -10.1% |
| $IQElong |
| | | | |
Sivers found a small Series B company that raised $3m last year that achieved 200-250mw per emitter apparently.
$SIVE can maybe combine that with their high wavelength DFB array, and maybe make something extremely high power like eg. 8/16 × 200-250mw for high aggregate output.
Program was focused on "need for higher power, more wavelengths" for CPO, so that's my guess.
$SIVE
@JoelLikesTurtle That's literally the earliest timeframe possible for CPO scale up early volumes if you look at $LITE and $COHR earnings.
And giving that specific timeframe is actually extremely bullish.
$LITE$COHR
$SIVE announces a $3.4M development program with SemiNex!
For CPO, DFB laser arrays, and optical amplifiers.
Early production is targeted H2 2027 (in line with early scale up CPO timelines)
Seemed weird to me at first given product overlap, since SemiNex is a much smaller Series B company...
But then I got reminded of a less explicit version of $SPCX + Cursor relationship (derisking by working together first).
There's probably something interesting Sivers found in this company.
$SIVE$SPCX
Is it just me, or is the list of 3 letter optical jargon never ending?
We have LPO, LRO, NPO, XPO, CPO, OBO, and others for approaches.
Then InP, EML, ELS, OCS, SOI, and others to add to the random terms.
Even the industry events with OCP or OFC get their three letter names.
People who have followed me on my optical bottleneck scavenger hunt with $SOI or $IQE might know a lot by now.
But wouldn’t new followers might be super confused…
$SOI$IQE
@stockprodigyman My takeaway was that $SIVE / Win, Sumitomo, Furukawa, and other qualified CW merchant laser suppliers...
Are going to become a lot more important in the near future.
$SIVE
My main takeaway was that your merchant CW laser suppliers seem to be EXTREMELY IMPORTANT now.
But TLDR of $COHR earnings:
"given the demand that we see in our DC business with transceivers, I don’t see any time in the near future where we would be selling indium phosphide lasers externally"
- Ton more value placed on companies that sell InP lasers externally if $AAOI can't doesn't enough capacity for first gen-CPO deployments, $COHR not selling externally...
I guess that's why $MTSI said a ton of customers are approaching them with urgency for InP CW DFB lasers (and they dont even have meaningful capacity coming online until EOY 2027)
$AAOI -> Internal
$COHR -> Internal
Buyers -> fewer places to look for capacity.
"Our backlog now extends out, fiscal 2027 is basically completely booked out. We are booked really through the end of calendar 2027" [ Massive massive demand visibility]
- Coherent also mentioned LTAs spanning end of decade. So this kinda reinforces what $POET CEO said at their AGM that the "big 3" are fully sold out next 2 years.
"we’re not constrained in the assembly and test capacity right now. We’re really just constrained by the ramp of the indium phosphide production"
- Just for the bottleneck bros in terms of assembly/test not a bottleneck.
"absolutely no push-out of CPO demand. In fact, it has been the opposite. We have seen demand increase and request from customers’ demand getting pulled in"
"we continue to expect revenue from CPO for scale-up applications to start to flow in the second half of calendar 2027"
- Big read through on other CPO players for scale up if $LITE, $COHR reaffirm revenue from CPO scale up coming h2027.
- "quarterly revenue exceeding $3 billion by the end of fiscal 2027"
- $COHR revenue go brrr
So for regular numbers it's:
- $2.046B revenue (+13.3% Q/Q, +33.8% Y/Y), main revenue ramp looks to be happening entering Q4 into 2027
- Non-GAAP gross margins: 40.2%
Next quarter guide is:
- Revenue: $2.2–$2.4B revenue
- Non-GAAP gross margins: 39.5-41.5%
Basically:
$1.69B -> $1.81B -> $2.05B -> ~$2.30B -> $3.0B (end of FY 2027)
~39% -> 39.6% -> 40.2% -> ~40.5% (gross margins)
For operating margins:
18.0% -> 19.5% -> 19.9% -> 20.3% -> 21.8%
Little less impressed compared to $LITE margin growth in terms of profitability, but revenue scale for $COHR growing rapidly.
↗ Quoting @LightLogix
$COHR$AAOI$MTSI$POET$LITE
@LightLogix Yeah looking at $COHR earnings now, pretty excited about the implications, will post soon
$COHR
@mikealfred Bears are going back into hibernation after seeing all these AI earning reports from $NBIS to $LITE.
$NBIS$LITE
I've been pretty vocally bearish on $CRWV since last year compared to $NBIS and other neoclouds.
Demand isn't really much of a problem with their $100B+ backlog, their revenue + 59% adjusted EBITDA margin looks good.
But underlying financing methods is really bad...
Coreweave's debt interest (eg. Q2 interest expense reached $640m), which eats into FCF way too much...
That figure is like 42% of Coreweaves $1.51B adjusted EBITDA for reference.
$CRWV$NBIS
$NBIS outlook is pretty insane yet again.
$582.3M revenue (+454% Y/Y, +46% Q/Q) off ~50% adjusted EBITDA margin (AI Cloud). $8.04B cash on hand.
Reiterates financial guide (2026 revenue: $3.0–$3.4B
2026 EoY ARR: $7–$9B), I was hoping for a raise, but it's already massive growth.
Not really about this quarter financials, but these signals:
- "We could sell our entire 2027 capacity on these terms today." massive visibility on demand
- "4 customer agreements averaging over $1B+ each in contract value"
- Around 70% of Q2 deals included customer prepayments
- Contracted power guidance was raised again, from more ~4+ GW to 5 GW. (this used to be a concern vs. $IREN debate, but Nebius power guidance keeps going through the roof).
- Expects $9B+ of prepayments in 2026 and says it has $40B+ of commitments.
- annual contract value per MW keeps going brrr (>$40M/mw for Q3 short term capacity deals)
Same bear story will always be there (eg. large $5.66B of capex with current GAAP net loss), but demand is extreme with massive visibility, with increasing AI Cloud adjusted EBITDA margins ( 24% -> 45% -> 50% progression)
We kinda got this read through from all your hyperscaler cloud earnings and $CRWV backlog yesterday, but glad it's showing up in Weebius's earnings.
$NBIS$IREN$CRWV
$AEHR receives another $22M follow on order for AI processor wafer level burn in systems.
By their lead AI processor company.
It’s cool to see this tiny company grow up so fast across so many verticals (memory, silicon photonics, etc).
Up +5.39% premarket off the news. https://t.co/YkOtELzkmo https://t.co/MhEQmNgAek
↗ Quoting @aleabitoreddit
$AEHR
Pretty sure $SIVE had Lightmatter, Celestial, Lightelligence, and Ayar as customers way early on before.
And they all ended up ~4B+ companies after starting off small. So I'm sure they know what to do with promising private company acquisitions.
There's not really much distressed public companies that offer optical transceiver designs other than maybe OE Solutions I think around ~$200m, but not sure how their progress is going with 800g/1.6T pluggables.
$SIVE
No, because $AAOI said that their scarce capacity is dedicated internally toward making their own 800G/1.6T optical transceivers.
Which they said would be a 20-40% demand imbalance even if all their capacity come online.
It's not a bad thing to have too much demand, that you can't expand to new product lines.
$AAOI
- Because newer 1.6T optical transceivers and CPO volumes haven't ramped yet. $SIVE is targeting all the next generation optical shifts.
This comes from a misunderstanding of architectural shifts, you won't get 9 figure revenue in 2024 if customer CPO scale up deployments start in 2028.
- $SIVE has 130+ employees and if I remember correctly, 1/4th to 1/3d were PHDs.
Lot of what they do is IP and they use Win Semi, external foundries for volume ramp. If they did assembly like $FN or $COHR, you would see employee count balloon.
Not quite sure why you say a customer supplying to $JBL, $GFS, Ayar, $POET, and many other hyperscaler suppliers is a hopeless case.
Probably one of the most unique ones I've seen.
$SIVE$FN$COHR$JBL$GFS$POET
 @aleabitoreddit
Aug 14, 2026 · 00:38 ET
stock