Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
I said $LITE went from $3b to $60B+ over a 2-3 year timeframe, especially due from Cloud Light acquisition in late 2023, that multiplied TAM by 5x+.
Since they started off in the EML laser / optical component chokepoint originally before M&A.
$SIVE has the potential to do the same starting off in the CW laser chokepoint.
But it does require something like a successful M&A down pluggables or optical engines/ELS.
To capture more revenue off things like completed transceivers $AAOI, if they want to get to a similar scale. And my take was NASDAQ listing is necessary to unlock more funding to do so.
$LITE$SIVE$AAOI
So this is just what I'm seeing with $SIVE and the CW DFB laser chokepoint right now.
From optical earnings:
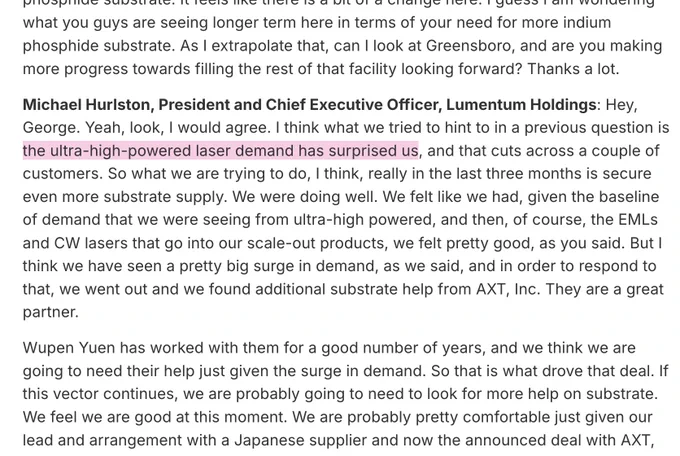
1. $LITE: unexpected demand and imbalance for UHP CW lasers.
- Had ability to price up ASP for lasers.
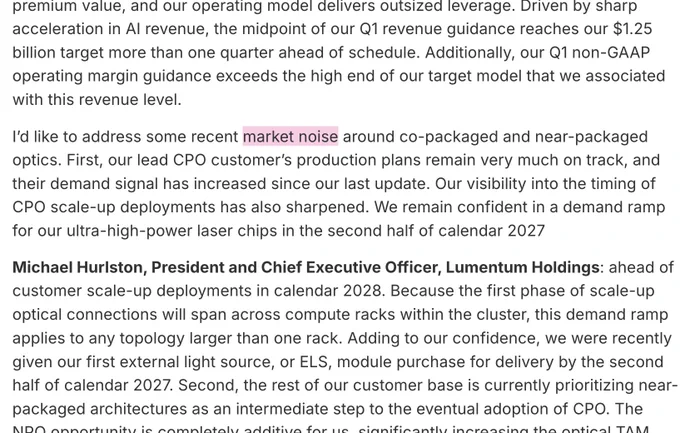
- Scale up CPO on track for H2 2027 shipments, called out any CPO scale up delay rumors as noise.
Lumentum confirmed timelines (that CPO players like Sivers sold off of misleading reports from), high margins, and extreme demand for qualified CW lasers.
2. $AAOI: doesn’t have enough CW laser capacity because of too much optical transceiver demand.
- Not meaningfully participating in first-gen CPO deployments, with $MTSI not looking like they're in it either but focusing on NPO. Haven't seen much with $SMTC after their HieFo acqusition.
- Called lasers as the bottleneck within a 20-40% demand imbalance for transceivers.
- Says customers approaching them every week asking them for supply + to move faster.
AOI confirmed demand imbalances + bottlenecks for lasers. And we got an even smaller pool for first-gen CPO players.
3. Both $AAOI and $LITE claimed Chinese players were years behind for CPO lasers and far behind stated claims in qualified capacity.
- $AAOI said 2-3 years+ behind with CPO lasers.
- $LITE said they haven't seen anything like Chinese claims in terms of outputs (and no recourse if it's false).
Reaffirms moat for CPO related lasers, and no flooding from some shortseller claims on the optical sector.
4. $MTSI said that many customers are approaching them with urgency due to the general supply shortage of indium phosphide DFB lasers.
Again, puts Sivers in the that bottleneck, giving them likely more customer demand .
Among $COHR ($72.54B), $LITE ($66.57B), $AVGO ($2.13T):
It's very special you get one of the public 4 Western CPO leaders at a ~$1.5B MC with $SIVE.
Feels like my thesis with both:
- The CW bottleneck that I predicted
- CW laser chokepoint (where there's only a few CPO players, at least for gen-1)
Got validated from earnings, now it's just waiting for the inflection points of next optical architecture shifts.
$SIVE$LITE$AAOI$MTSI$SMTC$COHR$AVGO
@MaxChua16 The Serenity Awarness Fund would have bought 1/6th of $SIVE and $AAOI
$SIVE$AAOI
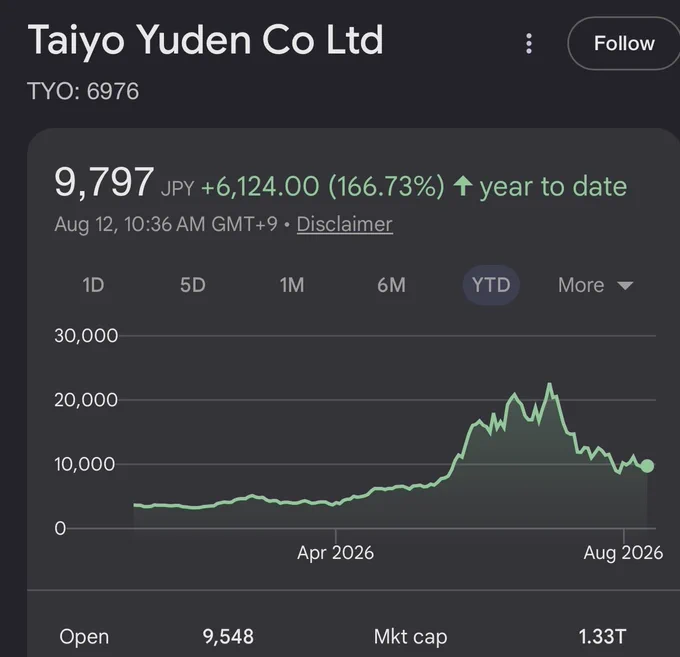
What a legend, Situational Awareness bought 1/6th of the entire company of Taiyo Yuden.
Pretty wild to see this unfolding. https://t.co/nBQW5DOZ5f https://t.co/6wg8xZncto
↗ Quoting @aleabitoreddit
$TYOYY
It was reported today that Leopold’s Situational Awareness acquired 11.62% of Taiyo Yuden (6976).
Up from 5.99% as of July 16th.
I do agree with his position (if he still has it) in terms of how valuable this MLCC manufacturer is to global AI supply chains. https://t.co/fAQNpAFfhU https://t.co/ezksKxgBWk
↗ Quoting @aleabitoreddit
$6976
I didn’t know Leopold was a fellow MLCC bottleneck investor in Taiyo Yuden (6976)
It’s been disclosed today that Situational Awareness owns 5.99% of the company with a ~ ¥17,446/share avg as of June 29th.
Current prices are ¥9,797.
I actually added some today to show support since Taiyo Yuden is one of the largest % MLCC manufacturers globally.
$6976
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $6976long |
| | | | |
@PatientGS Nah, $SMCI gave blowout projections for 2027 with that ~$70B revenue guidance relative to their $20B MC.
I still think it should get rerated. Just a bit annoying I couldn’t get clear answers for margin estimates.
$SMCI
Bro Charles the $SMCI CEO needs to become a politician.
I’ve never seen a guy dodge so many questions on a Q&A earnings transcript before.
- “what’s your 2027 gross margins”
A: “we look forward to growing them
- “do you anticipate margins to improve September?”
A: September. Which is September?
$SMCI
$LITE earnings transcript TLDRs:
- "Our visibility into the timing of CPO scale-up deployments has also sharpened. We remain confident in a demand ramp for our ultra-high-power laser chips in the second half of calendar 2027"
H2 2027 start of CPO scale up ramp confirmed from Lumentum for their lead customer.
- "We were recently given our first external light source, or ELS, module purchase for delivery by the second half of calendar 2027"
ELS industry ramp timelines
- "The NPO opportunity is completely additive for us, significantly increasing the optical TAM."
More TAM for laser chokepoint club
- "we expect the 1.6T transceiver uptake to intensify starting in fiscal Q1 and sustain through calendar 2027."
- "Even in CW, we’ve been surprised at our ability to price up"
Positive pricing power for $SIVE and the other CW laser players.
- "As a result, we are able to command a nice price premium that we expect to sustain, as these Chinese if these Chinese guys come online.
I caution people also, I think people are some of these Chinese laser suppliers are not delivering in the market today, so they have there is no recourse when they throw out these big numbers. We have not seen anything like that to date in terms of their output."
Chinese players are more behind than markets expect, corroborated by $AAOI and $LITE.
- "We are way behind in our shipments, unfortunately, on high-powered lasers"
"The demand signal has increased, and we are very much further behind relative to our ability to supply."
Extreme demand imbalance for UHP CW laser capacity, continued demand imbalance for EML. Shipping roughly +$50M year end -> $100m+ ("triple digit quarter") into much larger H2 2027 and 2028 scale up demand,.
- "So what we are trying to do, I think, really in the last three months is secure even more substrate supply" (because of demand imbalance), "we found additional substrate help from $AXTI They are a great partner."
Hello InP substrate bottleneck.
TLDR:
- Lumentum CPO scale up H2 2027 shipments got confirmed, dismissed any "delay" news as market "noise". (one delay report caused so much damage, and it took Nvidia, Lumentum, and all these companies weeks to do damage control).
- CW lasers demand ramp second half of 2027
- Extreme demand imbalance for UHP CW laser capacity surprised Lumentum
- UHP lasers commands very high margins and is able to price up CW laser capacity.
- China further behind in the laser/capacity angle.
Basically just validated timelines + demand/pricing for Western CW laser players.
CW laser scarcity is already happening before the main volume ramp even begins...
↗ Quoting @aleabitoreddit
$LITE$SIVE$AAOI$AXTI
Insane earnings today for the AI theme with $CRWV, $SMCI, and $LITE.
Coreweave: Absurd ~$104B+ backlog, which doesn't include $25B+ of new customer agreements added in early Q3.
Compute demand read through for Neoclouds is enormous (For Nebius, Iren and others)
Supermicro: Absurd $65-72B in revenue guidance, adding $60B+ in new orders...
AI DC buildout read through is just enormous.
Lumentum: $808M -> $1.01B -> $1.25B revenue ramp, with operating margins growing quarter after quarter.
Photonics players just keeps printing.
TLDR: Every layer of the AI buildout goes brrrrr, and it's showing up in earnings.
$CRWV$SMCI$LITE$NBIS$IREN
@throw_away_9264 Yep, I still think markets are correct to apply discounts to $SMCI given history with compliance failures.
Definitely not for everyone
$SMCI
@KHqmjz If you apply their net margin for 2026 so far, $SMCI is around ~7.7%.
If they do $70B revenue for H1 2026 with the same net margins, would be round ~4.1x forward earnings.
$SMCI
$SMCI 2027 guidance was actually unholy: $65-$72 billion FY 2027 revenue guidance...
vs. ~$52.4B expected, a casual +$16.1B above consensus.
SMCI logged a massive $60B+ in news order from this earnings.
That timeline is also interesting when they announced a plan to co-build $SPCX + xAI DCs "within a year" back in June..
But if SMCI sustain 10-15% gross margins off that ~$70B revenue guidance... I think there's a lot of room for rerating given MC is ~$20B (NFA, I have short term positions in SMCI now from this ER).
Most important thing is learning about 2027 margins from call today.
$SMCI$SPCX
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $SMCIlong |
+19.0% | +18.4% | +18.3% | — | +29.9% |
| $SPCXlong |
+9.6% | +7.5% | +11.2% | — | +13.2% |
$AAOI: "We just can’t make enough of them [CPO lasers] to be involved in their current first-generation [CPO] deployments because there’s just not enough capacity.
We have to prioritize our ability to make lasers for our own transceivers first"
This is just for early CPO related deployment read through.
$AAOI
$LITE earnings are out, very strong earnings:
Revenue: $1.01B, +24.5% Q/Q, +109.3% Y/Y growth
vs. ~$984.6M
Adj. EPS: $3.23 vs. ~$2.95
Gross Margin (non-gaap): 50.4% / Operating margin (non-gaap) 36.6%
Q1 FY2027 guidance is probably more important:
Revenue: $1.225–1.275B vs. ~$1.16B
Adj. EPS: $4.05–4.35 vs. ~$3.63
Operating margin (non-gaap) of 39.5% - 40.5%
In terms of notes:
Sees: "Increasing demand for ultra-high-power CPO lasers, an initial order for ELS modules"
- Great read through on other CPO players like $SIVEF, $COHR, and others. (maybe not AAOI since they're missing out on first-gen deployments)
- "Breath of NPO engagements are the first signs that optics are starting to penetrate in-rack connectivity, significantly upping our optical TAM"
- Revenue projections "reaching our target model more than a quarter ahead of schedule."
Extremely strong earnings as expected, you have revenue going from:
$808M -> $1.01B -> $1.25B while operating margin keeps increasing... Just my first impressions.
Most important thing is the earnings call coming up soon.
$LITE$SIVEF$COHR$AAOI
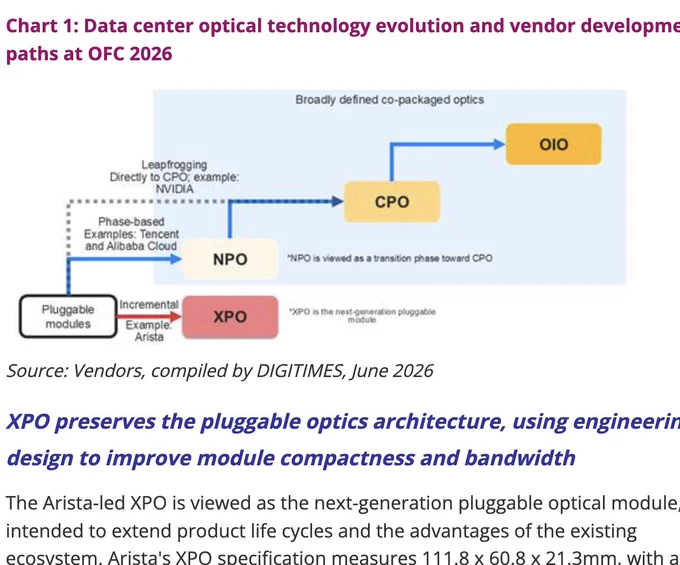
@NicolaRussoIT Not as familiar with adoption read through with $ANET XPO MSA (ik $MSFT has been the most openly supportive).. so can't really give a good answer to implications on other players like $POET.
$ANET$XPO$MSA$MSFT$POET
Just putting it out there for people that think AAOI is a one year cycle...
$AAOI projects their ELSFP capacity for CPO to be 400K/units a month in 2028.
400k * ~$400 ELS ASP (GS assumptions) = + another ~$1.92B 2028 annualized revenue capacity added as a new distinct (>50% gross margin) product line.
On top of their existing 2027 projections (eg. ~$5.6B annualized transceiver revenue off $471m/month entering H2).
TAM for 1.6T also goes brrr so I'd expect their end of H2 2027 projections to go up as more capacity comes online...
For certain optical names, it's one cycle (eg. 1.6T, CPO scale out/up, NPO etc. ), stacked on top of one another... stacked on top of another... with TAM + margins stacking like minions after Anivia uses W in line.
Rather than one-and-done off of one year.
This is a stark contrast to some other sectors where growth is likely to decelerate after maybe 1 year of triple digit Y/Y revenue growth.
$AAOI
@Yangyftz Looks like normal market volatility to me. I think a successful IPO from Unitree might bring up the robotics sector as a whole near-term.
Regardless, I see Harmonic Drive long-term to have record revenue numbers coming from humanoid ramp as robots scale up to the millions.
$6324
uhhh... the Unitree IPO is more than 8000 times oversubscribed by retail investors.
The demand for pure play humanoid companies is absolutely enormous?
I'm personally in the US-based Agility Robotics club (Softbank, $NVDA, $AMZN, Foxconn, etc), at $2.5B premoney via $CCXI.
And my take is that Unitree likely opening at $30B+ (from pre-ipo perps), might bring the leading US players some more attention in a week or two.
Regardless that's just absurd demand.
$NVDA$AMZN$CCXI
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMZNlong |
-2.1% | -6.0% | -9.2% | — | -10.4% |
| $CCXIlong |
+1.7% | +6.8% | -18.0% | — | -28.0% |
| $NVDAlong |
-0.0% | +3.4% | +2.8% | — | +5.1% |
I’m just posting about stuff I find interesting, and some signals thematically in terms of revenue inflection points.
I don’t own $RIOT myself and can’t give buy recommendations, so in the end up to you.
They did contract roughly ~$455M annual revenue from that deal, and a second catalyst to think about might be the 2028 Bitcoin.
So some of these names with dual exposure might get a lot of attention H1 2028.
$RIOT$BTC
Woah, $RIOT announced a $9.1B deal with Anthropic, with a possible contract extending to $16.1B, over 20Y.
$AMD also exercised its option to expand its existing deal with Riot. (And they still have another 1 GW campus they have LOI with for a tenant)
In terms of timelines, seem like most of the Colo basket have their revenue inflections hit H2 2027?
(Eg. Riot Anthropic deal targets Dec 2027 for first 96 MW, AMD full 50 MW - May 2027)
It’s cute to see all the former miners like $IREN and co. grow up.
$RIOT$AMD$IREN
Be Barrons:
- Wants to write about optical supply supply chains like $AAOI
- Hiring DPT: who needs engineers to write about this something this simple? Let’s find underpaid political philosophy backgrounds.
- proceeds to find a new hire from nonprofit communication consulting
- first day on job: gets paid to model revenue ramp/margins projections, CW laser bottlenecks, internal capacity
- New hire: “I don’t understand this sht”, “looks like a memestock”
Barrons: “Memestock? looks like our next article, I don’t understand either”.
$AAOI
Now that markets are hosting a laser party again from $SIVE, OE Solutions, $LITE, Coherent, to $AAOI.
There’s a pretty interesting study:
Both from Fidelity and a UC Berkeley research paper, that the best investors are the ones who either…
- Anecdotally forgot about their account (Fidelity)
- Didn’t actively trade/overtrade (18.5% return from infrequent traders vs. 11.4%).
Not any advice, but some of these anecdotes might be helpful to retail to read in general…
Since I witnessed a lot capitulation off memory, photonics, or thematic volatility, just for retail not have positions on a sharp recovery.
Having conviction also usually people in that “not overtrading” camp, since it helps to not overtrade in drops or see opportunities to cost average.
$SIVE$LITE$AAOI$COHR
I think we already got too many hints from $AAOI earnings about demand 20-40% imbalance for optical transivers with lasers as a bottleneck.
And $POET stating big 3 are completely sold out of capacity next 2 years during their AGM.
I don’t give earnings up or down predictions since it’s a coin flip most of the time. But I can say that a lot of pricing happens before earnings, unless there’s something very unexpected.
Regardless I expect $LITE earnings to come out really strong, and I primary use it as a read through for your other laser players.
$AAOI$POET$LITE
Just some near term events:
- OCP APAC tomorrow (Ayar, Lightmatter, $AMD, $NVDA) and your CPO players are giving announcements/updates.
This should be a catalyst for certain optical players.
- Earnings week: with $ASTS, $RKLB reporting today (space), $LITE on Tuesday (photonics), $NBIS in the middle of the week (Neocloud), and more.
- Unitree IPO subscriptions opened up today and Listing is expected this month.
Should be a potential catalyst for the humanoid + robotics sector if it opens up well eg. $CCXI.
Fun week ahead.
$AMD$NVDA$ASTS$RKLB$LITE$NBIS$CCXI

 @aleabitoreddit
Aug 12, 2026 · 04:07 ET
stock