Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
共和党が議会で多数派を維持できたら、トランプが成人1人につき5,000ドルを配ると約束している理由が、正直よく分からない。(総額約1.35兆ドル)
それより、アメリカ中のトイレを、日本にあるような便座が温かくなるTOTO(5332.T)のトイレにアップグレードしたほうが、支持率はもっと上がるんじゃないかと思う。
計算してみた:
3億3,500万台のトイレをTOTO UltraMax II + S7Aに交換すると、約9,900億ドル。
設置費用まで含めると、総額は約1.3兆ドル。
僕の案のほうがかなり安い。
↗ Quoting @jijicom
$5332.T
@zsummer931 There’s a $600m ATM which presents near term structural overhang (usually a month or so) of selling pressure.
$AAOI inflection point should be somewhere near the end of Q2 2027.
So still quite a lot of time to go.
$AAOI
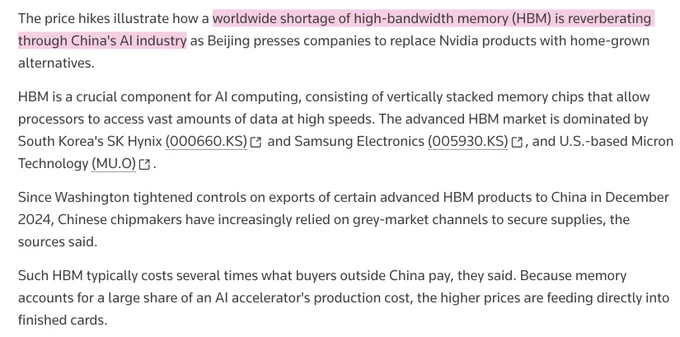
Wow, HBM reportedly drove up AI accelerator/card prices by 20-50% in China.
So $SKHY, Samsung, $MU, should be happy to hear this:
- Huawei has raised indicated pricing for the Ascend 950DT 20–50% above quotes from just 2 months ago
- Cambricon's upcoming 690 is reportedly +20–30%
Reuters stated that HBM acquired through grey market channels in China can cost several times regular pricing.
As someone who is long memory, I'm happy about memory causing this much inflation.
$SKHY$MU$SSNLF
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MUlong |
-0.2% | +0.0% | — | — | +9.4% |
| $SKHYlong |
+0.9% | -2.8% | — | — | -2.2% |
| $SSNLFlong |
— | — | — | — | — |
Anthropic's Economic Scenario publication was a pretty interesting read:
1. Anthropic's "extreme" scenario has GDP growth reaching 15.4% in 2030
So around 7.3x current rates (~2.1% Y/Y), which is consistent with what Elon Musk is saying about outgrowing the national debt with AI.
2. Almost all of the divergence happens after 2027.
Their model shows relatively little separation in 2026-2027, then the curves bend sharply into 2028-2030.
So my read is that it points to 2026-2027 as buildout years and 2028-2030 as economic acceleration.
Kinda gets mapped as well when you look at $AMZN / $META / $GOOGL capex, and short term FCF headwinds (but massive projected profitability post 2028)
3. In an extreme scenario, unemployment of knowledge workers goes to 17.9%. With 11.9% economy-wide unemployment
"At the individual level, it means coders and call service center agents may have to switch to jobs like electrician and nurse, which are less exposed to AI."
GG computer science majors.
4. Non-cognitive wages: +33.6% vs. baseline in an extreme scenario.
So your electricians/construction-type labor becomes extremely valuable? (but this isn't factoring in humanoids yet...)
Whereas -11.5% for knowledge workers in 2030 vs. baseline.
5. Aggregate capital income is ~81% higher than it would have been without AI
Productivity explodes -> aggregate labor income barely changes -> essentially all of the incremental GDP accrues to capital.
So that makes ownership of capital rather than labor... so equities like compute, power, semis, networking, robotics, etc. become pretty important...
TLDR:
- Economic growth go brr
- Jobs that require thinking = unemployment + lower wages
- Physical labor = more important, like electricians.
- AI equities go brrr.
$AMZN$META$GOOGL
Citibank TMT: "lasers and optical fibers are being positioned as the "next HBM."
I've been talking about lasers like $LITE / $AAOI since 2025... and architectural shifts toward CW, ahead of the current industry consensus.
And fully agree with Lightmatter/Citi.
Just for reference:
For lasers: $LITE / $SIVE / $AAOI / $COHR / $MTSI / Furukawa / Sumitomo are your better known ones.
For fiber: $GLW / Furukawa / Fujikura / Sumitomo are your more well-known exposure (obviously a lot more in the supply chain) *disclosure, personal exposure to theme
With added commentary that: "Tight supply conditions will support a scarcity premium for these assets."
We're already seeing price hikes with lasers as seen with $SIVE channel checks at CIOE 2026 Shenzhen today + $LITE commentary from earnings.
So I think the 2027–2028 photonics supercycle will look a lot like memory did in 2025–2026.
Especially as optical content/GPU-ASIC goes up significantly per Goldman Sachs revised estimates...
↗ Quoting @aleabitoreddit
$LITE$AAOI$SIVE$COHR$MTSI$GLW
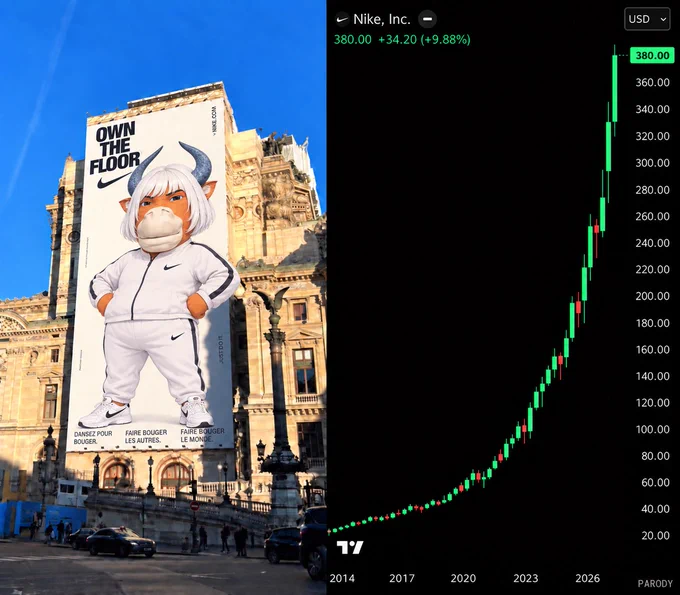
$NIKE 只需要做一件事,就能挽救自己的品牌形象 https://t.co/mhV2qUSSM3 https://t.co/kefGbNrlEr
↗ Quoting @alphaguytrading
$NKE
Special thank you to awodias for the crowdsourced channel check all the way from CIOE 2026 Shenzhen!
- Confirmed that $SIVE is actively engaged with Chinese pluggable makers
- $SIVE has raised lasers prices given tight supply
- 70mW lasers seem the most tight given association with 800g pluggables
It’s pretty cool that our little community reaches all the way around the world.
(Also thank you if other people did channel checks and I missed it, this was the first one I saw)
↗ Quoting @awodias
$SIVE
Goldman Sachs in their recent note upgraded their global optical module market forecast to:
- $67.7 billion (+33% revision) for 2026
- $131.4 billion (+81% revision) for 2027
- $148.5 billion (+115% revision) for 2028
For $NVDA Rubin Ultra, GS increased its modeled optical modules per GPU:
1.6T: 0 -> 2
3.2T: 3 -> 5
GS also raised their 1.6T and above forecast for 2027 by 61%... so that's also very material, with 80% silicon photonics penetration rate estimated.
So more optical content per chip = a lot more CW lasers, more SOI substrates, happy optical companies.
$NVDA
Okay I know this is US time and this is a Taiwan stock...
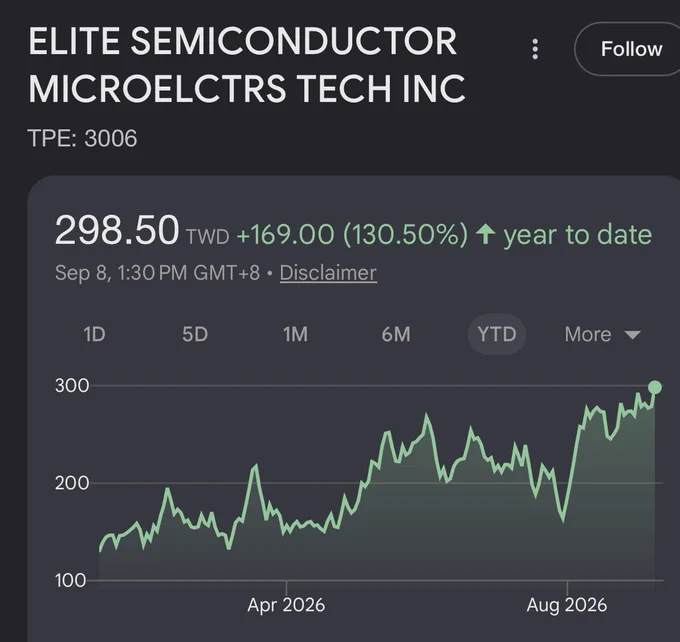
But I really am starting to think $ESMT (3006) can cook like $SNDK. And I’m excited.
So hopefully in a few months, people can something say similar...
FUN FACT CHAT:
Did you know.. 1 old DDR2 memory chip is.. ~$0.96? (from LCSC data)
Obviously different per spec since some can be $2.5...
But if you 3x ASP Hike this.
That's a whole... ~$2 added to final BOM cost.
So about the same cost as a $COST hot dog.
It goes into things like a D-Link security camera, maybe like $33 final cost...
and adds like $2. (which people won't mind)
But... 3X ASP hike to ESMT? Is very, very material.
That's just for one product category, and there's many others from SLC NAND (eg. +120–170% H2) to NOR Flash products for H2 ASP hike projections.
And my favorite thing is, they've already shown they're willing to partake in the price hike games (seems like there's a long way to go)…
Currently they make ~$111M net income a month from July earnings ($2.8B MC), which annualized is like ~2.1X P/E. *I have positions.
So... I think $ESMT has room to cook like masterchef Sandisk.
TLDR:
- Repeated rounds of price hiking = seems absurd for the company's net income... but has potential due to starting low component cost.
- Reminds me of early $SNDK but for other segments (legacy/niche memory).
↗ Quoting @yukimamax
$ESMT$SNDK$COST
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $COSTlong |
-0.8% | -1.0% | — | — | +0.0% |
| $SNDKlong |
+1.5% | -11.9% | — | — | +0.1% |
| $ESMTlong |
— | — | — | — | — |
@OInvests My 1 $IREN share is also cooking today.
$IREN
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $IRENlong |
-3.3% | -11.4% | — | — | -12.9% |
$NBIS is back, and coming in hot with a new partnership with $PLTR.
Palantir also named Nebius its preferred sovereign AI infrastructure partner.
The implications are potentially significant considering Palantir’s existing relations with the US Gov + Enterprises. https://t.co/izCDuR4r6Q https://t.co/1CKhfpy1BO
↗ Quoting @aleabitoreddit
$NBIS$PLTR
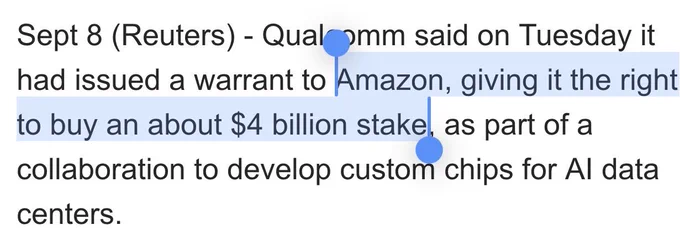
$AMZN signs a new deal with $QCOM, giving Amazon the right to buy a ~$4B stake of Qualcomm through warrants.
At this rate.. Amazon will be more of a semi ETF than $NVDA?
Given their existing equity/warrants with AlChip, $MRVL, $ALAB, $AAOI, and others.
This of course is linked with up to $60B in milestone revenue from Amazon/Qualcomm custom silicon partnership.
Good for both companies, moreso Qualcomm.
$AMZN$QCOM$NVDA$MRVL$ALAB$AAOI
@tcuso14 I still hold the same opinion that $HOOD should prioritize international equities and helping retail compound net worth through portfolio diversification.
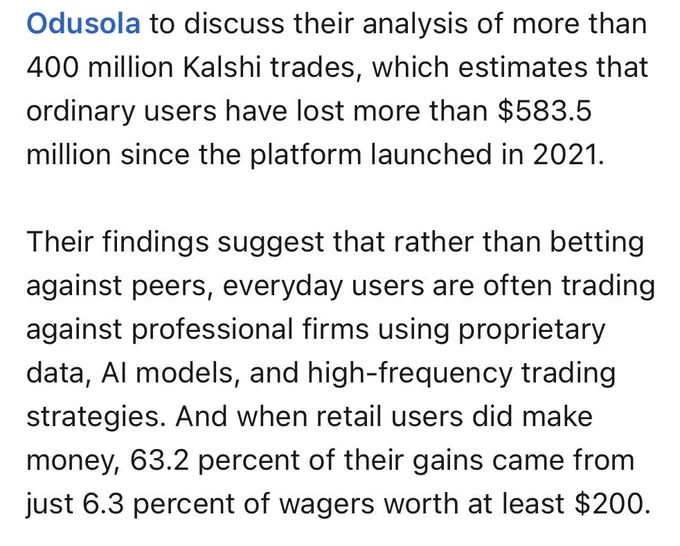
Instead of maximizing monetization through prediction markets where retail has lost a ton on aggregate.
$HOOD
Wow, $HOOD has taken minority ownership in Crypto.com.
It does feel like the future of the finance industry is slowly consolidating around Stripe/Robinhood.
Especially after the successful expansion of Robinhood Chain, Prediction Markets, and Credit Cards/Banking.
$HOOD
 @aleabitoreddit
Sep 08, 2026 · 03:56 ET
stock
1st mention
trade
position
📈 market call
So $INTC is raising PC CPU prices by 10% apparently in October per Digitimes, which I think markets might appreciate.
The legacy memory trade also just going brrr from August revenues:
-> ESMT revenue up ~+605% Y/Y, 16.4% M/M
Which is interesting given gross margins also rising tremendously too.
-> Etron revenue up +525% Y/Y, +6.4% M/M
Chairman says he sees growth momentum in memory to extend through 2028 or longer, potentially 2030. (which is very positive read through for ESMT given what Etron sells) *own ESMT/Etron
-> Winbond revenue up +289.43% Y/Y, up 2% M/M
Their president says memory supply and demand are expected to be even tighter in 2027 than in 2026.
-> Macronix revenue up +218.5% Y/Y, +5.4% M/M
Says SLC NAND, eMMC, NOR remain tight (kinda known there).
So... if you think your 80%-100% type revenue growth players are insane.
Check out legacy memory (operating income is even more hilarious). There's a few more where ~ modeled forward P/E values of like 2-3 from my estimates.
I personally find the theme a better value investing type idea than your 16 P/E no-growth dividend companies.
$INTC$ESMT$ETRON$WINBOND$MACRONIX
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $INTClong |
+1.7% | -7.0% | — | — | +15.1% |
| $ESMTlong |
— | — | — | — | — |
| $ETRONlong |
| | | | |
| $MACRONIXlong |
| | | | |
| $WINBONDlong |
| | | | |
Yes, 300m laser capacity H2 2028 seems like a realistic target for $SIVE.
It looks really large relative to global 2026 supply but if you factor if you factor in 100M+ CW DFB coming from Glasgow alone.
And expansion of all the other foundries, it looks reasonable.
They also might have 1 other foundry they might not have mentioned yet (we'll see). Since they've only made announcements for 2 of the 3 external partners they talked about a few years ago.
$SIVE
I use CIG for read through on Western markets, since they disclosed 5 CW laser supply agreements. But I remember likely $MSFT and $CSCO were optical customers.
Some of the more interesting companies were Nanjing Casela / 南京镭芯光电 (private) and Suzhou Dingxin / 苏州鼎芯光电 (private, but has a public parent via Yongding) for their potential CW laser sources.
But even after that, their filings showed they plan to stockpile CW lasers for next few years to avoid future bottlenecks.
I don't know enough about Cambridge fundamentals to comment on how well they might perform in the future.
$MSFT$CSCO
Glad $SIVE is attending CIOE Shenzen and hope my followers can go too!
If you want my read on current landscape:
-> Chinese pluggable makers like CIG (剑桥科技) are facing severe shortages in 70mW-200mW lasers.
If you look at filings from CIG, they claim "substantially longer delivery times and deposits to secure capacity” along with statements of shortages.
-> Innolight and others were also looking to secure multiple laser suppliers with LTAs recently from their filings.
On the US side of things:
-> $COHR was a major merchant laser supplier before, but largely withdrew from the market after rerouting them internally.
"I do not see any time in the near future where we would be selling Indium Phosphide lasers externally." From their ER transcript.
And then likely turned into a buyer in an already supply constrained market... where
"over the long term, we will have some portion of our datacom transceivers that will be supported by external sources."
-> $AAOI not really known to be a merchant supplier, but said same thing about laser capacity being rerouted towards transceivers. And having to turn away customers for lasers.
-> For $LITE, they still supply lasers but stated: "We are commanding a significant price premium" for CW lasers
$LITE Wupen Yuen: "wherever they can get the laser source, they will use that solution to support their build-out."
So hinting... about customers just finding anything available due to shortages.
-> $MTSI has no meaningful capacity online now, but they're already stating customers are approaching them with urgency to secure CW laser supply.
-> Trendforce reported $AMD and hyperscaler CSPs are aggressively going out to secure CW laser supply to avoid future bottlenecks.
And then you have Europe...
Where $SIVE is coming online with "tremendous capacity available now" from their foundry partners.
With 100M+ laser capacity Q4 2027, and maybe if you look at their 2:1 ratio implying ~200M targeted laser capacity from external foundries.
They also happen to offer the same power range (70mW, 100 mW, 200mW) as the ones currently in shortage by pluggable makers in China.
There's a massive void to fill, so this dramatically increases the chance of converting customers. (esp. Supported by Lumentum statements)
My speculation was that some of the 6 active pluggable engagements were from China?
Which is why they're attending the conference.
So to any of my Chinese followers, maybe you can ask a few questions like:
- if Europe is a laser source geography, if Innolight/Eoptolink/Cambridge are considering $SIVE.
- if they're seeing ASP hikes in lasers, and what CW products are hardest to obtain
If you are attending CIOE in Shenzhen!
↗ Quoting @marketmind2344
$SIVE$COHR$AAOI$LITE$MTSI$AMD
@IkaKnight_ Buffett: Here's why Pepsi is compelling at 16 P/E and why we need to save up $300B+ for the next market correction.
Abel: We're gonna full send it into AI's next bottleneck
$PEP
Uhh chat, did we accidentally AI bottleneck-pill Warren Buffett's $BRK.B successor Greg Abel?
$BRK.B$GOOGL
Congrats, yeah anything $TSM affiliated has been on a tear recently.
I don't have any personal targets for $IQE, just seeing what happens.
I think my earlier thesis around latent capacity refactored toward AI DC segments, for Landmark-type rerating was validated with their statement today at least:
"The main investment really is mainly the downtime of the tool, because you actually take it off of production for a time, and that obviously is opportunity costs that are lost. I think it’s still a worthwhile investment. Even with that minimal investment, we are still not converting tools without customer commitments and secured demand on these tools."
But we'll see what happens since their main concern was resolving InP substrate constraints.
$TSM$IQE
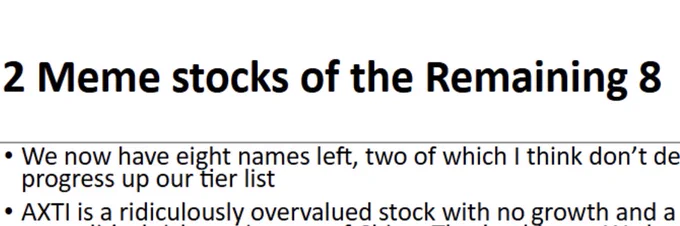
@AheadOfTmrw These "no growth meme stock" posts about $AXTI did not age well.
$AXTI
New report from Bloomberg on $IQE:
“indium phosphide substrates is emerging as a key risk for the semiconductor industry.”
I wonder who could have guessed this last year with $AXTI? https://t.co/ETW7Y2Pz7z https://t.co/xuSezBWFWO
↗ Quoting @aleabitoreddit
$IQE$AXTI
Of course, but it's just really exciting to think about these ideas sometimes.
I forgot to add in $AAOI as another example. Even though they do end-to-end pluggables, they're even potentially vertically integrating upstream too.
Think last ER they mentioned JVs with InP substrate makers... So reminds me of $COHR in a little way.
$AAOI$COHR
I'll let you decide that for yourself since that was an illustrative laser revenue modeling off $SIVE 100M CW DFB laser/year target.
But... do you want to know the main reason I like laser companies so much?
They don't just have to stay laser companies... just look at $LITE!
If we look at Lumentum's previous Cloud Light acqusition (pluggables)... it enabled:
- more than a 5X+ expansion in served opportunity inside DCs.
From Lumentum's OFC deck:
- ELS expansion from UHP laser chips was 2X TAM opportunity..
But selling lasers alone... just from one UHP laser fab was $5B in projected revenue capacity (their fab expected to ramp in early 2028), if we apply similar 55-65% CPO laser margin quotes by $AAOI.
So lasers by itself is very profitable, and despite industry capacity expansion, there would likely still be a demand imbalance for lasers.
Isn't that pretty cool?
So it's not quite just modeling component value for certain types of companies since they can keep growing into other products.
And you have new overlapping cycles eg. NPO/CPO/1.6T pluggables increasing demand.
So I'd personally assign higher premiums for laser companies over types of suppliers that stay in the same layer.
↗ Quoting @wannabepanacea
$SIVE$LITE$AAOI