Only on X, don’t trust fake accs
AI/Semi Supply Chains
NFA DYOR, no paid promos; may trade/hold names disc, views my own. Sharing free AI chokepoint research
Dumb Signal has archived 1,507 posts
from Serenity (@aleabitoreddit) and classified
153 as real trade calls — each priced the day it was
made and graded by direction-signed returns at 1D / 1W / 1M / 1Y, deletion-proof.
Is there any other industry... Where every investor is cheering for shortages and price hikes?
SED reported today that: Samsung / $SKHY "stockpiles have fallen to less than 10 days of supply, and a severe shortage could emerge next year, according to a new forecast"
KB Securities said that the memory market next year will see "the tightest supply conditions in history"
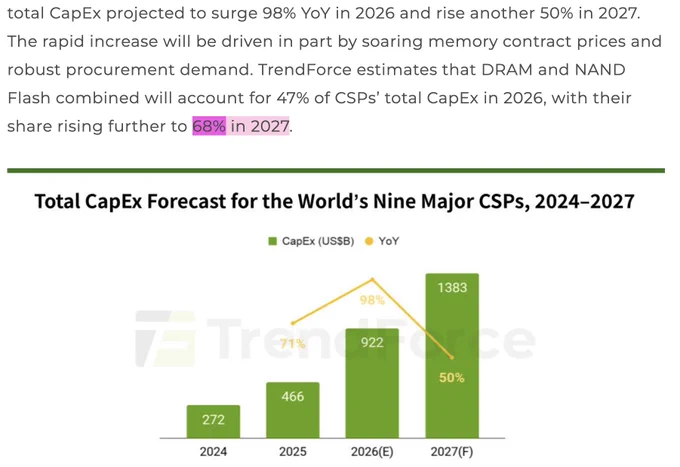
KB Securities projects memory's share of AI infrastructure costs to expand from 40% this year to 57% next year, with others like TrendForce placing next year's figure at 68% (total hyperscaler capex, pretty wild forecast attached)
"Both stocks have fallen 38% from their peaks over the past three months, pushing their price-to-earnings ratios based on next year's expected results down to about three times."
Likewise, commentary around Phison stated they expect extremely tight NAND supply in 2027, so hard to see memory flooding the market or prices collapsing next year...
They gave some color that "soaring NAND prices have forced some Chinese consumer module makers to liquidate inventory, giving Phison opportunities to buy lower-priced stock", so it does show some price declines can coexist with broader shortages.
TLDR: KOSPI + read through for other names like $MU / $SNDK might be happy for 2027 given demand causing shortages + infra spend share increase.
$SKHY$MU$SNDK$SSNLF$KOSPI
Got curious and decided to track which thesis of mine were still up 100%+ YTD after the recent drawdown:
1. $AXTI - InP substrates
2. $NBIS - Neoclouds
3. $MU - Memory
4. $INTC - Foundry
5. $LITE - Photonics
6. $IQE - Epiwafers
7. $AAOI - Photonics
8. $GDRZF - Venezuela
9. $AEHR - Machines
10. $EWY (volatility + underlying)
11. $RPI - AI orchestration
12. $SOI - SIlicon Photonics Substrates
13. $SNDK - Memory
14. $SIMO - Memory
15. $MRVL - ASICs
16. Nanya - memory
17. Unimicron - substrates
18. $ARM - CPUs
19. $SIVE - Photonics
From H1 2026, around 19 names across several themes up 100%+ still from the selection of winners.
Since many like $TSEM / $HPS.A / $LPK / $ALRIB fell out of the range. (obviously not all are green like Shunsin / $XFAB and disappointed by performance).
Regardless, glad a lot of my ideas turned out decently, rather than just being known for one like $AXTI. To the point the Chinese community gave my investing style a name "Perilla Leaf Theory".
Again not too sure if my new ideas replicate this performance again in H2 2026 or 2027...
For H2, my new thesis was on $CCXI for humanoids/downstream physical AI shift and ESMT for DDR2/DDR3/legacy memory.
But I'll keep sharing my core ideas and thought process for free so people can poke holes or debate it until things get validated.
$AXTI$NBIS$MU$INTC$LITE$IQE$AAOI$GDRZF$AEHR$EWY$RPI$SOI$SNDK$SIMO$MRVL$ARM$SIVE$TSEM$HPS.A$LPK$ALRIB$XFAB$CCXI
I get like 100 of these types of questions a day, I can’t just answer all of them.
Since you’ve asked 12 times: yes I still have exposure to all of them.
Cost averaged on a few, so as of today positions on:
Foci are up 53%
Xintec are up 53.1%
But still down -23% on Shunsin, -22% on Msscorp.
Main position I trimmed the most at a loss for tax harvesting was Auros after hybrid bonding industry delays.
I like to post thesis ideas, but try to keep portfolio management stuff private like tax loss harvesting or trimming.
I’ll post thesis research updates, like $TSM coupe confirming partnership with Shunsin. Or FAU bottleneck validation on Foci. Or hybrid bonding delays.
But in the end people should make their own decisions
$TSM$FOCI$XINTEC$SHUNSIN$MSSCORP$AUROS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $TSMlong |
+2.4% | +1.0% | — | — | +6.6% |
| $AUROSshort |
| | | | |
| $FOCIlong |
| | | | |
| $MSSCORPlong |
| | | | |
| $SHUNSINlong |
| | | | |
| $XINTEClong |
| | | | |
Oh cool! $SIVE also made it there on cnyes too (leading Taiwan financial media)!
The English translation might be off a bit, but this was summarizing Sivers surprising 100M+ CW DFB annual laser capacity expansion, ~ operational Q4 2027.
And how given historical ASP from previous year presentation slides, it could translate to $625M-$1.25B capacity revenue ceiling at full utilization.
Sivers might be of more interest given its partnerships with local foundries like Win Semi.
And since its downstream partners like Ayar (Mediatek / Alchip CPO partner) are heavily investing in Taiwanese optical supply chains.
↗ Quoting @aleabitoreddit
$SIVE
I didn’t know my ESMT thesis was making some rounds in Taiwanese media like Cnyes/Anue.
Just found it funny that I wanted to read about any recent commentary, then my name kept appearing…
Special thanks to BlockBeats for the original coverage. https://t.co/nS0lBHJmgH https://t.co/85HhMPoU8W
↗ Quoting @aleabitoreddit
$ESMT
@JensenHuang @ChaseLochmiller @OpenAI Wow, OpenAi’s Astra achieving AGI carries a lot more weight coming from the CEO of $NVDA.
$NVDA
I asked OpenAI Astra Ultra + Anthropic Fable 5.1 Max to make me a 5x-10x return type portfolio in 1 year.
Burnt a lot of credits, and the results are in:
OpenAI: - $KYTX (autoimmune CAR-T results)
- $PRQR (human RNA-editing datasets)
- $VSTM (KRAS cancer-drug)
- $CNTB (asthma and COPD)
- $RANI (oral biologics)
- $IVA (MASH)
- $SILC (networking + inference hardware)
- $AMPX (batteries)
- $EOSE (batteries)
- $ZVRA (rare-disease drug growth)
Anthropic: - $INO (respiratory papillomatosis)
- $CAPR (PDUFA for deramiocel)
- $GOSS (seralutinib)
- $SLS (Phase 3 binary)
- $IREN (familiar face)
- $WULF (familiar face)
- $OKLO (nuclear)
- $SMR (nuclear)
- $RGTI (quantum)
- $QBTS (quantum)
*Disclosure don't own any of these aside from 1 share in IREN, not a recommendation, just TLDR of LLM output for educational purposes.
So very interesting results:
Our beloved AGI Astra prefers really obscure biotech I've never heard about. And a few familiar names like $EOSE and $AMPX.
And Fable... yeah idk, feels like it learned a little too much from /r/wallstreetbets and X but maybe it's right, who knows.
Anyway no judgement, I'll save this and revisit it in a few months. If one of them actually delivers... I'll be impressed.
↗ Quoting @aleabitoreddit
$KYTX$PRQR$VSTM$CNTB$RANI$IVA$SILC$AMPX$EOSE$ZVRA$INO$CAPR$GOSS$SLS$IREN$WULF$OKLO$SMR$RGTI$QBTS
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $AMPXlong |
+5.1% | -4.6% | — | — | -2.1% |
| $CAPRlong |
-3.6% | -11.0% | — | — | +0.7% |
| $CNTBlong |
+3.8% | +10.9% | — | — | -40.2% |
| $EOSElong |
+10.8% | +1.8% | — | — | -21.0% |
| $GOSSlong |
+2.6% | -23.5% | — | — | -14.2% |
| $INOlong |
-0.7% | -12.6% | — | — | -14.0% |
| $IRENlong |
+5.0% | -1.9% | — | — | -8.5% |
| $IVAlong |
-2.3% | -15.9% | — | — | -31.2% |
| $KYTXlong |
-2.2% | -12.0% | — | — | -17.5% |
| $OKLOlong |
+4.9% | -12.2% | — | — | -10.3% |
| $PRQRlong |
-1.0% | -10.1% | — | — | -20.3% |
| $QBTSlong |
+6.6% | +1.3% | — | — | -0.1% |
| $RANIlong |
+0.8% | -2.6% | — | — | -8.6% |
| $RGTIlong |
+4.0% | +0.5% | — | — | +3.5% |
| $SILClong |
+6.2% | +3.4% | — | — | +28.5% |
| $SLSlong |
+0.7% | -16.7% | — | — | -11.2% |
| $SMRlong |
+15.3% | -11.2% | — | — | -18.6% |
| $VSTMlong |
-1.5% | -10.7% | — | — | -1.8% |
| $WULFlong |
+8.2% | +1.4% | — | — | -10.4% |
| $ZVRAlong |
+2.2% | -3.1% | — | — | -8.5% |
I’m not sure how OpenAI was likely holding off their IPO to 2027.
Because they had concerns about a $1T valuation 3 months ago.
Then Anthropic investors go and say **** it, lets one-up $SPCX and IPO at $2T next month?
$SPCX
Now that $MU to $SNDK have pulled a major recovery.
Good to have a reminder that the memory bottleneck hasn’t changed!
Same with CW lasers… substrates… or others.
But short term sentiment (depending on prices/macro) often does.
I think a lot of demand imbalances get worse than people expect:
- There’s some Japanese distributors in Nikkei today saying memory demand deficit has reached 40-60% (67-150% higher than supply). With general prices going up 50% by years end.
- $SPCX isn’t included in the $1.3T hyperscaler capex figures (I think Wells Fargo ets. ~$263b AI capex), so total capex figures might be surprising.
- $SNDK expects 80% gross margins to continue into 2030… (welcome to S&P 100)
- and once again you have long term visibility into 2031 now with companies like Samsung
Memory is very really volatile… some of my positions are up 270%+, so I find it a bit easier to hold through volatile periods.
But regardless, operating fundamentals doesn’t always align with short term price movements.
Same concept can be applied to other sectors.
↗ Quoting @aleabitoreddit
$MU$SNDK$SPCX
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MUlong |
-1.6% | -4.1% | — | — | +5.2% |
| $SNDKlong |
-0.1% | -6.1% | — | — | -0.0% |
| $SPCXlong |
+3.7% | +2.2% | — | — | +2.0% |
我觉得这种思路很好:借鉴我对 ESMT DDR2/DDR3 等老一代存储芯片的研究, 举一反三.
或者把我研究 $AAOI 时关于 CW 激光器供需失衡的思路, 应用到 A 股.
很开心看到大家学习我的思考方式,而不是照抄具体的股票, 并用这些思路去寻找自己看好的做多标的! https://t.co/pppIo47t15
↗ Quoting @lonlinlin001
$AAOI$ESMT
@kevs_World02 Some random $90m MC biotech company that I'd prefer not to mention lol.
It also really likes $OUST for some reason (don't have any).
$OUST
Let me get this straight chat… you have:
$NVDA 70% supply constrained revenue growth projections (would be 100%+)
$AVGO AI revenue growing 100%+ Y/Y for next 2 years from mid ~$50B -> $230B
OpenAI Astra blowing away AGI benchmarks and starting to train itself.
$MSFT / $GOOGL / $AMZN stating compute demand imbalances into next year, with Nvidia projecting $1.3T spend for 2027.
You’re seeing this flow through supply chains from Samsung 70% capacity LTAs into 2031 to Powertech advanced packaging capacity 100% booked into 2030.
Even your legacy players like Winbond are starting 2029-2030 allocations.
Markets always have temporary drawdowns and macro scares… but…
How can anyone not think AI stock go brrr?
$NVDA$AVGO$MSFT$GOOGL$AMZN
@rektusd101 I actually support $HOOD here, but agree with the $AMC CEO a narrow point:
That US needs clearer regulations on tokenized equities so they can be offered regularly in the states.
Just for people who are missing context:
$HOOD$AMC
From my channel checks, it appears Korean retail is firmly siding with $HOOD over the $AMC CEO.
Korean sources find the prospect of 40x leveraged Samsung / $SKHY a powerful enough argument to win the tokenization debate.
$HOOD$AMC$SKHY
So... here's my take on US / China tensions:
You have European monopolies like:
- $ASML (EUV)
- $SOI (Photonics-SOI)
- Zeiss SMT (ASML EUV supplier), Trumpf (ASML EUV laser supplier)
Japan has many near/complete monoplies like:
- TOK, JSR, ShinEstu, Fujifilm for EUV photoresist - 90-100% share
- coat/develop equiment with Tokyo Electron -90%+
- actinic EUV patterned mask inspection (Lasertec) -100% share
- EUV mask blanks (HOYA, AGC) ~93% share
- arf photoresist
- Nittobo T-Glass
- ABF film (Ajinomoto)
- lot of misc from specialty glassAGC, wafer thinning/grinding/dicing with Disco and others.
Then there's US allied countries like Taiwan eg. $TSM, Korean memory with $SKHY / Samsung.
US has EDA with Synopsys/Cadence, $LCRX / $KLA, $NVDA, and many downstream giants.
China has many chokepoints such as gallium, graphite, refined lithium, and others + benefits from cost mass production over many future supply chains (eg. robotics).
If I had to give my opinion on US / China supply chain wars:
- US is trying to achieve Western independence from China/Russia rare earths + materials supply, but took too long (should have been a priority last decade).
- China is trying to eliminate strategic chokepoint dependence and forcing US reliance on Chinese supply chains (as seen with Wf6)
It's a race on who achieves supply chain independence first to gain leverage over the other.
And fun thing is, AI acceleration kinda throws an unknown variable in terms of speeding up independence.
As well as open source efforts (eg. RISC-V), which China is heavily focusing on. So it's a weird paradox where US should theoretically support open source hardware development + open source AI, but it's also being exploited against them.
From a Chinese perspective, they're pressuring US supply chains by targeting Japan, which increases Western supply chain reliance on China.
And going down the list to eliminate competitor chokepoints internally by throwing subsidized spend into R&D. Or by acqusition as seen with China's acquisition of EU leaders like Ficontec.
America... they had all the cards initially, but I think they got too comfortable, and took too long to focus heavily on rare earths (recent funding is a good thing).
The earlier tariffs went the wrong way (socks, furniture, other exports), and pissed off allies in EU/Canada too.
Which could have been used for leverage for major chokepoints. But maybe they'll realize soon enough why allies are important.
Anyway, we'll see what happens, just my two cents about ongoing dynamics.
In an ideal world, everyone works together...
TLDR: Just some shower thoughts on how there's an unspoken race on who achieves supply chain independence first to gain leverage over the other.
↗ Quoting @aleabitoreddit
$ASML$SOI$TSM$SKHY$LRCX$KLA$NVDA$SNPS$CDNS
China reportedly halts some rare earth shipments to US.
Not a new blanket ban, or any mention of specific rare earths.
But… if I had to guess, Japan is usually a decent indicator of what’s actively important since Japan:
- “sources virtually all of its dysprosium and terbium from China.”
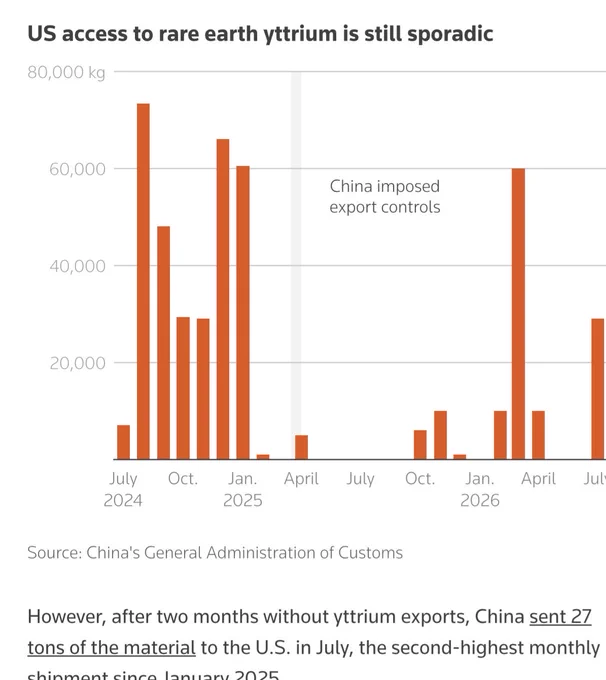
- gallium, dysprosium, terbium and yttrium from China to Japan all stood at “zero” in June.
- Shin-Etsu Chemical has reportedly suspended acceptance of new orders for magnets containing dysprosium.
- Global magnet producer Proterial had received no export licenses for Chinese dysprosium as of last month
The Reuters piece mentioned yttrium, gallium, terbium, indium phosphide, and tungsten as historical examples (doesn’t say what’s being targeted now).
On a side note, $LYC.AX is becoming one of the most important alternatives, as Japan has locked up 75% of Lynas’s medium/heavy rare-earth output. (8 tons of dysprosium + terbium in Q1)
Something fun I also read is that Japan’s deep sea resource is enormous (est. at 16 million tons of rare earth rich mud, but commercialization is post-2028)
But in the meantime, China seem to be choking off feedstock that would materially affect Japan.
Since you’ve already seen the WF6 Japanese industry stressed from tungsten related halts.
And indium/others earlier this year that is used to make InP substrates from Sumitomo/JX.
But still gradually allowing exports directly eg. $AXTI -> $LITE to allow US/China trade to continue, kinda disrupting that from time to time, then using that as leverage.
It’s interesting since Japan has so many different monopolies like ABF, so we’ll see if they do anything back.
But if I had to give a prediction, it does look like the US has a countdown timer until China becomes self-sufficient on semiconductors.
TLDR:
- rare earth disruption to US
- China actively targeting Japan for upstream feedstock (which goes to Us supply chains), probably want to focus on that
- many many second/third order effects from disruptions
- we’ll see what US/Japan wants to do back, but supply chain wars are being fought upstream.
$LYC$AXTI$LITE
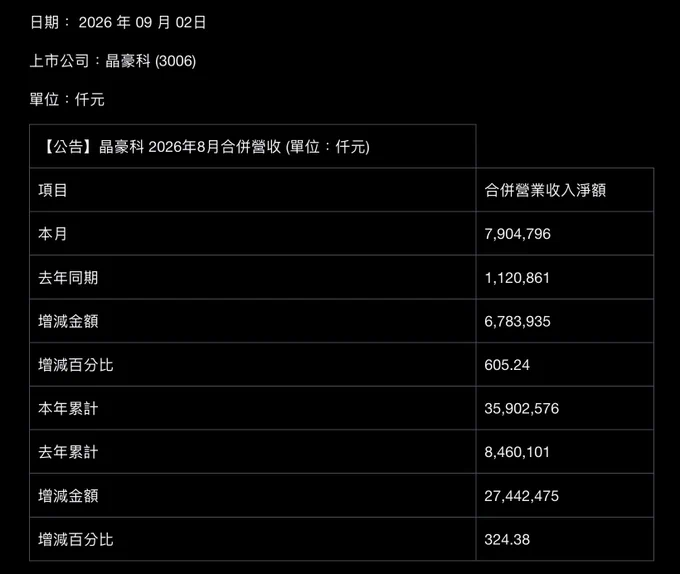
Just an update to my DDR2/DDR3 memory idea with ESMT. They reported August revenue (Taiwan sometimes does monthly reporting):
June revenue: ~$153M
July: ~$214M
August (new): ~$249M vs. $35.3m (last year)
Monthly revenue has increased ~63% in two months despite reportedly similar 2026 wafer allocations to 2025 (MoneyDJ report).
The profitability is already really high as seen with July's monthly revenue (where they reported ~$109M net income).
So if pricing holds, and revenue increases, that would be very nice...
Now a lot of US people don't really care since it's in Taiwan, but if you're in the $MU / $SKHY, $SNDK trade.
Just educational purposes, it's a second order effect where your leading memory players prioritize AI/DC higher end memory and reduce allocations to older generations (causing shortages).
But... DDR4 since prices going up too much, so older gen memory products (DDR4) are getting redesigned with older gen memory (DDR3). And DDR3 products with DDR2.
And so on. Causing cascading supply chain shortages.
(DDR2 for example is boring/old memory used for cameras, printers, automotive back in the 2000s and not many ppl make them anymore).
And even your old DDR2 suppliers like Winbond are gradually withdrawing from the market too...
So ESMT is the beneficiary of DDR3/DDR2 shortages.
TLDR:
ESMT August revenue was ~$249M, up from ~$214M last month.
↗ Quoting @aleabitoreddit
$ESMT$MU$SKHY$SNDK
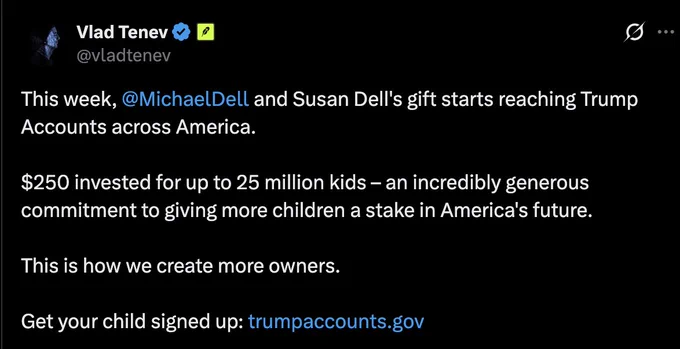
@sherlycrypt According to Vlad it's starting to be being distributed this week, which is the material thing for $HOOD (the pledge was awhile back)
$HOOD
$DELL founder is a legend.
The Dell family pledged $6.25B / $250 each to 25M children through Trump Accounts, with $HOOD (up 14.83%+ today) as the initial sole brokerage.
Little off topic but getting the public invested early is very meaningful compared to the dollar amount.
$DELL$HOOD
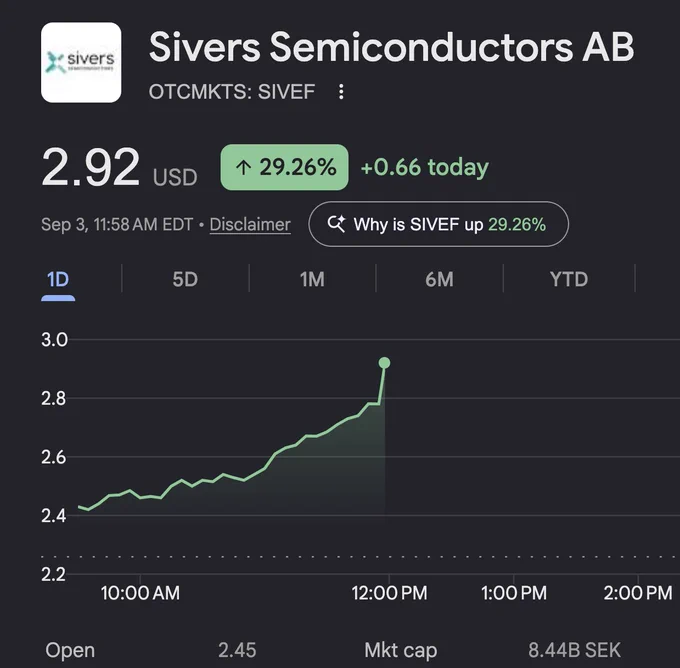
This is the correct response when looking at $SIVE >100m CW DFB extraordinary capacity disclosure.
To give some context, Trendforce July data cites global CW/EML capacity is roughly 608.4M/year (~50.7M monthly units annualized).
With $AVGO, $LITE, and Sumitomo making up ~335m/year combined.
By Q4 2027, it's likely a lot of these players will significantly expand capacity again, with broadcom citing 3x Y/Y growth. (also capacity not being 1:1 since many are allocated to EML or UHP CWs, etc).
But this capacity target would place Sivers in global Tier 1 laser supplier category.
With possibly low double digits global laser market share if you factor in their hybrid 2:1 manufacturing model.
This new disclosure is very exciting coming from a conservative company.
And sheds more light on why the $MRVL SVP cited Europe as a major geography when talking about laser supply chain sourcing.
↗ Quoting @LcubedInvest
$SIVE$AVGO$LITE$MRVL
@Shiboo9019 it's partly a defensive acquisition. $NVDA talks started after $CRM and other companies were reportedly approaching Hugging Face for an acquisition.
$NVDA$CRM
$NVDA acquires hugging face for $12,930,300,000.
Jensen stated the reason being:
- 18M+ devs use Hugging Face
- 3M+ models, 500k+ datasets, 1M+ apps
- 200k+ companies use the platformm
- support of open weight models
this almost reminds me of $MSFT buying Github?
$NVDA$MSFT
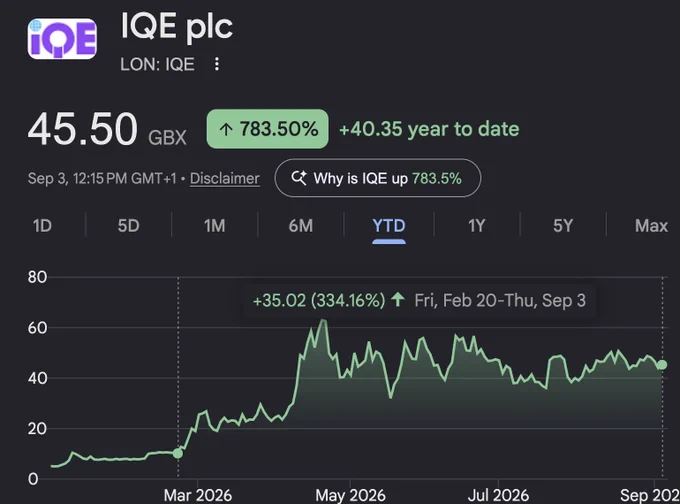
@KhalidIshaq85 Yes? I wrote my thesis on $IQE Q1 this year before $MTSI, $TSEM and the other material events came about.
$IQE$MTSI$TSEM
| return | 1D | 1W | 1M | 1Y | now |
|---|
| $MTSIlong |
+3.5% | +4.8% | — | — | +9.6% |
| $TSEMlong |
+7.8% | +0.9% | — | — | +10.3% |
| $IQElong |
| | | | |
$IQE is actually a quantum dot foundry leader believe it or not.
Today IQE announced a purchase agreement with Quintessent (top player in the QD space).
“As quantum dot lasers move to customer sampling.”
Your QD bros like $ALMU, QD Laser (6613), and others might finally start to see the light of day, with broader commercialization in the next few years.
Second order effects are QD machine chokepoints like $ALRIB that might capture more attention.
But TAM is typically pretty small on the QD material epi side of things. (No disclosure over $ figure), but good news nevertheless.
↗ Quoting @nabil_oneill
$IQE$ALMU$ALRIB
@Jayden11129225 Yes, so implications on their foundry parter allocations are a lot more meaningful from this disclosure.
$SIVE

 @aleabitoreddit
Sep 07, 2026 · 03:09 ET
stock